
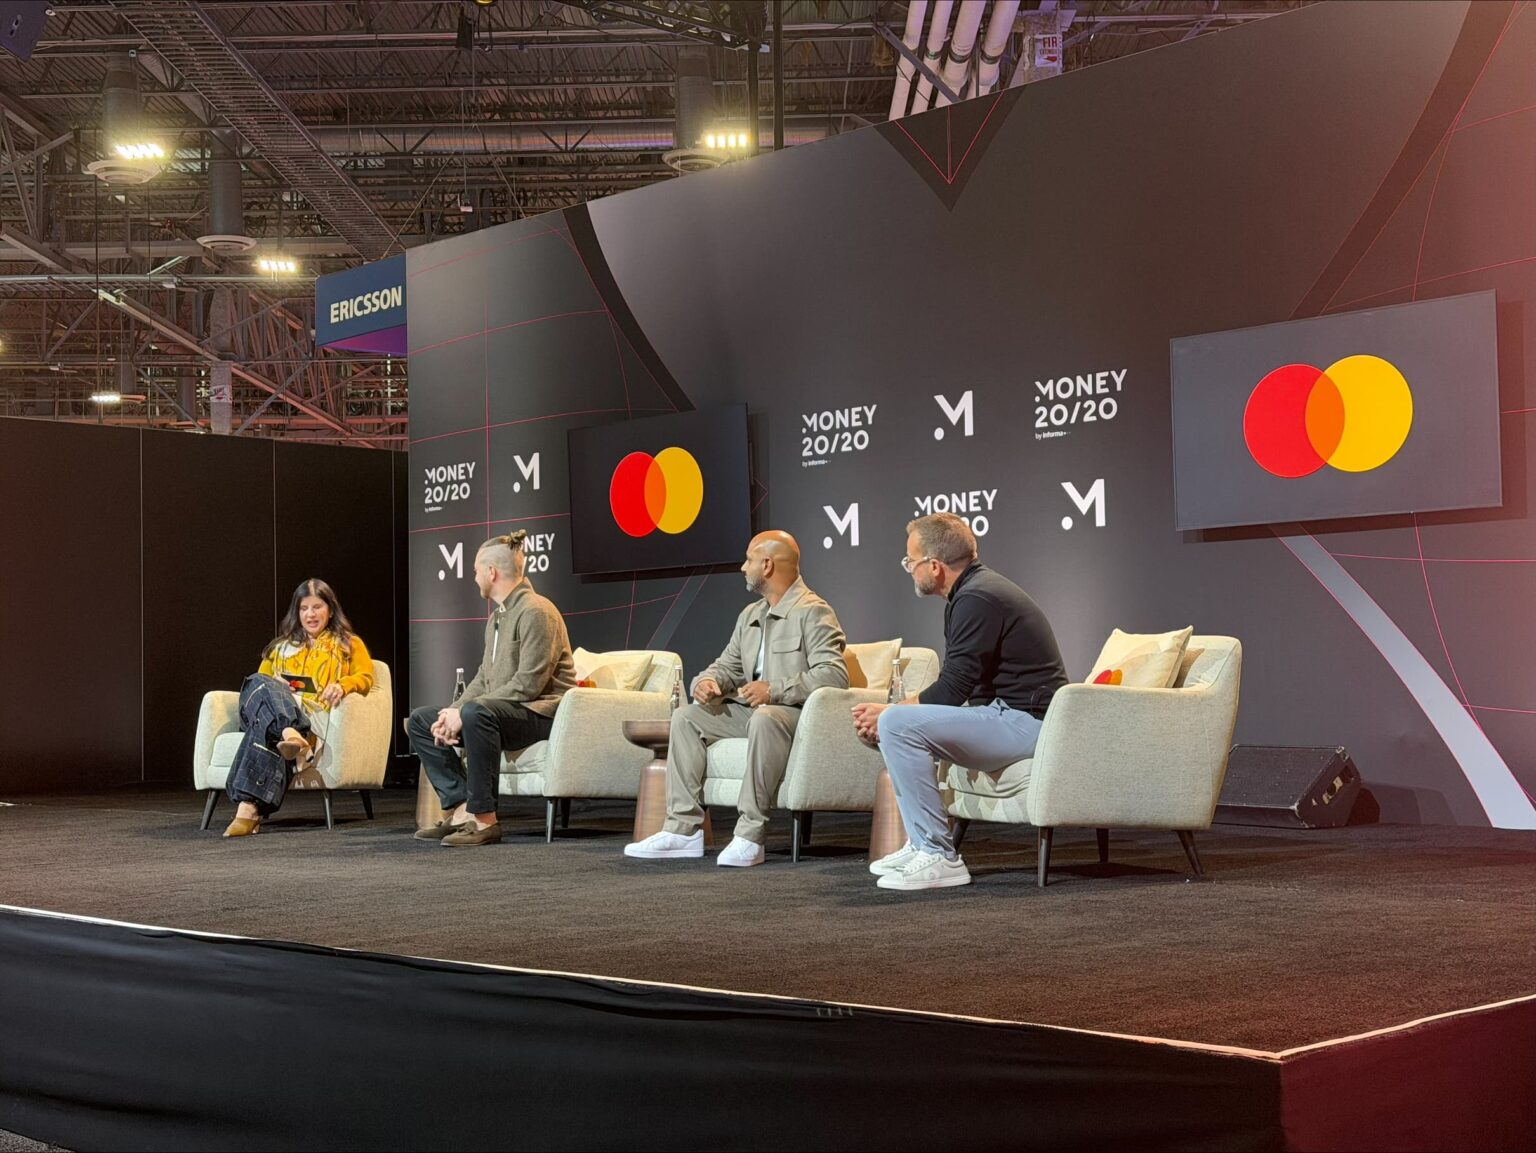
The first full day of Money20/20 USA in Las Vegas focused less on whether stablecoins and AI agents can function in financial transactions and more on what happens when automated payments go wrong. Across panels involving Mastercard, Citi, eBay, Payoneer, Skyfire and Forter, the recurring issue was accountability: how financial institutions identify an automated actor, establish authority and determine who bears losses when a transaction was not intended.
The discussion reflects a broader change in payments. Stablecoins are moving from primarily trading and crypto-market applications toward cross-border commerce, treasury and settlement. At the same time, AI agents are beginning to act on behalf of consumers and businesses, creating a new layer of automated financial activity. Both developments potentially reduce friction, but they also challenge established systems for fraud prevention, authentication and dispute resolution.
For banks, payment companies and merchants, the question is increasingly how to build controls around transactions that can occur faster and with less direct human intervention.
Stablecoin Payments Put Trust at the Center
Mastercard opened the discussion with its Stablecoin Security initiative, introduced by Ann Johnson, the company’s security-solutions executive. The system uses Mastercard’s fraud, identity and cyber intelligence accumulated over 16 years alongside blockchain analytics to generate a risk score for stablecoin payments at machine speed.
Mastercard said the service will launch initially in North America, with worldwide availability expected in 2027.
The underlying issue is straightforward: stablecoin transactions can move rapidly across wallets and jurisdictions, while the information needed to assess the parties involved may not always travel with the transaction.
Rajpal Khangura, co-founder and chief compliance officer of Keyrails, described the challenge from the perspective of cross-border commercial payments. His company handles trade payments for merchants, including businesses in markets such as Nigeria paying suppliers in China. Average transactions are between $250,000 and $350,000.
According to Khangura, customers increasingly want to understand not only transaction speed and cost but also the security of the wallet receiving the funds and the destination of the fiat currency.
That creates a complicated compliance problem when a wallet itself has not been sanctioned but has interacted with another wallet that has. Payment providers must also account for the risk policies of banks, liquidity providers and other institutions further down the transaction chain.
The issue illustrates a broader challenge for stablecoin infrastructure: transaction speed can improve without automatically improving the ability to identify counterparties or assess their risk.
How Stablecoin Payments Are Moving Beyond Crypto Trading
Stablecoins remain closely associated with cryptocurrency markets, but companies at Money20/20 emphasized their potential role in conventional payments.
Keith Vander Leest, who leads BVNK in the US and is now part of Mastercard, argued that stablecoin activity needs to shift further toward real-world payments rather than trading.
That transition requires infrastructure comparable to systems developed over decades in traditional finance.
Data and compliance become payment infrastructure
One recurring proposal was to attach more information to on-chain transactions.
Industry participants pointed to ISO 20022 messaging and Travel Rule information as examples of data that could strengthen compliance and transaction monitoring.
Alex Garn of Borderless highlighted approaches used by established instant-payment networks. In the UK, additional checks can occur when a new payee is added. In Brazil, Pix uses network-level fraud signals rather than relying exclusively on individual institutions.
The implication is significant for stablecoin networks. If risk controls are added only at individual wallets or payment providers, criminals may be able to exploit gaps between institutions. Network-level intelligence can potentially provide a broader view of transaction behavior.
The challenge is building those controls without undermining the speed and programmability that make stablecoins attractive in the first place.
Enterprise Adoption Shows a Gap Between Interest and Usage
A panel involving Payoneer, eBay and Citi highlighted another feature of the stablecoin market: corporate interest appears to be moving faster than actual everyday usage.
Nik Milanović of This Week in Fintech cited a Payoneer survey of 265 payments, treasury and finance leaders. The survey found that 69 per cent were already using stablecoins, while 41 per cent reported usage at meaningful scale.
Yet when Milanović asked the audience who had personally made a payment using a stablecoin, only six or seven people raised their hands.
That distinction matters. Institutional experimentation does not necessarily translate into consumer-facing adoption.
Renata Camera Santos, eBay’s head of wallet, said marketplaces need payment infrastructure that produces a consistent customer experience regardless of the underlying payment rail. That makes edge cases as important as the standard transaction.
For a global marketplace, a stablecoin payment must work across different currencies, jurisdictions, wallets, compliance requirements and customer protections. A faster settlement rail is not necessarily enough to justify replacing an established payment method.
Tokenised deposits offer another route
Citi’s Will Artingstall, head of banking as a service, said clients are increasingly asking about risk rather than simply the features of new payment technologies.
One area where Citi has seen stronger adoption is tokenised deposits. Unlike conventional stablecoin arrangements, customers can fund from an existing bank account without directly holding a wallet while the token is created and subsequently redeemed.
That model can reduce some of the operational complexity associated with self-custodied digital assets.
Rowland Berry of Payoneer also highlighted a fundamental regulatory principle: outsourcing parts of the technology stack does not necessarily transfer responsibility. The regulated institution holding the relevant licence can remain accountable for the activity.
AI Agents Create a New Payments Liability Problem
The same question becomes more complicated when the party initiating a payment is not a person but an AI agent.
At a Money20/20 session involving Mastercard, Skyfire and Forter, participants examined the infrastructure required for agentic commerce.
Ranjita Iyer, Mastercard’s executive vice president of services for North America, said the network expects agents could account for one transaction in ten by 2030, potentially sooner.
The forecast highlights a fundamental difference between conventional online commerce and agent-led transactions.
A human shopper can authenticate themselves, select a product and approve a payment. An AI agent may search across merchants, compare options, select a product and initiate payment based on instructions given earlier.
That creates several questions for merchants and financial institutions:
- Who does the agent represent?
- What authority has the owner granted it?
- What payment credential is it using?
- Was the transaction within the owner’s instructions?
- Who is responsible if the agent makes an unauthorized purchase?
Competing standards are emerging
Adam Davies, Forter’s director of AI strategy, said merchants need to establish the identity of an agent, the person or organization behind it and the authority under which it is acting.
Several competing approaches are already emerging, including Visa’s Trusted Agent Protocol, Google’s AP2, Mastercard’s Verifiable Intent and Stripe’s shared payment tokens.
The fragmentation creates a practical problem. Merchants cannot reasonably be expected to build separate infrastructure for every emerging agent-payment standard.
Amir Sarhangi of Skyfire argued that existing internet fraud systems were largely designed around human users and probabilistic assessments. Agentic commerce introduces demand for stronger evidence about who an automated actor represents.
Skyfire’s Know Your Agent token is designed to connect an agent with verified information about the business and user behind it. Forter can then use that information during checkout.
The objective is not necessarily to create a separate checkout process for AI. Instead, the industry is attempting to make an agent identifiable as an authorized representative of an existing customer.
Who Bears the Loss When an AI Agent Gets It Wrong?
The liability question may become one of the defining issues in agentic payments.
If an AI agent purchases an item that its owner did not intend to buy, conventional card-payment protections do not necessarily provide an equivalent framework for determining responsibility.
Mastercard’s Iyer raised the issue directly: payment networks need sufficient identity and intent information to determine liability when an automated transaction goes wrong.
This is different from ordinary fraud.
With traditional unauthorized payments, the central question may be whether someone other than the legitimate account holder initiated the transaction. With agentic commerce, the account holder may have explicitly authorized the agent but not necessarily the individual purchase.
The distinction could make intent data as important as identity data.
A payment system may eventually need to establish not only that an agent belongs to a verified user, but also what the user authorized that agent to do.
That creates technical, contractual and regulatory questions that remain unresolved.
Regulation Is Following the Technology
The policy debate at Money20/20 reflected a broader tension between regulation and technological development.
Former CFTC Chairman J. Christopher Giancarlo argued that regulators should allow commercial applications to develop before attempting to impose comprehensive rules. He cited the CFTC’s work on prediction markets as an example of an area where regulatory approaches continue to evolve.
Giancarlo also predicted that by 2040, anything of value capable of being tokenised will be tokenised.
That remains a forward-looking assessment rather than an established market outcome. The broader regulatory question is more immediate: which aspects of stablecoins and tokenised assets require existing financial rules, and where are new frameworks necessary?
The US regulatory landscape remains unsettled
The discussion took place roughly a month after the CLARITY Act failed a Senate procedural vote, leaving a major piece of proposed US digital-asset legislation unresolved.
The absence of comprehensive legislation does not mean the market operates without regulation. Banks, payment companies and other financial institutions remain subject to existing requirements covering areas such as anti-money-laundering controls, sanctions compliance, consumer protection and licensing.
The challenge is determining how those rules should apply when payments become programmable, tokenised and increasingly autonomous.
The Broader Payments Market Is Building Around Agents
The developments extended beyond conference panels.
Huntington launched The 1866 Studio, an agentic platform for small businesses built with Google Cloud.
Separately, Proof and Circle demonstrated an agent capable of establishing whom it represented before making a payment in USDC. Skyfire and Forter also formalized their partnership around agent verification and commerce.
These developments point toward a payments ecosystem in which identity verification, transaction authorization and payment execution increasingly operate together.
For banks and merchants, that could mean moving beyond the traditional model of authenticating a person at the point of payment. The infrastructure may instead need to authenticate an agent, verify its authority and preserve enough information to establish responsibility after the transaction.
Future Outlook for Stablecoins and Agentic Payments
Stablecoins and AI agents are developing along different technological paths, but the financial infrastructure required by both is beginning to converge around the same problems: identity, authorization, fraud detection, data sharing and liability.
Stablecoins need stronger compliance and risk controls if they are to expand from trading into mainstream commercial payments. AI agents require reliable ways to demonstrate who they represent and what they are permitted to do.
Neither technology eliminates the need for trust. Instead, both shift where that trust has to be established.
The emerging payments model may therefore depend less on whether transactions can be executed automatically and more on whether institutions can establish a reliable chain of identity, authority and accountability around those transactions.
Conclusion
The central discussion at Money20/20 USA was no longer whether stablecoins and AI agents can participate in financial transactions. Their technical capabilities are increasingly established.
The unresolved issue is responsibility.
For stablecoins, that means determining how transaction monitoring, sanctions screening and fraud intelligence can operate at the speed of blockchain payments. For AI agents, it means establishing identity and intent before automated purchases occur and determining liability when an agent acts outside its owner’s expectations.
As banks, payment networks and technology companies develop standards for these systems, the ability to assign responsibility may become as important as transaction speed or cost. The next phase of digital payments will therefore depend not only on automation, but on the infrastructure that makes automated financial activity accountable.

