
Introduction
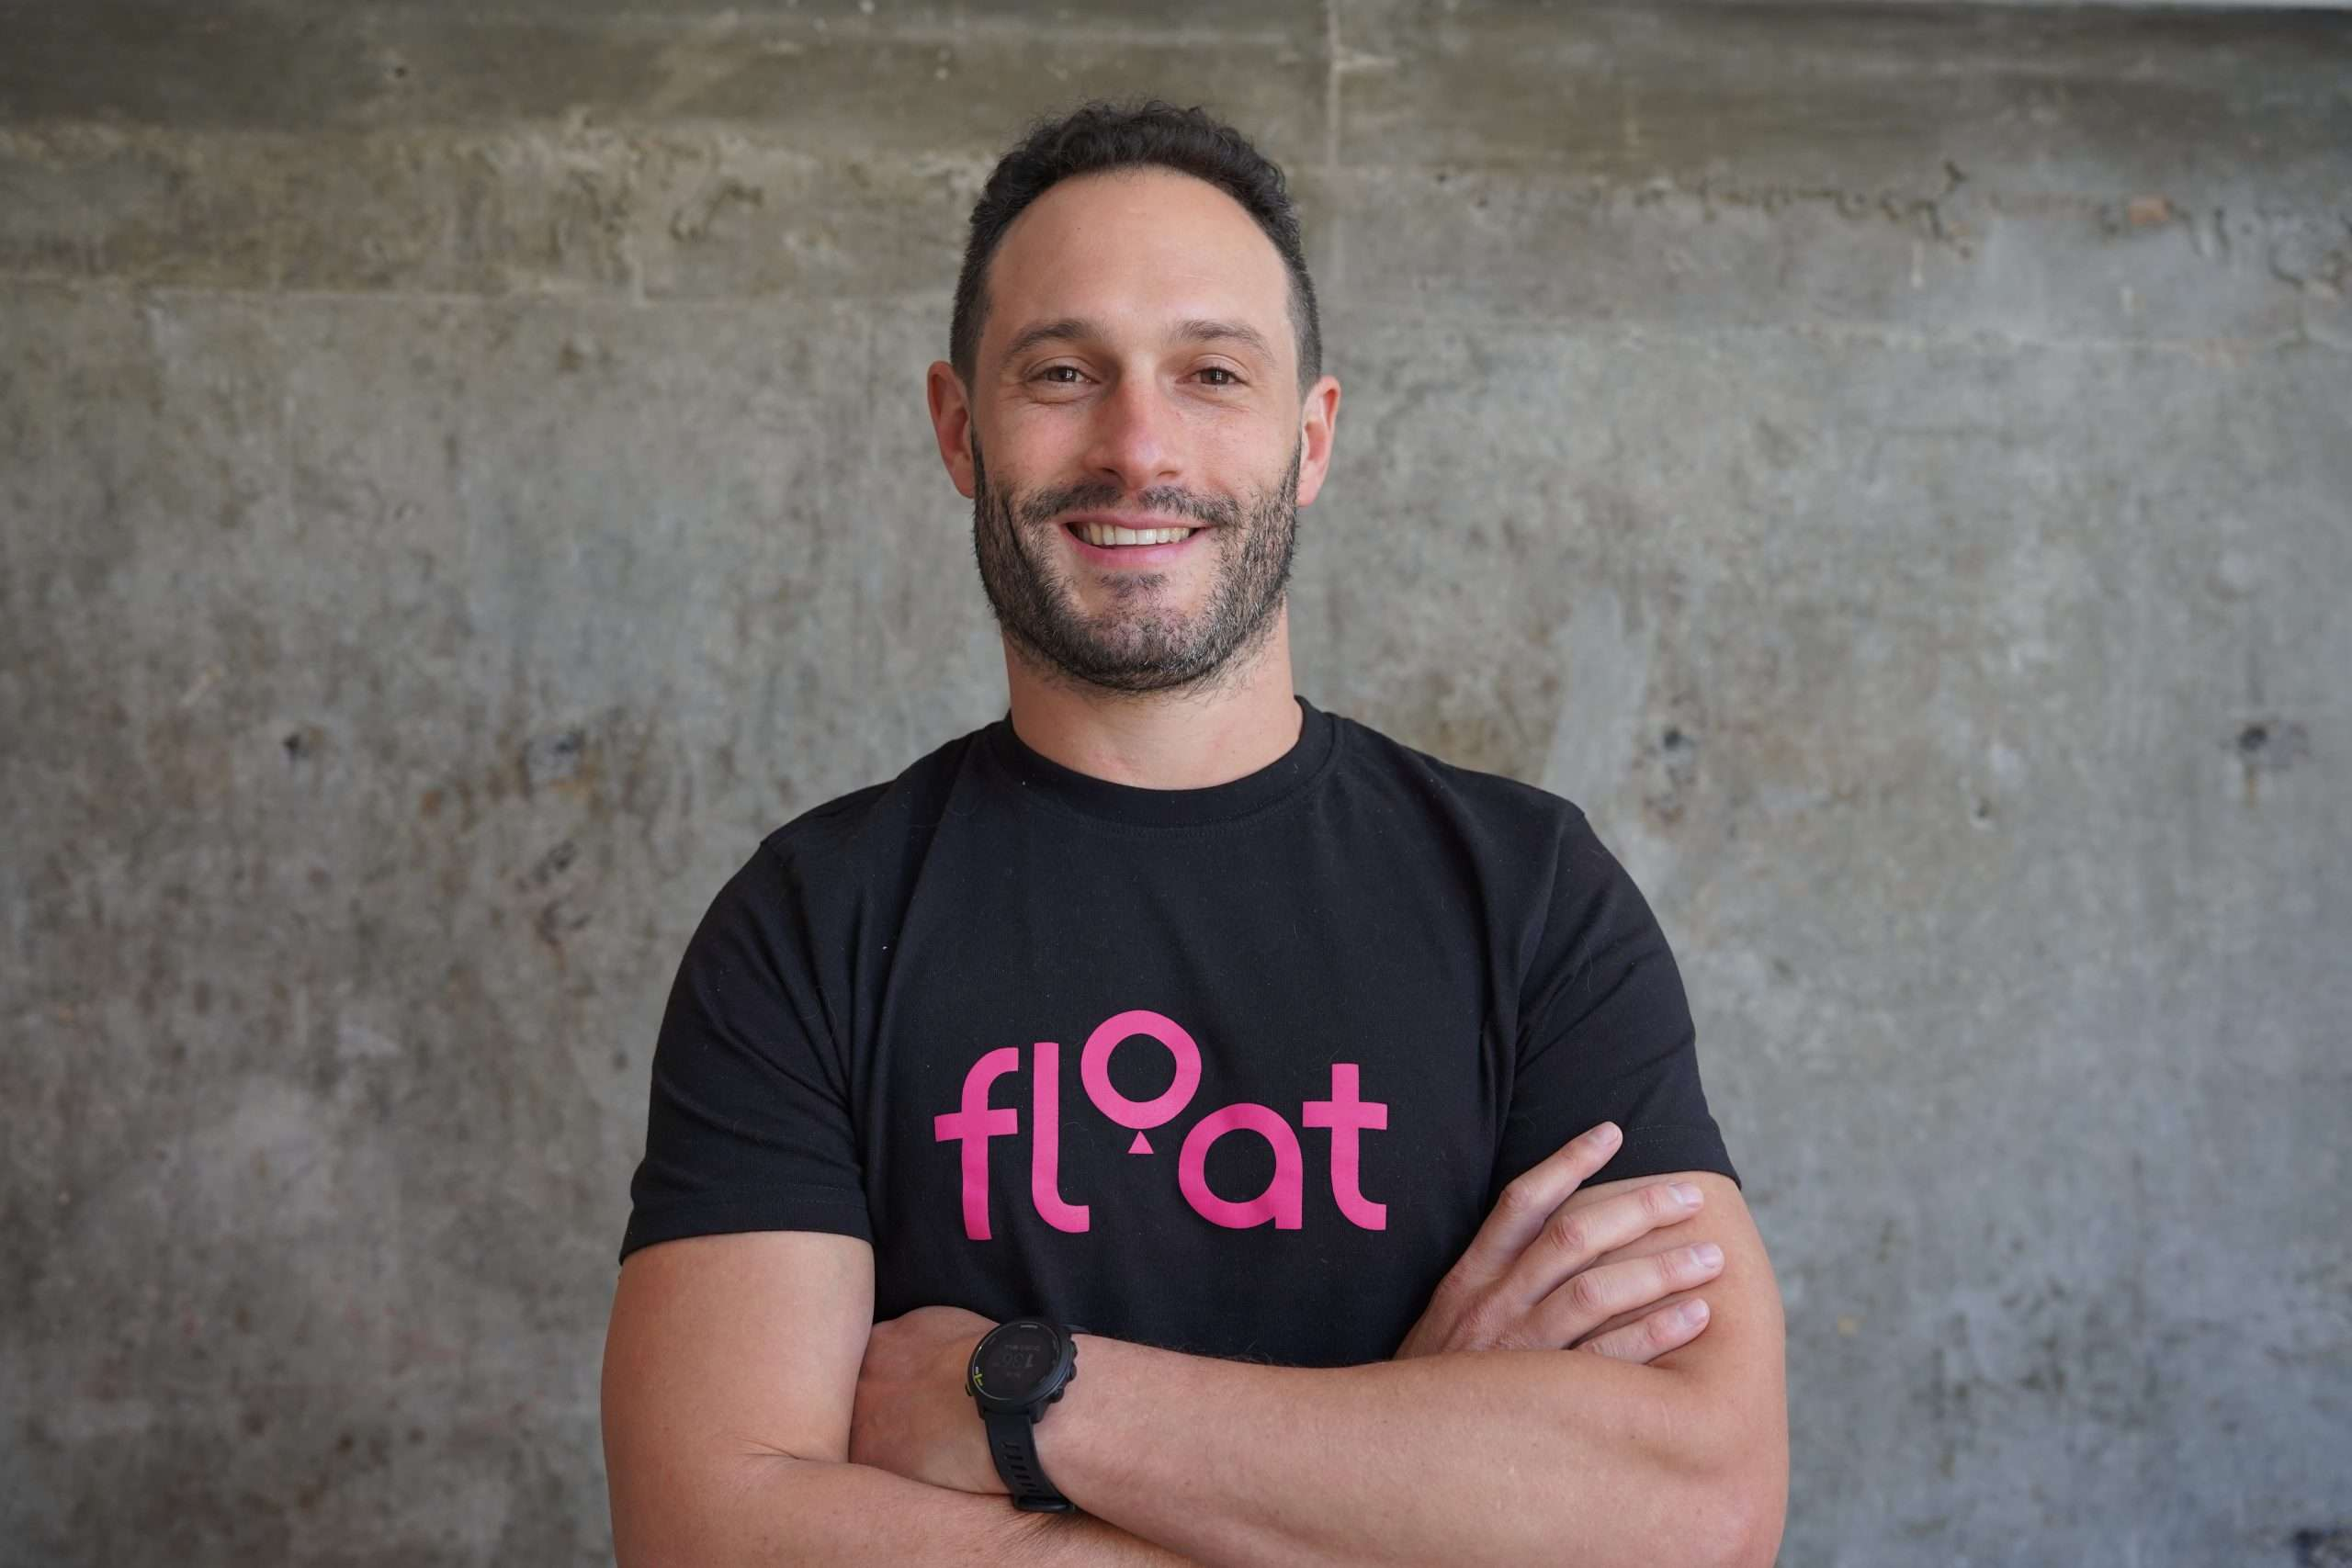
Float, a card-linked instalment platform, has reported its first month of trading data in the UK following its July 2026 launch. The company said 75% of its initial UK merchant cohort processed transactions on the day they went live, while the remaining 25% recorded transactions within 10 days.
The platform reported a UK average order value of £676 and said purchases made through Float have generated order-value increases of up to 133%. The company cautioned that the UK dataset remains smaller than its global dataset, limiting the extent to which the early figures can be generalized.
Float’s model differs from conventional buy-now-pay-later services because it uses a customer’s existing Visa or Mastercard credit limit rather than creating a new point-of-sale credit facility. The purchase can be divided into up to 12 monthly instalments, with Float stating that consumers pay no additional interest or fees to Float.
How Float’s Card-Linked Instalment Model Works
Traditional BNPL products generally involve a provider extending credit when a consumer chooses an instalment option at checkout. Float takes a different approach by connecting instalment payments to an existing credit card.
Under Float’s model, a customer uses available credit on an existing Visa or Mastercard card. The purchase is then divided into monthly instalments for up to 12 months.
The company says its platform is compatible with more than 55 million UK credit cards.
There is an important distinction between Float’s fees and the underlying credit-card agreement. Although Float describes the instalment option as carrying no interest or fees for the consumer, the cardholder remains subject to the terms of their existing credit card. Interest can therefore accrue if the customer’s monthly card statement is not cleared in full.
This means the economic cost to a consumer can depend on the underlying card agreement rather than solely on Float’s instalment terms.
Early UK Merchant Data Shows Initial Adoption
Float’s first-month figures provide an early indication of merchant uptake following its UK launch.
The company reported that 75% of its initial merchant group processed transactions on launch day. The remaining 25% processed transactions within 10 days.
The reported UK average order value was £676. Float also reported order-value increases of up to 133% for purchases made through its platform, although it emphasized that the UK sample is smaller than its global dataset.
The figures therefore describe early transaction activity rather than an established UK market trend. The release did not provide sufficient information to determine how the reported order-value uplift was calculated, the number of UK transactions involved or whether the increase applies consistently across merchant categories.
Which Retail Sectors Are Using Float?
Float’s initial UK merchant base includes businesses in several relatively high-value consumer categories.
Consumer electronics
Electronics is among the sectors where Float has early merchant adoption. Instalment payment structures can be relevant to purchases where customers face relatively large upfront costs.
Furniture and home
Furniture and home retailers are another early category. Float identified an unnamed furniture retailer that said the platform had become an important part of its payment offering and that customer adoption had been strong.
Sports and leisure
Sports and leisure businesses are also part of Float’s initial merchant mix.
The company said it is in advanced discussions with potential partners in automotive, beauty, luxury fashion and jewellery. These sectors generally include products with higher transaction values, which could be relevant to a card-linked model requiring sufficient existing credit availability.
Float’s Position in the UK Instalment Market
The UK instalment-payment market is undergoing regulatory change as authorities examine the treatment of BNPL and other forms of short-term consumer credit.
The Financial Conduct Authority (FCA) has been developing a regulatory framework for BNPL products, with regulation expected to affect the sector from 2026 onwards.
Float’s structure is relevant to that discussion because the platform does not describe itself as originating new credit at the point of purchase. Instead, it uses credit already available through a customer’s existing card.
That structural distinction could affect how the product is treated under the applicable regulatory framework. However, the supplied company material does not establish that Float has received a definitive regulatory determination confirming that its model falls outside particular FCA requirements.
The distinction between product structure and regulatory treatment is therefore important when assessing Float’s position in the market.
How Card-Linked Instalments Differ From BNPL
The main difference between the models concerns where the credit originates.
Conventional BNPL
A conventional BNPL provider typically establishes a new credit arrangement when a customer selects an instalment option. The provider may assess the consumer at checkout and then fund or facilitate the transaction under its own credit structure.
Card-linked instalments
Float instead links the transaction to an existing credit card. The customer is using credit that has already been provided through the card relationship.
This can reduce the need for a separate credit application at the point of sale. However, it also means the consumer’s available credit limit becomes an important constraint.
The model does not eliminate credit risk for the consumer. Instead, it shifts the relationship toward the existing card issuer and the cardholder’s contractual terms.
Existing Credit Limits Are Central to the Model
Float’s approach depends on consumers having sufficient available credit on their existing cards.
That creates a different set of commercial considerations from conventional BNPL. A customer may have access to a card but insufficient unused credit to finance a large purchase.
The model may therefore be particularly relevant to consumers making higher-value purchases where available credit is sufficient.
Float reported a UK average order value of £676, while saying its transactions can generate order-value increases of up to 133%. The company did not disclose enough information in the supplied release to establish how these results vary according to customers’ available credit, income, card type or merchant category.
Float’s International Merchant Footprint
Float said it operates across more than 2,200 stores globally.
Its named partners include Samsung, Trek, Reebok, The North Face and Diesel.
The company’s international footprint provides a broader operating base than its newly launched UK business. However, the first-month UK data should be considered separately from global performance because Float itself said the UK sample is smaller than its global dataset.
The company did not disclose revenue, the number of UK merchants or funding details in the announcement.
Regulatory and Consumer Considerations
The regulatory environment is one of the main issues surrounding instalment payments in the UK.
The FCA’s work on BNPL is focused partly on ensuring that consumers receive appropriate information and protections when using credit-based payment products. The distinction between new credit and existing credit can become significant when assessing different business models.
For Float, the key question is not simply whether the platform charges consumers an additional fee. The underlying credit-card relationship remains relevant because customers can incur interest under their existing card terms if they do not settle their statements in full.
This makes transparent communication particularly important when comparing a card-linked instalment product with a conventional interest-free BNPL product.
The supplied announcement does not report any formal FCA determination specifically covering Float’s model. Its regulatory position should therefore be distinguished from the company’s commercial description of the product.
Risks and Limitations of the Card-Linked Model
Several limitations are apparent from Float’s reported structure and early UK data.
Limited UK sample: The company acknowledges that its UK dataset is smaller than its global dataset. The first month’s results may therefore not represent longer-term UK performance.
Existing credit requirement: Customers need an eligible Visa or Mastercard credit card with sufficient available credit.
Underlying card costs: Float’s instalments may be described as carrying no interest or fees, but customers can still incur interest under their existing credit-card terms.
Regulatory uncertainty: The precise application of the UK’s developing BNPL regulatory framework to different instalment structures remains an important consideration.
Limited disclosure: Float did not disclose UK revenue, UK merchant numbers or funding information in the announcement.
Order-value interpretation: The reported increase of up to 133% does not by itself establish a causal relationship between Float and higher spending across the entire merchant base. The announcement does not provide enough methodological detail to assess the figure independently.
Future Outlook for Card-Linked Instalments in the UK
Float’s first month provides an early view of how a card-linked instalment model may be adopted by UK merchants.
The company’s next potential areas of expansion include automotive, beauty, luxury fashion and jewellery, where higher-value purchases could make instalment structures relevant.
At the same time, the UK’s changing consumer-credit regulatory environment will remain an important factor for payment providers. The distinction between originating new credit and using existing credit may influence how different products are structured and supervised.
For Float, the longer-term picture will depend on whether early merchant adoption develops into sustained transaction volumes, how consumers use the product over time and how regulators treat card-linked instalment models within the broader consumer-credit framework.
Conclusion
Float’s first UK trading figures show early merchant adoption following its July 2026 launch. The company reported that 75% of its initial merchant cohort processed transactions on launch day, while the remaining 25% did so within 10 days. Its reported UK average order value was £676, with order-value increases of up to 133% reported across Float transactions.
The company’s model differs from conventional BNPL because it operates through consumers’ existing Visa and Mastercard credit limits rather than issuing new point-of-sale credit. That structure may create a different regulatory and operational profile, but the supplied announcement does not establish a definitive FCA position on Float’s model.
With more than 2,200 stores globally and potential expansion into automotive, beauty, luxury fashion and jewellery, Float is seeking to extend the card-linked instalment model across additional retail categories. The UK business remains at an early stage, making longer-term merchant adoption, transaction volumes and regulatory developments important indicators of how the model develops.

