
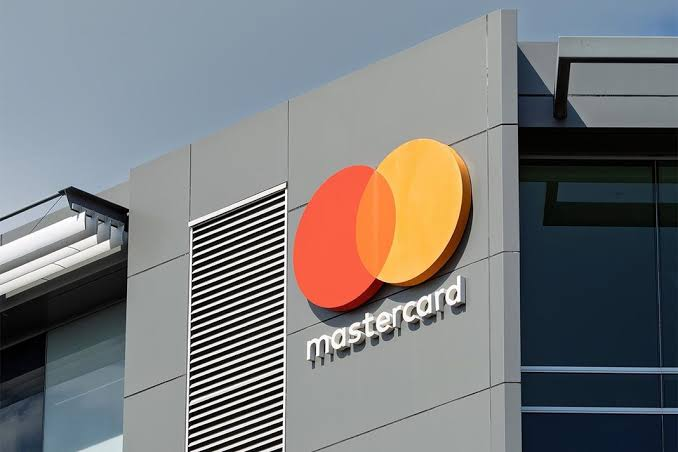
Mastercard is extending its First-Party Trust programme into Europe as payment networks, banks and merchants face growing pressure from disputes involving legitimate card transactions. The initiative is designed to help distinguish genuine third-party fraud from first-party misuse, often referred to as “friendly fraud”, when cardholders dispute purchases they authorised or received.
The expansion began in Eastern Europe, the Middle East and Africa in October 2026. Mastercard plans to make the programme available across Europe by July 2027. The service has operated in the United States, Canada, Latin America, the Caribbean and Asia Pacific since 2024.
The move gives merchants and card issuers additional tools to assess disputed transactions using fraud-risk signals and transaction evidence. It also strengthens Mastercard’s position in the competition between global payment networks to reduce chargeback losses and improve dispute management.
What Is Mastercard’s First-Party Trust Programme?
First-Party Trust is a Mastercard initiative intended to help payment participants identify the difference between transactions involving stolen payment credentials and disputes initiated by the cardholder who made the purchase.
Third-party fraud typically involves an unauthorised person using another individual’s payment details. First-party misuse, by contrast, can occur when a genuine cardholder disputes a valid transaction. This may happen deliberately or because the customer does not recognise a merchant name on a bank statement.
The distinction matters because the two cases require different responses. Treating every disputed payment as conventional fraud can expose merchants to avoidable chargeback costs, while rejecting legitimate claims can leave consumers without appropriate protection.
Mastercard’s programme aims to give issuers more information before they decide whether a disputed transaction should result in a chargeback.
How the First-Party Trust System Works
The programme uses two complementary mechanisms: transaction risk signals during payment authorisation and evidence sharing when a dispute is raised.
Fraud-risk signals during authorisation
Mastercard incorporates fraud-risk models into the authorisation process. These models generate signals that help identify transactions more consistent with third-party fraud and distinguish them from transactions carrying stronger indicators of trust.
The objective is to provide issuers with additional context about a payment before a dispute occurs. Better transaction-level information could help financial institutions assess subsequent claims more accurately.
However, risk signals are not definitive proof that a transaction is legitimate or fraudulent. Their value depends on the quality of the underlying data and how issuers incorporate them into their decision-making processes.
Evidence submitted during disputes
The second mechanism allows participating merchants to provide supporting information when a cardholder challenges a transaction.
Evidence may include:
- Delivery and fulfilment records.
- Authentication information.
- Relevant purchase history.
- Other transaction details that help establish whether a purchase was authorised and completed.
Issuers can use this information to assess the circumstances surrounding a disputed payment rather than relying solely on the cardholder’s claim or the merchant’s initial response.
Merchants that meet the programme’s evidence-sharing requirements receive chargeback protection for qualifying disputes. This creates a financial incentive to provide the information needed for a more detailed review.
The protection is conditional: it applies to eligible disputes and should not be interpreted as blanket immunity from chargebacks.
Why Chargebacks Are Becoming a Bigger Concern for Merchants
Chargebacks are an established part of card payments. They provide a mechanism for consumers to challenge transactions involving unauthorised activity, incorrect charges or goods and services that were not delivered as expected.
But the process can also create costs for businesses when customers dispute legitimate purchases.
According to the Merchant Risk Council figures cited in the source report, global chargeback volumes are forecast to reach 324 million transactions in 2028, compared with an estimated 261 million in 2025.
Projected global chargeback volume
Merchant Risk Council estimates cited in the source article.
0 million90 million180 million270 million360 million2025 estimate2028 forecast
The forecast represents an increase of approximately 24% over three years. It points to a growing operational challenge for merchants and financial institutions as digital commerce expands.
The figures are projections, not confirmed transaction totals. Actual volumes will depend on payment activity, fraud patterns, consumer behaviour and the effectiveness of dispute-prevention measures.
Why Small Businesses Could Benefit
Chargebacks can affect businesses of different sizes, but the financial impact may be more difficult for smaller merchants to absorb.
A high-volume retailer may have dedicated fraud teams, payment specialists and established procedures for responding to disputes. A small online business may have fewer resources and less capacity to investigate individual claims.
Chargeback-related expenses can include the disputed transaction amount, administrative fees, staff time and the potential loss of merchandise or services already provided.
Mastercard’s inclusion of small businesses in the programme’s scope could therefore be significant. Access to structured evidence-sharing and qualifying chargeback protection may help smaller merchants manage disputes without building extensive internal fraud operations.
The practical benefit will depend on how easily acquirers and payment service providers make the programme available to smaller businesses.
European Payments Regulation Adds Another Dimension
The expansion also takes place against a changing European regulatory environment.
The EU’s Payment Services Directive framework establishes requirements for payment service providers, including rules concerning unauthorised transactions, security and consumer protection. The EU’s proposed successor framework, PSD3, and the accompanying Payment Services Regulation are intended to update parts of that system.
Strong Customer Authentication (SCA), introduced under PSD2, is particularly relevant to online payments. It requires additional authentication for many electronic transactions, subject to exemptions and specific conditions.
Authentication records can help merchants demonstrate that a payment passed through a recognised verification process. Combined with delivery information and purchase history, those records may provide issuers with a stronger evidential basis when reviewing disputes.
However, authentication does not automatically establish that a customer received the goods or services, nor does it resolve every type of chargeback claim. Merchants and issuers must still assess the circumstances and applicable payment rules.
First-Party Trust should therefore be viewed as a potential support for dispute assessment, not a replacement for existing legal obligations or consumer protections.
Mastercard and Visa Compete in Dispute Management
Mastercard’s expansion also reflects competition between the two largest global card networks in payment security and dispute infrastructure.
Visa operates dispute-management services including Visa Resolve Online and its Compelling Evidence 3.0 framework, introduced in 2023. The latter provides a structured approach to presenting transaction evidence in certain card-not-present disputes.
Mastercard’s First-Party Trust programme addresses a related challenge by combining risk signals with merchant-provided evidence.
The systems are not identical, and their eligibility requirements and operating procedures differ. Nevertheless, the European expansion gives financial institutions managing both Mastercard and Visa portfolios additional network-specific tools for handling disputed transactions.
For banks and payment processors, the availability of more structured evidence workflows could support operational consistency. It will not necessarily eliminate the need to maintain separate processes for each card network.
What Could Limit the Programme’s Impact?
The programme’s effectiveness will depend on implementation across the payments ecosystem.
Acquirer participation: Merchants generally access card-network services through acquiring banks and payment processors. If those institutions do not integrate First-Party Trust into their systems, merchant adoption may remain limited.
Evidence quality: Incomplete, inconsistent or poorly organised records can weaken dispute assessments. Merchants will need reliable processes for retaining authentication, delivery and transaction information.
Integration costs: Smaller merchants may benefit from chargeback protection but could face technical or administrative barriers if participation requires changes to their payment systems.
Consumer protection: Reducing unjustified disputes must not make it harder for customers to challenge genuinely unauthorised or incorrectly processed transactions. Issuers will still need to distinguish legitimate consumer claims from first-party misuse.
Regional differences: Payment practices, regulatory requirements and merchant infrastructure vary across European markets, the Middle East and Africa. A programme that works effectively in one market may require adjustments in another.
What to Watch Ahead of the July 2027 Rollout
Mastercard’s next challenge is moving the programme from regional expansion to broad operational adoption.
The initial rollout in Eastern Europe, the Middle East and Africa began in October 2026, while full European availability is scheduled for July 2027. That timetable gives acquirers and payment service providers time to assess integration requirements and prepare merchant-facing processes.
Several indicators will help determine whether the initiative gains traction:
- The number of acquirers and payment processors integrating the programme.
- Merchant participation, particularly among small and medium-sized businesses.
- Changes in chargeback outcomes for qualifying disputes.
- The quality and speed of evidence submitted to issuers.
- Whether the programme reduces avoidable disputes without weakening consumer protections.
Mastercard has not provided a specific adoption target or quantified reduction in chargebacks in the supplied announcement. Its commercial impact will therefore need to be assessed through implementation data and dispute outcomes after wider deployment.
Conclusion
Mastercard’s European expansion of First-Party Trust addresses a persistent problem in digital payments: distinguishing genuine fraud from disputes involving legitimate cardholder transactions.
By combining authorisation-stage risk signals with evidence submitted by merchants, the programme aims to give issuers more information when evaluating chargeback claims. Its inclusion of smaller businesses could also broaden access to dispute-management tools that have traditionally been easier for larger merchants to support.
The July 2027 availability target will be an important milestone. Ultimately, the programme’s value will depend less on its technical design than on acquirer adoption, evidence quality and whether it can reduce unnecessary chargebacks while preserving consumers’ ability to challenge legitimate problems.

