


Introduction
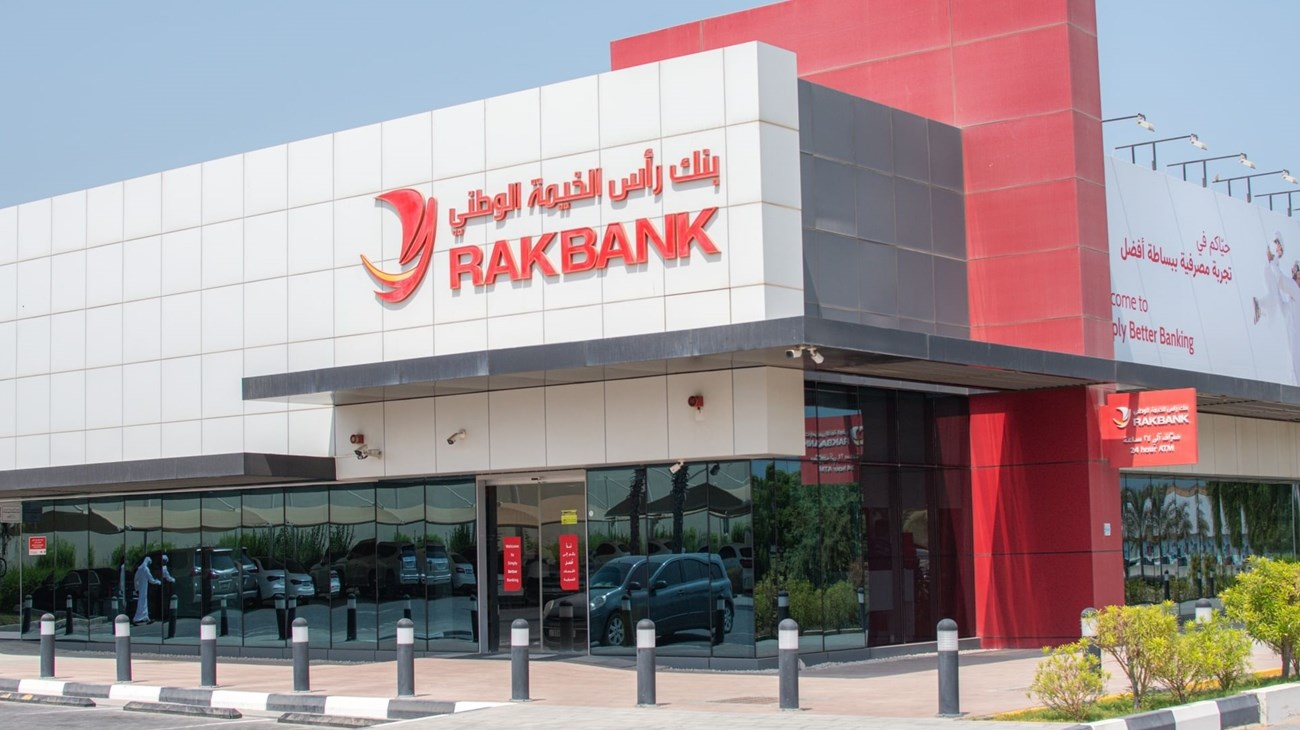
RAKBANK, Ras Al Khaimah National Bank, has reported record first-half profitability for 2026, attributing the result to a sector-leading net interest margin, a strengthening low-cost deposit base and a one-off AED 473 million gain from the sale of its merchant payment acceptance business. The bank’s return on equity rose to 25.2%, up from 22.1% a year earlier, positioning it among the higher-returning listed lenders in the UAE banking system.
The results carry relevance beyond RAKBANK itself. As UAE banks continue to benefit from elevated benchmark rates tied to the dirham’s dollar peg, RAKBANK’s performance offers a data point for assessing how sustainably regional lenders are pricing loans and managing funding costs as global credit conditions become more selective. The bank’s decision to divest merchant acquiring infrastructure also reflects a broader pattern among Gulf and international banks reassessing which payment functions belong on balance sheet versus with specialist processors, a question relevant to investors, competing regional banks and payments industry participants.
What RAKBANK Reported
RAKBANK did not disclose an absolute net profit figure in its release, limiting direct year-on-year comparison. The bank instead highlighted return on equity of 25.2%, up from 22.1%, and return on assets of 3.2%, up from 3.1%. The net interest margin stood at 3.9%, alongside a current and savings account (CASA) ratio of 64.3%, which the bank cited as evidence of a structurally low-cost funding base.
Asset quality metrics also improved. The non-performing loan ratio fell to 1.8% from 2.1% on an annualised basis, with Stage 3 provision coverage reaching 85.9%, a level the bank described as among the highest in its peer group. The capital adequacy ratio stood at 19.3%, above UAE Central Bank minimum requirements, while the eligible liquid assets ratio (ELAR) was 13.0%.
How the Result Was Driven
Two separate factors underpin the headline figures: underlying operating performance and a one-off disposal gain. The net interest margin of 3.9%, sustained through the first half of 2026, reflects disciplined loan pricing combined with the low-cost CASA-heavy deposit mix, in a rate environment where the UAE’s dollar peg has kept benchmark rates elevated industry-wide.
Separately, RAKBANK generated AED 473 million from the sale of its merchant payment acceptance business. The bank did not name the acquirer or disclose the total transaction value, leaving the strategic rationale beyond the immediate profit contribution unclear. The move mirrors a wider trend of banks in the Gulf and internationally separating payment acceptance infrastructure from core balance sheets, either to realise capital value or to partner with specialist payment processors.
Key Factors Influencing the Results
The UAE’s dollar-pegged monetary policy is a structural factor supporting margins across the domestic banking sector, with elevated benchmark rates benefiting lenders broadly rather than RAKBANK specifically. RAKBANK’s funding structure, reflected in its 64.3% CASA ratio, is a bank-specific factor reducing its sensitivity to rate movements relative to peers more reliant on term deposits.
Regional economic conditions in Ras Al Khaimah also factor into the results. RAKBANK operates as the dominant commercial bank in the emirate and is positioned to benefit from its ongoing industrialisation drive, alongside broader UAE Central Bank data showing continued aggregate bank credit growth this year, supported by government infrastructure spending and business formation in the northern emirates.
Costs, Impact and Business Implications
The AED 473 million disposal gain provides a material but non-recurring contribution to H1 2026 profitability, meaning the underlying, recurring earnings power of the bank cannot be fully assessed until consolidated accounts excluding the one-off item are published. For analysts and investors, this distinction matters for forward earnings projections and valuation.
RAKBANK’s business spans personal banking, business banking with a stated SME focus, and wholesale and institutional banking, alongside minority stakes in Skippr, a school-payments platform, Protego, a digital insurance product, and RAK Insurance, a licensed underwriter. The bank has also positioned itself as an early entrant in retail cryptocurrency trading in the UAE, a market now regulated under the Virtual Assets Regulatory Authority (VARA) framework, an area with distinct regulatory and risk considerations separate from core banking operations.
Risks and Limitations
The absence of a disclosed net profit figure and the undisclosed acquirer and transaction value for the merchant business sale limit the transparency of RAKBANK’s reporting in this release, constraining independent verification of the results. The one-off nature of the AED 473 million gain means headline profitability and return-on-equity figures for H1 2026 are not directly comparable to periods without similar disposals, and should not be extrapolated as a sustainable earnings run rate.
Improved asset quality metrics, including the lower non-performing loan ratio and higher provision coverage, are self-reported figures pending confirmation in full consolidated accounts. The bank’s expansion into retail crypto trading also introduces exposure to a nascent regulatory framework under VARA, with risks that differ from those of traditional lending and deposit-taking activities.
Future Outlook
The next disclosures likely to clarify RAKBANK’s underlying performance are the identity of the merchant business acquirer and the publication of full consolidated accounts, which would isolate the one-off disposal gain from recurring operating profit. Continued UAE Central Bank data on aggregate credit growth and the trajectory of benchmark rates tied to the dollar peg will remain relevant to whether RAKBANK and peer UAE banks can sustain current net interest margins through the remainder of 2026. No specific timeline for these disclosures has been confirmed by the bank.
Conclusion
RAKBANK’s record H1 2026 results reflect a combination of sustained net interest margin strength, a low-cost deposit base and a one-off gain from the sale of its merchant payment acceptance business. Improved asset quality and capital metrics support the underlying picture, though the absence of a disclosed net profit figure and details of the merchant business transaction limit full transparency. Clarity on recurring earnings will depend on future disclosures, including consolidated accounts isolating the one-off disposal gain.

