


Introduction
Tanzania has built one of East Africa’s most widely used mobile-money markets, with digital financial transfers embedded across urban centres, rural communities and Zanzibar. By the end of last year, the country recorded approximately 75.8 million active mobile-money subscriptions, according to the Bank of Tanzania, a figure exceeding the adult population due to multi-provider usage. The more consequential question facing the Tanzania fintech ecosystem in 2026 is not whether citizens can access digital financial services, but what functionality that access now supports.
The shift matters beyond Tanzania’s borders. As mobile-money markets across Sub-Saharan Africa reach saturation, attention among regulators, investors and payment providers is moving toward interoperability, real-time settlement infrastructure and the qualitative use of financial services, questions with direct relevance for Tanzania’s banks, fintech companies, small and medium enterprises, and international investors assessing East African digital infrastructure.
What the Tanzania Fintech Ecosystem Comprises
Tanzania’s digital-finance sector is anchored by mobile-wallet providers including M-Pesa, Mixx by Yas, Airtel Money, HaloPesa and AzamPesa, alongside banks such as CRDB Bank, NMB Bank and National Bank of Commerce. Beyond consumer transfers, a second layer of the ecosystem, comprising companies such as AzamPay, Selcom and ClickPesa, provides payment gateways, merchant collection tools, disbursement services and application programming interfaces enabling businesses to accept payments across wallets, cards and bank accounts.
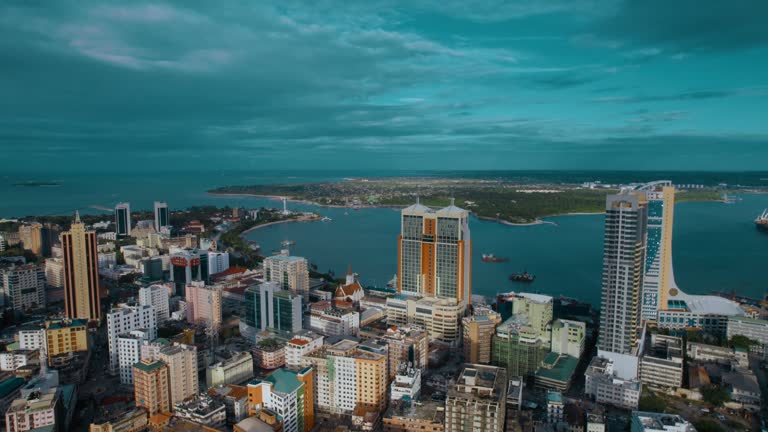
According to the IMF, Tanzania’s economy is projected to grow by 5.9% this year, with inflation expected to remain around 4%. Nominal GDP is forecast to approach $95 billion, equivalent to approximately $1,360 per capita. Agriculture, mining, tourism, construction, manufacturing and telecommunications remain the dominant economic sectors, with Dar es Salaam functioning as the country’s commercial and financial centre.
How Payment Integration Works in Practice
The Tanzania Instant Payment System (TIPS), developed and operated by the Bank of Tanzania, connects banks and non-bank financial providers through shared real-time payment infrastructure, allowing funds to move instantly between participating institutions rather than remaining confined within separate networks. TIPS was developed domestically by Tanzanian engineers rather than procured from an overseas vendor, giving the central bank direct control over a core piece of national financial infrastructure.
This interoperability layer addresses a structural limitation of mobile-money growth: a market with multiple wallet providers and banks can remain fragmented if customers face additional costs or steps when transferring funds across networks. TIPS is designed to reduce those frictions by standardising settlement across institutions.
Key Factors Shaping the Ecosystem’s Development
Financial inclusion data indicates the scale of Tanzania’s digital-finance base. The 2023 FinScope survey found that 89% of adults could access formal financial services, with 76% actively using them, up from 65% formal usage in 2017. However, usage patterns skew toward basic transfer and withdrawal functions rather than formal savings, insurance, pensions or productive credit, indicating that access has outpaced deeper financial engagement.
The National Financial Inclusion Framework 2023–2028 is a second influencing factor, prioritising underserved women, young people, rural communities and micro, small and medium-sized enterprises, alongside consumer protection, financial education and responsible digital-service use. Regulatory capacity is a third factor: the Bank of Tanzania’s fintech regulatory sandbox has run a second cohort, announced in September of the prior year, and a third cohort in June of this year, indicating that structured experimentation with new financial products is becoming a recurring regulatory function rather than an isolated initiative.
Costs, Impact and Implications
For businesses, particularly SMEs unable to build proprietary financial infrastructure, third-party payment gateways and disbursement APIs lower the operational cost of accepting digital payments across multiple channels. For the broader economy, real-time interoperable settlement through TIPS reduces transaction friction between institutions, a factor with implications for merchant cash flow and the cost of doing business digitally.
At the household level, the gap between formal access (89%) and active usage of savings, credit and insurance products suggests that the economic benefit of financial inclusion remains partially unrealised. Closing that gap has direct implications for household resilience and long-term economic security, a policy priority reflected in the National Financial Inclusion Framework.
Risks and Limitations
Tanzania’s fintech ecosystem remains smaller in scale than those of Nigeria, South Africa, Egypt and Kenya, Africa’s largest fintech markets, which may limit investment flow and cross-border product expansion relative to regional peers. The central bank has also increased scrutiny of unauthorised digital lenders and unregistered providers, reflecting ongoing risk as digital credit expands through mobile applications outside traditional institutional channels.
The gap between financial access and active usage of savings, insurance and credit products represents a further limitation: broad account ownership does not, on its own, indicate improved household financial security. Additionally, while the regulatory sandbox demonstrates growing institutional capacity, its outcomes and long-term effectiveness in balancing innovation with consumer protection have not yet been independently assessed over multiple cycles.
Future Outlook
The trajectory described suggests Tanzania’s digital-finance priorities are shifting from expanding mobile-money access, a largely achieved goal, toward improving interoperability, product depth and consumer protection. With real-time payment infrastructure in TIPS, an active regulatory sandbox, and a formal inclusion framework running through 2028, structural foundations are in place. Whether these translate into measurable gains in savings, credit access and business growth will depend on execution over the coming years rather than infrastructure alone. No specific timeline for full interoperability or additional TIPS expansion has been confirmed by the Bank of Tanzania.
Conclusion
Tanzania’s fintech ecosystem has moved beyond the initial achievement of mobile-money access toward a more integrated model connecting wallets, banks, merchants and government services through shared digital infrastructure. Real-time payment systems, a maturing regulatory sandbox and a formal inclusion framework mark measurable institutional progress. The unresolved question is whether these structures translate into deeper financial usage, savings, credit and insurance, rather than continued growth limited to basic transfers.

