


Introduction
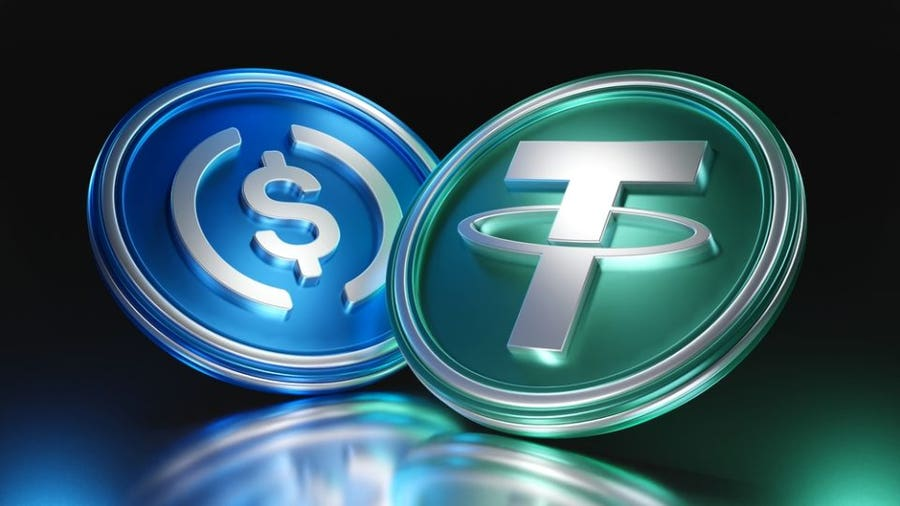
Stablecoins are increasingly moving beyond cryptocurrency trading and into everyday financial activity, including payments, payroll and corporate treasury operations. Data published by Mercuryo in August shows that stablecoins represented 60 per cent of crypto purchase value through its on-ramp during the first half of 2026, compared with 43 per cent in the second half of 2025.
The company also reported a significant increase in stablecoin use on the cash-out side. USD Coin (USDC) and Tether (USDt) accounted for 57 per cent of accepted off-ramp transactions in the first half of 2026, compared with 25 per cent a year earlier. Mercuryo linked a substantial portion of this activity to payroll, particularly among internationally distributed workers.
The figures point to a broader question for financial institutions and businesses: whether stablecoins are becoming another practical payment and treasury rail rather than remaining primarily a cryptocurrency product.
What Are Stablecoins and Why Are They Being Used for Payments?
Stablecoins are digital tokens designed to maintain a relatively stable value against an underlying reference asset, commonly a fiat currency such as the US dollar.
Unlike many cryptoassets whose prices can fluctuate substantially, dollar-denominated stablecoins are intended to provide a digital representation of dollar value that can be transferred over blockchain networks.
This characteristic is increasingly relevant to businesses and individuals involved in cross-border transactions. Stablecoins can move continuously over blockchain infrastructure rather than being restricted to traditional banking settlement schedules.
Mercuryo’s data indicates that stablecoins accounted for a growing share of crypto purchase activity during the first half of 2026. The company also said transaction frequency and average purchase sizes increased, suggesting that the change was not limited to a single group of speculative buyers.
Stablecoins and cross-border financial activity
For internationally active individuals and businesses, the attraction is partly connected to the ability to move dollar-denominated value across borders.
New users are also increasingly selecting stablecoins as their first crypto purchase, according to Mercuryo. The company attributes this partly to demand for dollar-denominated value, access to global markets and alternative ways to move money internationally.
However, the use of blockchain networks does not eliminate the need for conventional financial infrastructure. Conversion between stablecoins and local currencies, compliance procedures and access to the banking system can still require regulated financial institutions and payment providers.
How Stablecoin-Based Neobanks Differ From Conventional Neobanks
The emergence of stablecoin-enabled financial products is another development in digital banking.
A conventional neobank generally provides services such as accounts, cards and transfers through digital channels, with cryptocurrency services potentially offered alongside those products.
A stablecoin-focused financial product can instead use blockchain networks as part of its underlying payment infrastructure, with stablecoins providing the digital value transferred through those networks.
The distinction is important because blockchain infrastructure can provide a settlement layer operating continuously, while stablecoins provide a digital unit of value that can be transferred across that infrastructure.
The role of connectivity
For users, the objective is increasingly to make the underlying infrastructure invisible.
A customer or business may not need to know which blockchain network processes a transaction if the payment provider can manage the technical and compliance requirements behind the transaction.
This could be particularly relevant for companies operating across multiple jurisdictions, where traditional international transfers may involve several financial institutions, settlement periods and reconciliation processes.
The practical value therefore depends not simply on blockchain technology, but on how effectively stablecoin infrastructure connects with local banking and payment systems.
Stablecoins in Corporate Treasury Management
Corporate treasury is one of the areas where stablecoins could have a direct operational application.
Businesses with subsidiaries in several countries often need to move working capital between jurisdictions. Traditional transfers can involve multiple bank accounts, correspondent banking relationships, settlement windows and reconciliation procedures.
Stablecoins provide another potential mechanism for transferring dollar-denominated value between entities, after which the funds can be converted into local currency when required.
Moving liquidity between subsidiaries
Consider a multinational business with operating entities in Europe, the United States and emerging markets.
Instead of maintaining large, separate pools of liquidity in every jurisdiction, a treasury operation could use stablecoins to transfer value between entities and convert the funds when local currency is required.
The source material does not identify a specific company currently using this model, so the example should be viewed as an illustration of the potential treasury structure rather than evidence of a particular corporate implementation.
For treasury departments, the relevant considerations extend beyond transfer speed. Liquidity management, foreign-exchange exposure, accounting treatment, compliance, custody and local regulatory requirements remain important parts of the operating model.
Stablecoin Payroll and the Rise of Global Workforces
Payroll is another area where stablecoin adoption is becoming more visible.
Mercuryo’s off-ramp data shows USDC and USDt accounting for 57 per cent of accepted off-ramp transactions in the first half of 2026, compared with 25 per cent a year earlier. The company associates much of this activity with payroll.
The strongest demand, according to Mercuryo, is coming from globally distributed workers, including contractors, freelancers and digital professionals working for companies located in other countries.
For these workers, receiving international compensation can involve local banking infrastructure, foreign-exchange conversion and settlement schedules.
A stablecoin-based payroll arrangement can allow an employer to transfer dollar-denominated value over blockchain infrastructure, with the worker converting the funds into local currency when required.
Stablecoin payroll does not eliminate banks
The growth of stablecoin payroll does not necessarily mean banks and remittance providers disappear from the payment chain.
Banks can continue to provide local settlement, currency conversion, compliance services and access to traditional financial accounts.
Remittance companies can also remain relevant where customers require cash-out services, local-currency delivery or other regulated payment services.
The more likely structural change is that blockchain networks may increasingly handle part of the movement of value between financial systems, while regulated institutions continue to provide the connections into those systems.
What Weekend Stablecoin Transactions Say About Banking Hours
One of the more notable findings in Mercuryo’s data concerns activity outside traditional banking hours.
The company reported that weekend stablecoin cash-out volumes were approximately 86 per cent of weekday levels.
That pattern highlights a fundamental difference between blockchain-based settlement and conventional banking schedules.
Permissionless blockchain networks can operate continuously, including Saturdays and Sundays. Businesses and individuals therefore have the ability to initiate transactions outside traditional banking windows, subject to the operating hours and requirements of the payment provider or off-ramp involved.
For internationally distributed businesses, this distinction can be operationally significant.
A company whose workers, suppliers or subsidiaries operate in multiple time zones does not necessarily follow a Monday-to-Friday financial timetable. Continuous blockchain settlement can therefore provide an additional payment rail for transactions occurring outside conventional banking hours.
Regulatory Frameworks Will Shape Stablecoin Adoption
The expansion of stablecoin payments also creates regulatory questions.
The source highlights the GENIUS Act in the United States as establishing a legal framework covering areas including stablecoin issuance, reserve backing and consumer protection. It also notes that the United Kingdom is developing its own regulatory regime.
For businesses, regulatory clarity matters because stablecoin payments can involve several different participants.
A single cross-border transaction may include a stablecoin issuer, blockchain network, payment provider, financial institution and local-currency conversion service.
Each part of that chain can create different compliance and responsibility requirements.
Issuance, reserves, redemption and custody
A mature stablecoin payment ecosystem requires clarity around several areas:
- Stablecoin issuance
- Reserve arrangements
- Redemption
- Custody
- Consumer protection
- Compliance responsibilities
- Cross-border transactions
- Conversion into local currencies
Regulators face the challenge of developing safeguards while dealing with payment infrastructure that operates across national borders.
For companies considering stablecoin-based financial products, uncertainty around these requirements can increase operational and compliance costs.
Regulatory Fragmentation Could Slow Adoption
One of the biggest risks to stablecoin adoption is regulatory fragmentation.
Blockchain networks operate internationally, while financial regulation remains largely jurisdiction-specific. A stablecoin product serving customers in several countries may therefore have to operate under different rules concerning issuance, custody, payments, consumer protection and financial crime controls.
This creates a potential barrier for businesses seeking to build stablecoin payments into their existing operations.
A fragmented regulatory environment can make product development more complicated and may discourage companies from committing significant resources to infrastructure that could face different requirements from one market to another.
Greater regulatory alignment could make it easier for businesses and financial institutions to determine how stablecoins can legally and operationally fit into existing payment systems.
Risks and Limitations of Stablecoin Payments
The growth of stablecoins should not be interpreted as evidence that they are replacing conventional financial infrastructure.
Several limitations remain.
Regulatory risk
Rules governing stablecoin issuance and use continue to develop across jurisdictions. Companies operating internationally may face different requirements in each market.
Conversion risk and infrastructure dependence
Users often need to convert stablecoins into local currencies. That requires an off-ramp, payment provider, exchange or financial institution capable of completing the transaction.
Compliance requirements
Stablecoin transactions can still involve identity verification, anti-money-laundering controls and other regulatory obligations. Blockchain settlement does not automatically remove these requirements.
Operational complexity
Businesses adopting stablecoins must consider custody, wallet management, accounting, reconciliation, treasury controls and integration with existing financial systems.
Network and service-provider considerations
Although blockchain networks can operate continuously, the complete payment journey may still depend on regulated intermediaries, liquidity providers and local banking infrastructure.
The practical benefit of stablecoins therefore depends on the entire financial stack rather than on blockchain settlement alone.
The Implications for Banks and Remittance Companies
The expansion of stablecoin payments creates a strategic question for banks and remittance providers.
Rather than simply removing intermediaries, stablecoins can change where different parts of the payment process occur.
Traditional financial institutions may continue to provide:
- Local-currency settlement
- Foreign-exchange services
- Customer accounts
- Compliance infrastructure
- Custody
- Payment connectivity
- Access to regulated financial systems
Blockchain networks can potentially provide another layer for moving digital value between markets.
This means competition and cooperation may develop simultaneously. Financial institutions that connect traditional accounts and payment services with digital-asset infrastructure could remain important even as the underlying payment rails evolve.
The Future of Stablecoins as Everyday Money
The evidence presented by Mercuryo suggests that stablecoins are increasingly being used in practical financial contexts, including crypto purchases, cash-outs and payroll-related transactions.
The significance of the trend lies less in stablecoins as a new type of speculative asset and more in their potential role as a digital settlement mechanism.
Corporate treasury is one area where the model could develop further, particularly for companies managing liquidity across several jurisdictions. Payroll represents another practical use case because international workers frequently encounter differences between where they work, where their employer is located and where they maintain their bank accounts.
However, adoption will depend heavily on regulation, interoperability with existing financial systems, local-currency conversion and the ability of businesses to manage compliance and operational risks.
The next phase of stablecoin development is therefore likely to be shaped not only by blockchain technology but also by how effectively digital payment networks connect with regulated financial infrastructure.
Conclusion
Stablecoins are increasingly being tested as payment and treasury infrastructure rather than simply as crypto trading instruments. Mercuryo reported that stablecoins accounted for 60 per cent of crypto purchase value through its on-ramp in the first half of 2026, up from 43 per cent in the second half of 2025.
At the same time, USDC and USDt represented 57 per cent of accepted off-ramp transactions, compared with 25 per cent a year earlier, with the company linking much of that activity to payroll.
The figures point to growing demand for digital dollar-denominated value that can move continuously across borders. Yet stablecoins remain dependent on the wider financial system for regulation, compliance, local settlement and currency conversion.
For banks, remittance companies and businesses, the important development may therefore be the emergence of a hybrid financial system in which blockchain-based settlement and traditional banking infrastructure operate alongside one another.

