


Introduction
Türkiye’s fintech ecosystem has moved beyond its early development phase, according to industry assessments, evolving into a sector capable of producing internationally valuable financial technology businesses despite persistent macroeconomic volatility. The country combines a large domestic consumer base, an established technology hub in Istanbul, and central bank-led payment infrastructure that has reshaped how money moves between institutions and individuals.
This development matters globally because Türkiye demonstrates how financial technology can expand even amid high inflation and currency depreciation. The International Monetary Fund’s July 2026 update projects real GDP growth of 2.9%, while consumer price inflation is expected to average around 28.6% for the year. Those conditions have created demand for more efficient financial tools among consumers, merchants, and businesses engaged in cross-border trade.
The Turkey fintech ecosystem now affects a broad range of stakeholders, including domestic banks adapting to digital competition, international investors evaluating Turkish payment and investment platforms, and businesses in neighbouring regions that could benefit from infrastructure originally built for the Turkish market.
What Defines the Turkey Fintech Ecosystem
According to The State of Turkish Fintech Ecosystem 2025, published by the Investment and Finance Office of the Presidency of the Republic of Türkiye and Startups.watch, the sector spans payments, banking technology, digital banking, insurance, investment technology, blockchain, and financial software. Türkiye’s population is expected to reach approximately 86.2 million in 2026, providing fintech companies with a substantial domestic base before considering international expansion.
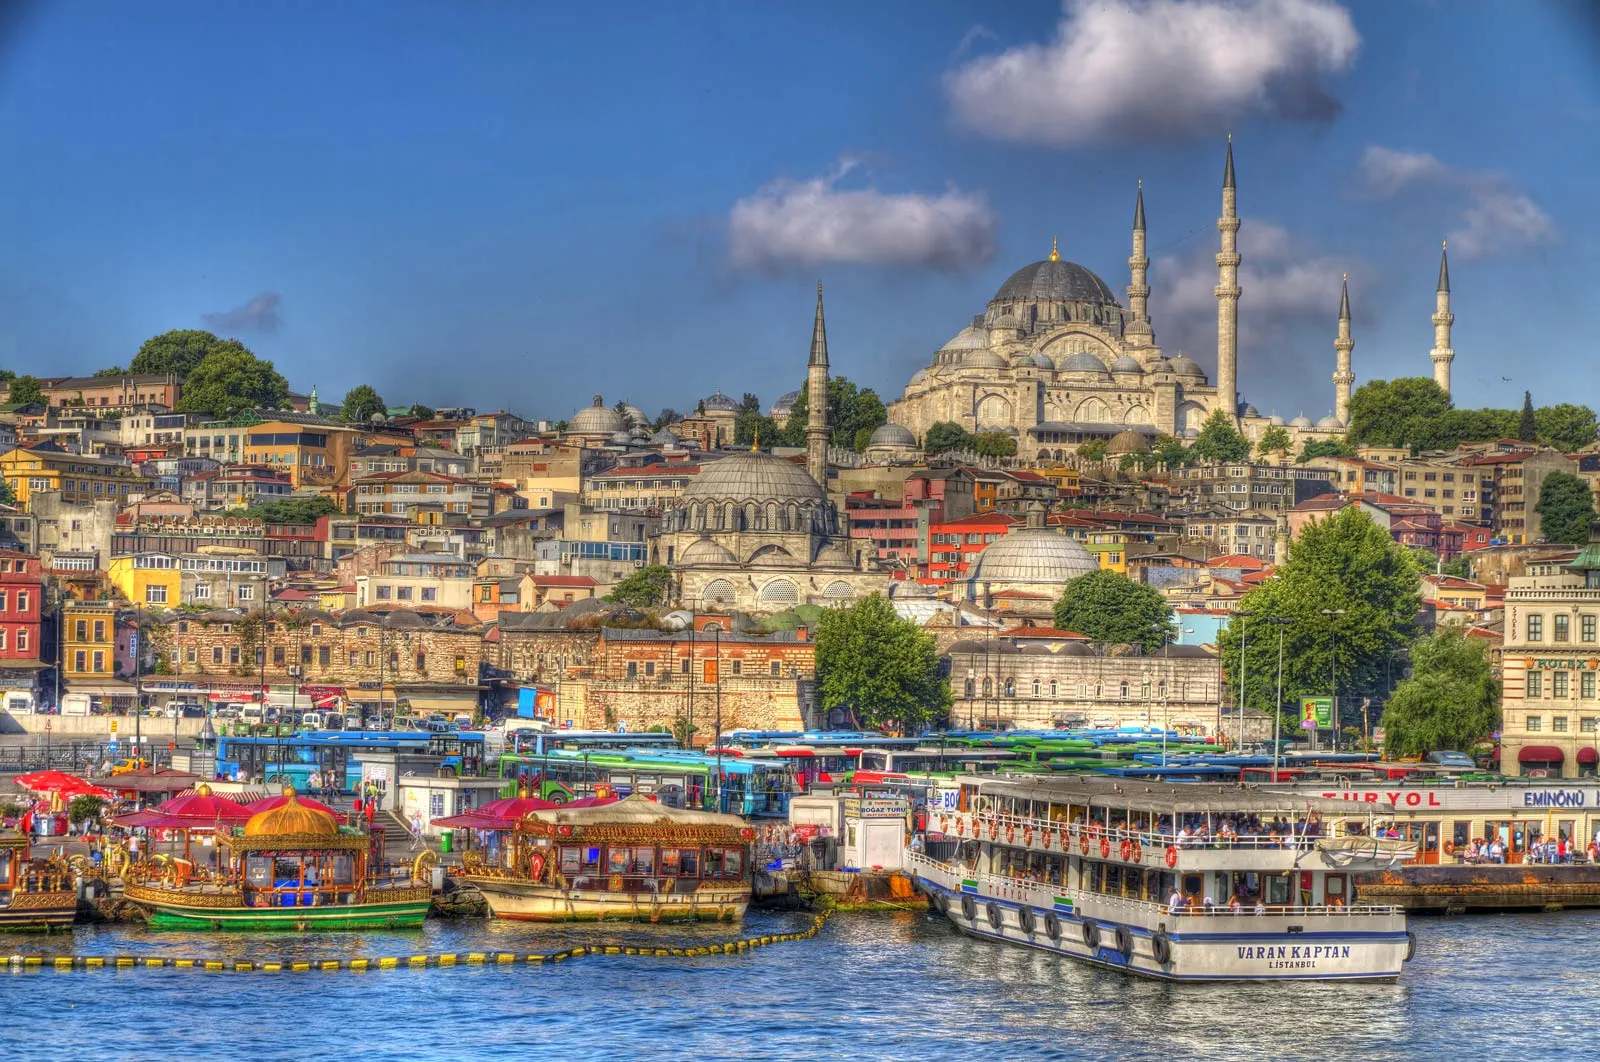
Istanbul serves as the country’s financial and technology centre, supported by the developing Istanbul Financial Center and major institutions including Türkiye İş Bankası, Akbank, Garanti BBVA, Yapı Kredi, and state-owned Ziraat Bankası. The broader economy, encompassing manufacturing, automotive production, textiles, tourism, construction, agriculture, logistics, and services, underpins a diversified base positioned between Europe, the Middle East, and Central Asia.
How Turkish Payment Infrastructure Works
A central feature of the Turkey fintech ecosystem is FAST, the Instant and Continuous Transfer of Funds system introduced by the Central Bank of the Republic of Türkiye (CBRT) in January 2021. FAST enables continuous fund transfers between participating institutions within seconds, operating independently of conventional banking hours.
FAST works alongside the Easy Addressing System (KOLAS), which allows consumers to transfer funds using a telephone number, email address, or identification number instead of an IBAN. By the end of 2024, KOLAS had reached 24.7 million individual users. The FAST transfer limit was increased to TRY100,000 (approximately $2,093) in 2024, while merchant payments using dynamic FAST-TR QR codes could reach TRY250,000 (approximately $5,232); those limits remained in place through the following year.
This infrastructure provides an alternative to conventional card payment networks, allowing funds to move directly between accounts through domestic rails rather than international card processing systems.
Central Bank Infrastructure vs Private Fintech Companies
While much fintech innovation globally originates with private start-ups, Türkiye’s most significant payment infrastructure has been built by the central bank itself. Private companies have concentrated instead on building consumer-facing applications and services on top of this public infrastructure, including payment processing, investment platforms, and embedded finance tools.
Key Companies Shaping the Sector
Türkiye has produced fintech companies that have achieved international transactions of scale. Payment infrastructure provider iyzico, built to serve online merchants and marketplaces, was acquired by Prosus in 2019 for $165 million. In 2025, Turkish payments company Param agreed to acquire iyzico from Prosus in a transaction valued at $87 million, consolidating two significant parts of the country’s payments ecosystem.
Midas has extended financial technology into investment services, operating a mobile platform that gives Turkish consumers access to Borsa Istanbul and US equities through a digital-first interface. Additional companies operate across embedded finance, open banking, SME services, insurance technology, and business payments, reflecting a sector that has moved from early-stage experimentation toward established commercial operations.
Costs, Impact, and the Digital Lira Initiative
Beyond existing infrastructure, the CBRT has been developing a Digital Turkish Lira, joining central banks internationally examining whether sovereign currency should become programmable and digitally native. Initial development phases included payment transaction testing, with subsequent work addressing digital identity, mobile applications, and interoperability.
Türkiye’s approach to central bank digital currency development is shaped by existing conditions: sophisticated domestic payment infrastructure, widespread smartphone adoption, and a large digitally active population. A digital lira could operate alongside FAST rather than replacing it, adding another layer of public digital-money infrastructure. Whether consumer demand justifies this addition, given that existing instant payment systems already function efficiently, remains an open question.
Risks and Limitations
Rapid growth in the Turkey fintech ecosystem has drawn increased regulatory scrutiny. The payments sector has faced stronger supervision as authorities focus on safeguarding customer funds, addressing money laundering risks, fraud, and illegal betting activity. This reflects a broader principle: as fintech companies hold growing amounts of customer funds within applications, they take on a position of trust historically associated with licensed banks rather than technology start-ups.
Currency volatility also presents an ongoing risk. High inflation, projected at around 28.6% for 2026 according to IMF estimates, and historical depreciation of the Turkish lira create operating conditions that differ significantly from more stable developed markets. Fintech companies operating in Türkiye must account for these macroeconomic factors when designing products and managing financial risk. Additionally, this analysis draws primarily on data specific to the Turkish market; growth patterns and regulatory frameworks in neighbouring markets may develop differently.
Future Outlook
Türkiye’s geographic position is expected to remain a structural advantage for its fintech sector. Istanbul sits within several hours’ flight of much of Europe, the Middle East, North Africa, the Caucasus, and Central Asia, a position the Istanbul Financial Center aims to leverage in attracting financial institutions, international investors, and technology companies.
Industry observers suggest that products tested among more than 80 million domestic consumers could potentially be adapted for neighbouring markets sharing similar payment behaviours, demographics, or financial infrastructure characteristics. Whether Türkiye’s fintech sector successfully transitions from a domestically focused industry into a regional export base will depend on continued regulatory development, currency stability, and the pace of infrastructure adoption across bordering markets.
Conclusion
The Turkey fintech ecosystem has developed substantially since its early growth phase, supported by central bank infrastructure including the FAST instant payment system and an ongoing Digital Turkish Lira initiative. Companies such as iyzico, Param, and Midas illustrate a sector capable of producing internationally relevant transactions and platforms, even as the broader economy contends with elevated inflation and currency pressure. Increased regulatory oversight reflects the sector’s growing role within the formal financial system, positioning Türkiye’s fintech industry for continued development amid ongoing macroeconomic uncertainty.

