


Introduction
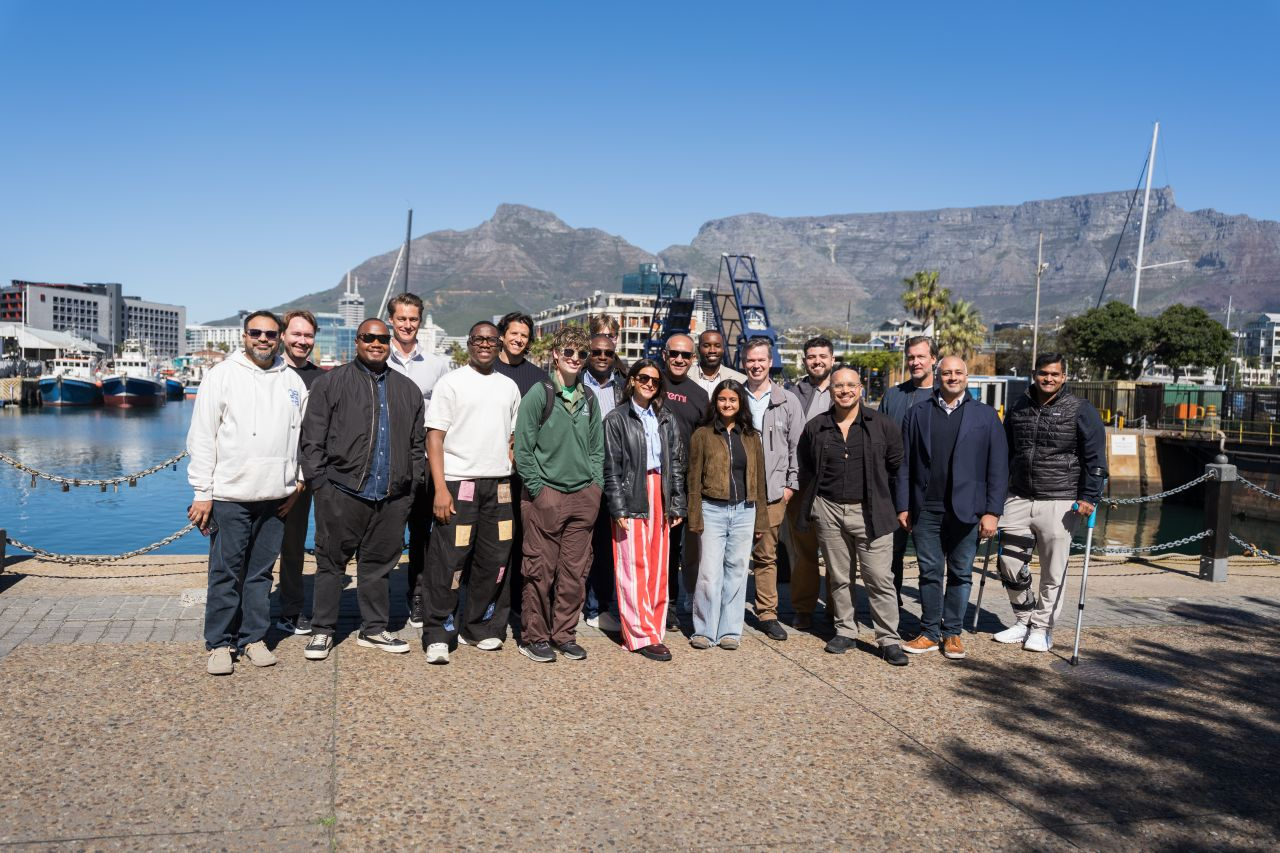
Ten financial technology startups from the UAE, Africa, Asia, Europe and the United States have assembled in Cape Town, South Africa, for a 12-week accelerator program focused on cross-border payments, foreign-exchange management, trade finance and digital-dollar access.
The initiative is being delivered through CV VC’s Startup Activation Service, combining the Stellar network with CV Labs’ international incubator infrastructure in Switzerland, the UAE, Germany, Liechtenstein, Portugal and South Africa. The program is aimed at established founders developing financial infrastructure for markets where traditional banking and payment systems can create significant cross-border friction.
Rather than focusing on early-stage product development, the cohort is centered on companies that already have operating businesses and are seeking commercial expansion, partnerships and access to international financial and technology ecosystems.
What the Stellar and CV VC Fintech Program Is
The program brings together startups developing financial applications on blockchain and digital-asset infrastructure.
Its central focus is the movement of money across borders, an area that remains fragmented because businesses and consumers often have to navigate different banking systems, currencies, payment networks and regulatory environments.
The participating companies are working on different parts of that infrastructure. Their products include foreign-exchange tools, payment processing, trade finance, digital wallets, stablecoin infrastructure, financial operating systems and cross-border banking services.
The program provides participating companies with access to the Stellar Development Foundation ecosystem, CV Labs’ network and commercial connections in several financial and technology centers.
The startups are scheduled to present their progress at an in-person Demo Day during Stellar Meridian 2026 in Lisbon, Portugal.
How the Startups Are Addressing Cross-Border Payments
International payments can involve multiple intermediaries and settlement systems. Currency conversion can add another layer of complexity, particularly for companies operating across several markets.
The selected startups are approaching these problems from different angles.
Foreign exchange and stablecoin infrastructure
Crebit Pay, based in the United States, is developing a rate-locking layer for stablecoin foreign exchange. Its stated objective is to provide greater price predictability for corporate cross-border payments.
Remi, headquartered in the UAE, is working on infrastructure connecting traditional banking networks with digital-asset liquidity for cross-border transfers in emerging markets.
These models reflect growing interest in combining conventional financial infrastructure with blockchain-based settlement mechanisms.
Payment collection and reconciliation
JoonaPay of Côte d’Ivoire is developing financial operations infrastructure for Francophone African businesses. Its platform is designed to connect mobile money, traditional banking and stablecoin payment rails.
The company’s focus highlights one of the challenges facing businesses operating across African markets: payment systems are often fragmented between countries and between traditional banks and mobile-money networks.
Digital-dollar access
Sorted, from Hong Kong, is developing a non-custodial wallet framework aimed at expanding access to digital dollars across South Asia and Africa.
Saleem, based in the UAE, is taking a different approach. Its infrastructure is designed to facilitate stablecoin payments through feature phones, without requiring a smartphone or conventional bank account. Its initial target corridors include Syria and the Levant.
These models illustrate how fintech developers are exploring alternatives for populations that may have limited access to conventional banking infrastructure.
Trade Finance and Supply Chains Are Another Focus
Cross-border finance extends beyond payments.
Companies engaged in international trade need working capital, payment guarantees, settlement mechanisms and financing for goods moving between jurisdictions. Smaller businesses can face additional constraints because they may have limited access to conventional trade-finance products.
Kutana, based in Ghana, is developing decentralized trade-finance infrastructure intended to provide African small and medium-sized enterprises with access to import-export liquidity.
Janus, from Germany, is developing a financial operating system for global trade logistics and supply chains.
DeFa by InvoiceMate, headquartered in the UAE, is focused on secondary settlement liquidity for licensed cross-border payment operators working across Africa and the Gulf.
The different approaches demonstrate that blockchain applications in financial services are extending beyond cryptocurrency trading into settlement, liquidity and business-to-business financial infrastructure.
The 10 Startups in the 2026 Cohort
The inaugural group includes companies operating across several financial technology segments:
| Startup | Location | Primary focus |
|---|---|---|
| Crebit Pay | United States | Stablecoin FX and corporate cross-border payments |
| DeFa by InvoiceMate | UAE | Settlement liquidity for payment operators |
| Janus | Germany | Trade logistics and supply-chain finance |
| JoonaPay | Côte d’Ivoire | Multi-rail payments and reconciliation |
| Kutana | Ghana | Decentralized trade finance |
| Remi | UAE | Banking and digital-asset liquidity |
| Saleem | UAE | Feature-phone stablecoin payments |
| Sly | United States | Identity, governance and payments for AI agents |
| Sorted | Hong Kong | Non-custodial digital-dollar wallets |
| Yolat | Nigeria | Multi-currency cross-border banking |
Sly is developing infrastructure for what it describes as agentic finance, including decentralized identity, governance and payment capabilities for AI agents.
Meanwhile, Yolat is building a multi-currency cross-border neobank for African businesses and individuals, with functions designed around earning, holding and transacting in multiple currencies.
Why Africa and Emerging Markets Are Central to the Program
Africa is an important part of the cohort, with startups from Côte d’Ivoire, Ghana and Nigeria, while several other participating companies are developing products targeting African markets.
Cross-border financial infrastructure is particularly relevant in emerging markets because businesses and individuals can operate across multiple currencies and payment systems while maintaining relationships with banks, mobile-money providers and international financial institutions.
The World Bank’s Remittance Prices Worldwide database has consistently documented substantial differences in the cost of sending money across international corridors. Those costs are influenced by competition, infrastructure, regulation, transaction size and the characteristics of individual corridors.
Blockchain-based payment systems are being developed partly in response to these structural issues. However, blockchain does not eliminate the need for regulated financial institutions, local payment connections, compliance systems or appropriate consumer protections.
The Role of Stablecoins in Cross-Border Finance
Stablecoins are an important common theme across several companies in the cohort.
Unlike cryptocurrencies whose market prices can fluctuate significantly, stablecoins are generally designed to maintain a relatively stable value against a reference asset, often a fiat currency such as the US dollar.
Their potential role in cross-border finance is linked to settlement. A digital token representing a dollar-denominated value can move across a blockchain network without following the same technical pathway as a conventional bank transfer.
However, the financial and regulatory characteristics of stablecoins vary considerably between issuers and jurisdictions.
Questions around reserves, redemption, custody, consumer protection, anti-money-laundering controls and regulatory status remain important. The Financial Stability Board and other international bodies have highlighted the need for regulatory oversight of global stablecoin arrangements and crypto-asset activities.
For businesses using stablecoins for payments, the underlying technology is therefore only one part of the financial infrastructure.
Costs, Commercial Opportunities and Operational Implications
The potential economic impact of cross-border fintech infrastructure extends beyond transaction speed.
Companies can face costs associated with foreign-exchange conversion, payment intermediaries, reconciliation, liquidity management and delays in receiving funds.
Technology that reduces manual reconciliation or connects previously separate payment systems can potentially change the cost structure of international transactions.
At the same time, implementing new infrastructure can create additional costs. These may include technology integration, compliance systems, cybersecurity, licensing, liquidity management and connections to local financial institutions.
For regulated financial companies, the ability to demonstrate compliance can be as important as technical performance.
The 12-week program is therefore positioned not simply as a technology accelerator but as a commercial-development platform connecting startups with investors, mentors and potential strategic partners.
Risks and Limitations
The expansion of blockchain-based financial infrastructure also introduces risks.
Regulatory fragmentation
Financial regulation differs substantially between jurisdictions. A payment model that operates in one country may require different licenses, partnerships or controls elsewhere.
Stablecoin and liquidity risks
Stablecoin-based payments depend on the reliability of the token, its issuer, redemption mechanisms and the liquidity available in the relevant market.
Cybersecurity
Digital wallets, blockchain applications and payment platforms remain potential targets for cyberattacks, fraud and operational failures.
Financial inclusion does not happen automatically
A technology platform can reduce certain barriers while leaving others unresolved. Users may still need access to mobile connectivity, cash-in and cash-out infrastructure, identification systems or regulated financial institutions.
Cross-border compliance
International payment providers must contend with anti-money-laundering requirements, sanctions regimes, customer identification requirements and other financial controls. These obligations remain relevant regardless of whether a transaction is settled through conventional banking infrastructure or blockchain networks.
Switzerland, the UAE and Africa Form Key Commercial Hubs
The accelerator gives participating startups access to two major ecosystems highlighted by the program: Switzerland’s Crypto Valley and the UAE, alongside African markets.
Switzerland has developed a significant ecosystem around blockchain and digital-asset companies, while the UAE has positioned itself as a regional hub for financial technology and digital assets.
Africa provides a different dimension. Many markets have experienced rapid adoption of mobile money and digital financial services, creating an environment in which alternative payment infrastructure can develop alongside traditional banking.
The combination gives startups access to different regulatory, commercial and technological environments. It also exposes them to the practical challenge of adapting financial products to different markets.
Future Outlook for Cross-Border Fintech Infrastructure
The Stellar-CV VC program reflects a broader industry movement toward programmable payments, digital assets and interoperable financial infrastructure.
The participating startups are working on different components of that transition, from foreign-exchange management and trade finance to digital wallets and payment infrastructure.
The longer-term development of these systems will depend on several factors, including regulatory clarity, institutional adoption, interoperability, cybersecurity, liquidity and the ability of fintech companies to integrate with existing financial networks.
For emerging markets, the outcome will also depend on whether new infrastructure can connect effectively with local banks, mobile-money systems and established payment providers.
The program’s 12-week structure provides a mechanism for testing commercial models and developing partnerships, with the cohort’s progress expected to culminate in the Stellar Meridian 2026 Demo Day in Lisbon.
Conclusion
The selection of 10 fintech startups from the UAE, Africa, Asia, Europe and the United States highlights the range of technologies being developed around cross-border financial infrastructure.
The companies are addressing different problems, including foreign-exchange risk, payment reconciliation, trade finance, digital-dollar access, settlement liquidity and multi-currency banking.
Blockchain and stablecoins form an important part of several of these models, but their commercial development remains dependent on regulation, financial partnerships, cybersecurity and local market infrastructure.
The Stellar and CV VC program provides a structured environment for established fintech companies to develop those commercial connections while testing how digital financial infrastructure can operate across multiple regions.

