


Venezuela’s financial system has undergone a profound transformation as years of economic instability, currency depreciation, migration and restrictions on international financial access changed how households and businesses manage money. The result is a Venezuela fintech market shaped less by conventional technological disruption than by the practical need to move, receive and preserve value in a difficult monetary environment.
The country’s experience combines several financial systems operating at the same time. Bolívares remain the official currency, while US dollars are widely used in commerce. Mobile bank transfers have become an important payment mechanism, digital financial services have emerged around gaps in traditional banking, and cryptocurrency has periodically provided another channel for transferring or holding value.
This makes Venezuela an important case study in how financial technology can evolve when economic conditions themselves become the primary driver of innovation.
Venezuela’s Economy and the Financial System
Venezuela’s economy has historically been dominated by petroleum. The country holds the world’s largest proven crude-oil reserves, and oil exports have traditionally generated the majority of its export earnings.
The broader economy includes manufacturing, agriculture, mining, retail and services, but petroleum remains central to the country’s economic structure.
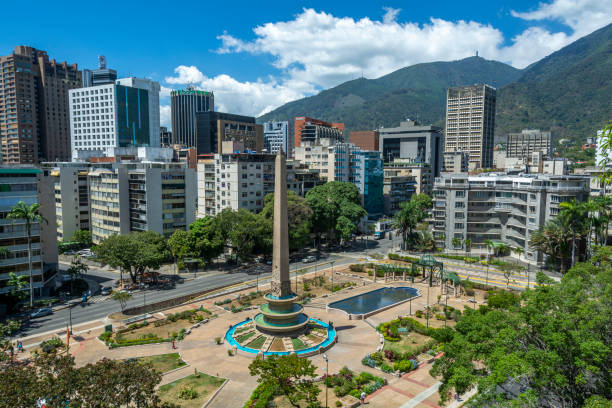
Caracas is the country’s principal financial centre, with major institutions including Banco de Venezuela, Banesco, BBVA Provincial and Banco Mercantil.
The scale of Venezuela’s economic contraction has, however, changed the environment in which these institutions operate.
According to the International Monetary Fund’s April 2026 World Economic Outlook database, Venezuela’s nominal GDP is projected at approximately $111.3 billion in 2026, equivalent to about $4,140 per person. The population is estimated at approximately 26.9 million.
Inflation remains a defining challenge. The IMF projects average consumer-price inflation of approximately 387% in 2026.
For financial technology companies, such an environment creates operational challenges that are uncommon in more stable economies. Prices can change rapidly, purchasing power can deteriorate quickly and consumers may need to manage transactions across more than one currency.
How Economic Instability Changed Payments
Venezuela’s payment ecosystem developed around the practical requirements of consumers and merchants.
One of the most important developments has been Pago Móvil Interbancario, a system that enables rapid transfers between participating bank accounts using information such as a mobile telephone number and identity details.
The significance of mobile payments extends beyond convenience.
A customer can use a mobile transfer to settle a restaurant bill, pay a taxi driver or purchase goods from a small merchant without necessarily relying on cash or a conventional card terminal.
This illustrates a broader feature of digital payments in Venezuela: technology has been adopted partly because it addresses practical weaknesses or limitations within traditional payment channels.
The World Bank reported that more than 45% of Venezuelan adults were making digital merchant payments in 2020, placing Venezuela among the higher-adoption markets in Latin America at that time. The World Bank’s 2024 Global Findex survey also includes Venezuela, providing a newer dataset for examining changes in financial and digital behaviour.
The Venezuelan experience therefore shows that economic instability and digital-payment adoption can coexist. In some circumstances, financial pressure can encourage consumers to adopt payment methods that make transactions faster and more flexible.
Dollarisation Created a Multi-Currency Payment Environment
Another defining feature of Venezuela’s financial system is the widespread use of the US dollar.
As the bolívar lost purchasing power during the country’s prolonged economic crisis, consumers and businesses increasingly began using dollars to price and settle transactions.
This created a form of informal or bottom-up dollarisation.
A household could receive money through one channel, make a purchase in dollars and use a bolívar-denominated bank transfer for another transaction. The result is a financial environment in which different payment mechanisms and currencies can coexist.
For fintech businesses, this creates both opportunities and operational complexity.
Financial products have to accommodate customers who may hold or receive funds in different forms. Payment infrastructure must also account for the distinction between the country’s official currency and the currency frequently used by consumers for pricing or settlement.
The result is a market in which multi-currency finance in Venezuela is not simply a specialist financial product but part of everyday economic behaviour.
Fintech and the Consumer Credit Gap
Payment technology is only one part of Venezuela’s fintech development. Consumer credit has also created an opening for financial technology companies.
Cashea is an example of a company operating a buy-now-pay-later model in Venezuela. Its service allows consumers to purchase goods and repay the cost through instalments.
The model addresses a financing environment that has been heavily affected by inflation.
Traditional credit cards historically played an important role in consumer financing. But prolonged inflation reduced the real value of credit limits, while conventional lending became more difficult to operate in an unstable monetary environment.
Cashea developed an alternative mechanism for consumer purchases.
Customers can make payments through channels including Pago Móvil, bank transfers and bolívar deposits, while certain transactions can also involve US-dollar payments.
Its payment arrangements demonstrate how fintech products in Venezuela have evolved around local financial conditions rather than simply replicating models developed in more stable markets.
The broader lesson is that fintech innovation does not necessarily begin with a new piece of technology. It can begin with a financial service that consumers need but that the existing system is no longer delivering efficiently.
In Venezuela, access to consumer financing became one such gap.
Cryptocurrency and Stablecoins in Venezuela
Cryptocurrency has also played a role in Venezuela’s financial landscape.
The country’s economic conditions created circumstances in which alternative forms of digital value could attract attention. A domestic currency experiencing substantial depreciation can increase interest in assets denominated in currencies perceived as more stable.
Stablecoins are particularly relevant because some are designed to maintain a value linked to currencies such as the US dollar.
For Venezuelan users, cryptocurrency can therefore have purposes beyond investment speculation. Digital assets may be used in some circumstances for international transfers, access to dollar-denominated digital value or as an alternative method of holding funds.
Venezuela also conducted its own experiment with a state-backed digital currency.
The Petro, introduced in 2018 and associated with the country’s petroleum resources, was eventually discontinued in 2024.
The contrasting experiences of the Petro and privately used cryptocurrency demonstrate an important distinction: government-sponsored digital currencies and consumer-driven digital-asset adoption can develop for very different reasons.
Remittances Became a Major Digital Finance Use Case
Venezuela’s migration crisis has also influenced the country’s financial technology ecosystem.
Millions of Venezuelans have migrated to countries including Colombia, Peru, Chile, Spain and the United States, creating extensive cross-border communities with financial links to relatives remaining in Venezuela.
Those links make remittances an important part of the country’s digital-finance landscape.
Traditional money-transfer companies increasingly operate alongside digital payment platforms, international financial applications and, in some cases, cryptocurrency-based transfer mechanisms.
For recipients, however, receiving money is only part of the financial decision.
Currency choice matters because converting funds immediately into bolívares can expose recipients to the effects of rapid inflation. Some households may therefore have an interest in holding value in dollars or another relatively stable asset where available and permitted.
This creates a direct connection between Venezuelan remittances, currency depreciation and fintech.
The country’s diaspora has effectively created a cross-border financial network in which payment technology, migration and currency management intersect.
Infrastructure Is a Critical Constraint
Financial technology cannot operate independently of physical infrastructure.
Venezuela’s electricity and telecommunications challenges therefore represent a significant constraint on digital finance.
Years of underinvestment have weakened parts of the country’s electricity-generation and distribution infrastructure. Power interruptions can affect businesses and consumers for extended periods in some communities.
The implications for fintech are straightforward.
A mobile payment requires a functioning device and communications network. Digital banking requires electricity and telecommunications. A merchant using a QR-based payment system still needs access to a functioning digital network.
This means the development of Venezuela’s fintech sector is linked to broader infrastructure conditions.
Technology can reduce some barriers to financial access, but it cannot completely compensate for unreliable electricity, telecommunications limitations or restricted connections to international financial infrastructure.
Regulatory and Political Conditions Remain Important
Venezuela’s financial environment has also been shaped by political developments, international sanctions and changes in its relationship with foreign financial institutions.
Years of political confrontation and disputed elections contributed to uncertainty during the Nicolás Maduro era, while sanctions complicated parts of Venezuela’s relationship with the international financial system.
These factors matter to fintech because digital financial businesses depend on more than consumer demand.
They need payment networks, banking relationships, telecommunications infrastructure, regulatory clarity and, where international transactions are involved, access to cross-border financial systems.
Consequently, the development of Venezuela fintech regulation cannot be separated entirely from the country’s broader economic and political environment.
The 2026 environment also remains subject to uncertainty surrounding Venezuela’s longer-term political settlement, future elections, external debt and investment conditions.
What Venezuela’s Fintech Market Shows
Venezuela offers a distinctive example of financial adaptation under severe economic pressure.
Several developments illustrate this transformation:
- Mobile payments: Pago Móvil has helped make rapid bank transfers part of everyday commerce.
- Multi-currency transactions: Bolívares and US dollars coexist in the financial lives of consumers and businesses.
- Alternative consumer credit: Companies such as Cashea have developed instalment-based financing models.
- Digital assets: Cryptocurrency and stablecoins have provided additional mechanisms for some users to transfer or hold value.
- Remittances: Migration has increased demand for cross-border financial services.
- Infrastructure dependence: Electricity and telecommunications remain fundamental limitations for digital finance.
Together, these developments show that fintech markets do not always evolve because consumers are seeking the newest technology. They can evolve because existing financial systems fail to meet changing economic needs.
Risks and Limitations for Venezuelan Fintech
The same conditions that create opportunities for financial technology also introduce significant risks.
Currency risk
Rapid changes in the value of the bolívar can complicate pricing, lending, savings and financial planning.
Infrastructure risk
Electricity and telecommunications disruptions can interrupt digital payments and banking services.
Cross-border restrictions
International sanctions and restrictions affecting financial institutions can make cross-border transactions more difficult and increase compliance requirements.
Consumer-credit risk
Alternative lending products can expand access to financing, but borrowers and providers remain exposed to repayment and inflation-related risks.
Digital-asset risk
Cryptocurrency and stablecoins introduce technological, regulatory, liquidity and counterparty considerations that vary by asset and platform.
Financial inclusion gaps
Digital adoption does not automatically mean universal access. Consumers still require suitable devices, connectivity, banking access and sufficient financial literacy to use digital services effectively.
The Future of Fintech in Venezuela
The future trajectory of Venezuela’s fintech sector will depend heavily on the wider economy.
Sustained monetary stability, stronger infrastructure, greater investment and improved access to international financial networks could create conditions for financial technology companies to expand beyond crisis-driven solutions.
At the same time, the behaviours developed during years of instability may continue to influence the market.
Consumers have become accustomed to mobile transfers, multi-currency transactions and alternative financial channels. Companies that understand these behaviours may continue developing products around payments, credit, remittances, digital identity and financial management.
The key question is therefore not whether Venezuela can adopt financial technology. Its experience already demonstrates that it can.
The more important question is how the fintech ecosystem evolves if the economic conditions that originally created demand for many of these services begin to change.
Conclusion
Venezuela’s fintech sector is closely tied to the country’s economic history.
The collapse in the purchasing power of the bolívar, widespread dollar use, mass migration, restricted international financial access and weaknesses in conventional credit all contributed to an environment in which consumers and businesses had to adapt how they move and store money.
Pago Móvil helped expand instant digital transfers. Dollarisation created a multi-currency economy. Cashea addressed part of the consumer-credit gap, while cryptocurrency and digital remittance channels provided additional options for some users.
Yet fintech cannot solve every underlying economic problem. Reliable electricity, telecommunications, monetary stability, regulatory clarity and access to international financial infrastructure remain important foundations.
Venezuela’s experience ultimately illustrates a broader principle in financial technology: innovation can emerge not only from technological progress, but also from the need to adapt to a changing financial reality.

