
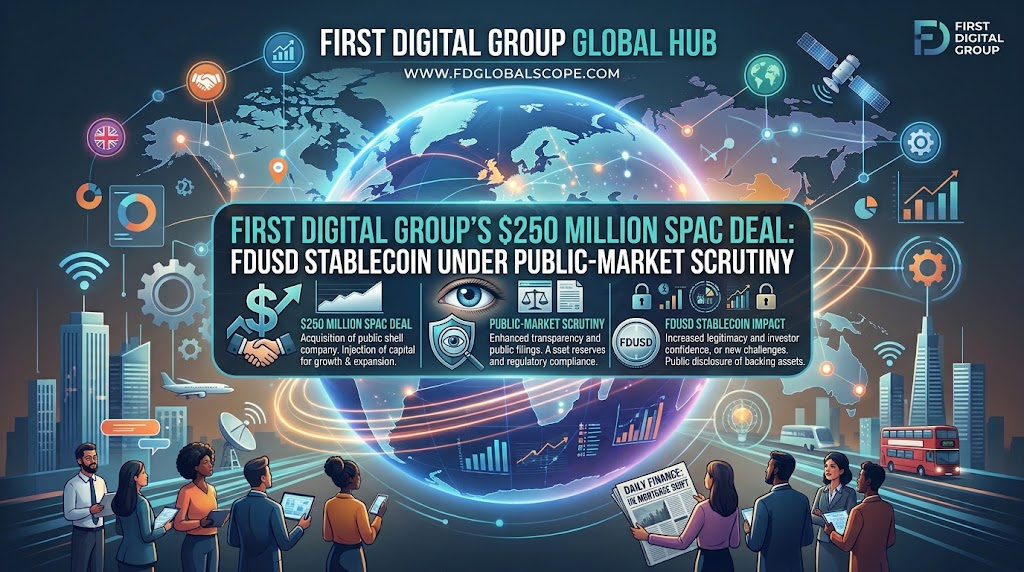
First Digital Group, the Hong Kong-based issuer of the FDUSD stablecoin, has agreed to combine with CSLM Digital Asset Acquisition Corp III (Nasdaq: KOYN) in a transaction that values First Digital at $250 million on a pre-money equity basis.
The proposed transaction is expected to create a Nasdaq-listed holding company incorporated in the Cayman Islands during the first half of 2027, subject to shareholder approval, SEC registration and other regulatory clearances. The deal would give First Digital access to US public markets while placing its stablecoin business under greater investor and regulatory scrutiny.
The transaction comes as stablecoin issuers increasingly move beyond cryptocurrency trading toward payments, settlement and automated commerce. First Digital is positioning its planned Finance District ecosystem around that transition, including potential payments involving AI agents. However, the business currently generates little material revenue from that new segment, making the valuation and future growth assumptions important considerations for investors and regulators.
What the First Digital and KOYN Deal Means
The transaction is structured as a business combination between First Digital and CSLM Digital Asset Acquisition Corp III, a special purpose acquisition company, or SPAC.
Under the proposed arrangement, the resulting company would be publicly listed on Nasdaq. First Digital founder and chief executive Vincent Chok would retain significant voting control through Class B ordinary shares carrying 10 votes per share.
The transaction does not include a minimum cash condition.
Institutional investors have already purchased $20 million of KOYN Class A ordinary shares at $10.60 per share from existing KOYN holders.
First Digital has also entered into a non-binding term sheet with Millennial Trading for a $25 million zero-coupon convertible note with a $12.00 conversion price. The agreement remains subject to definitive documentation, and the company has cautioned that the proposed financing may not ultimately be completed.
The transaction therefore combines a public-market listing with additional potential financing rather than relying solely on the SPAC structure to provide capital.
Advisory structure
Cohen & Company Capital Markets is acting as capital markets and M&A adviser to First Digital.
DLA Piper is advising First Digital on legal matters, while Loeb & Loeb is serving as legal counsel to KOYN.
First Digital’s FDUSD Business
First Digital launched FDUSD in 2023, with early adoption supported by its integration on Binance.
The company reported approximately $87 million in revenue for the fiscal year ended 30 June 2025.
FDUSD recorded more than $4.7 trillion in cumulative trading volume as of 30 June 2026, according to company information. Its circulating supply reached a peak of more than $4.4 billion in April 2024.
Those figures provide scale for the existing stablecoin operation, but trading volume should not be treated as equivalent to revenue. Stablecoin transaction volume can include multiple transfers and trading activity without producing an equivalent amount of economic income for the issuer.
That distinction is particularly relevant when assessing the proposed $250 million pre-money valuation.
How FDUSD Reserves Are Structured
FDUSD is designed as a fiat-referenced stablecoin, with reserves held in cash equivalents and short-dated US Treasury bills through First Digital Trust Limited.
The reserves are subject to independent monthly attestations.
For stablecoin issuers, reserve composition is a central issue because the ability to maintain a stable reference value depends partly on the quality, liquidity and accessibility of the assets backing the tokens in circulation.
US Treasury bills and cash equivalents are generally liquid reserve instruments, but investors and regulators also examine how reserves are held, who controls them, how redemptions work and whether the issuer has sufficient liquidity under periods of elevated redemption demand.
The proposed public listing could increase scrutiny of those arrangements because a listed company would face continuing disclosure and reporting obligations in addition to applicable stablecoin regulation.
The $250 Million Valuation Faces a Growth Test
The proposed $250 million pre-money equity valuation will be assessed against First Digital’s existing financial performance and its plans for new businesses.
The company’s reported $87 million revenue for the fiscal year ended 30 June 2025 provides an established financial base. However, the planned Finance District ecosystem does not yet contribute material revenue.
That creates a distinction between the value of the existing FDUSD business and the potential value attributed to future activities involving AI-enabled commerce.
Stablecoin volume versus business economics
FDUSD’s $4.7 trillion cumulative trading volume is significant as a measure of market activity, but it does not by itself establish the profitability or recurring revenue potential of the business.
Stablecoin issuers can generate revenue from activities associated with reserves, transaction services and related infrastructure. Their economics can also be affected by interest rates, token circulation, competition and changes in reserve requirements.
Consequently, the proposed public-market valuation will depend on more than historical transaction volume.
Investors are likely to examine the company’s revenue growth, reserve economics, operating costs, regulatory footprint and the extent to which Finance District develops into a commercially meaningful business.
Finance District Links FDUSD to AI Commerce
First Digital is positioning Finance District as infrastructure for an emerging model of commerce in which AI agents can conduct transactions on behalf of businesses and consumers.
The concept places FDUSD in a potential settlement role for automated payments.
That market remains at an early stage. AI agents can increasingly search for products, compare services and perform other commercial tasks, but financial institutions still need mechanisms to establish an agent’s identity, authority and payment credentials.
A stablecoin could theoretically provide an automated settlement mechanism, but the payment asset alone does not solve questions surrounding authorization, fraud, consumer protection or liability.
First Digital has cited third-party projections suggesting global agentic consumer-to-business spending could reach $1.7 trillion by 2030.
That estimate comes from the company’s investor materials and should therefore be viewed as a market projection rather than established market data. Actual adoption will depend on the development of AI agents, merchant acceptance, payment infrastructure, regulation and consumer trust.
Regulatory Expansion Is Central to First Digital’s Strategy
First Digital’s proposed Nasdaq listing comes as the company expands its regulatory footprint across multiple jurisdictions.
The company currently holds a Trust or Company Service Provider licence in Hong Kong and two Money Services Business registrations in Canada.
It also has a pending licence application with the Abu Dhabi Global Market for fiat-referenced token issuance.
The company intends to pursue additional authorisations in Europe, the UAE, Southeast Asia, Latin America and the United States.
This geographic strategy introduces both market opportunities and regulatory complexity. Stablecoin frameworks differ substantially between jurisdictions, particularly around reserve requirements, licensing, redemption rights, custody and permitted uses.
US regulation
The US is particularly important because a Nasdaq listing would place the company directly within the US public-markets environment while its stablecoin operations remain subject to applicable financial regulation.
The GENIUS Act and competing stablecoin proposals moving through Congress in 2026 are part of a broader effort to establish rules for payment stablecoins in the United States.
The eventual regulatory framework could affect how foreign-domiciled issuers structure US operations, obtain authorisations and distribute stablecoins to US customers.
Separately, the SEC’s review of the Form F-4 registration statement will be a key procedural milestone for the proposed transaction.
The combination therefore faces two distinct regulatory questions: whether the SPAC transaction can obtain the required securities approvals and whether First Digital can expand its stablecoin activities within the relevant US regulatory framework.
South Korea Adds Another Strategic Market
First Digital is also targeting South Korea as part of its international expansion.
The company has signed memoranda of understanding with Wavebridge, a KoFIU-registered company and subsidiary of ITCEN Group, to explore FDUSD distribution and settlement infrastructure.
A Korean branch office is planned for the first quarter of 2027.
South Korea is an important digital-asset market, but market access remains dependent on local regulatory requirements and relationships with regulated financial and technology infrastructure providers.
The planned arrangements therefore appear aimed not simply at token distribution but at building local settlement and institutional infrastructure around FDUSD.
Risks and Limitations of the SPAC Structure
The proposed transaction also carries risks associated with the SPAC model.
SPAC combinations can provide private companies with a route to public markets that differs from a conventional initial public offering. However, the resulting valuation can face substantial market scrutiny after the transaction closes.
The digital-asset sector has also produced examples of SPAC-led listings whose shares subsequently traded below the valuations established around their combinations.
That history does not determine the outcome for First Digital, but it illustrates the gap that can emerge between transaction valuation and public-market valuation.
The absence of a minimum cash condition is another relevant feature. The amount of capital ultimately available to the combined company can depend on transaction terms, financing arrangements, redemptions and other factors.
Founder control is also notable. With Class B shares carrying 10 votes per share, Vincent Chok would retain substantial voting influence after the transaction.
That structure can provide continuity of control but may also limit the voting influence of holders of ordinary Class A shares.
Future Outlook for First Digital and FDUSD
The proposed listing comes at a time when stablecoins are expanding into areas beyond cryptocurrency trading.
Payments, treasury management, cross-border settlement and automated commerce are among the potential applications attracting financial institutions and technology companies.
For First Digital, the challenge will be converting FDUSD’s existing trading activity into sustainable commercial use while developing Finance District into a meaningful business.
The company must also navigate licensing requirements across multiple jurisdictions and demonstrate that its reserve, compliance and operational systems can support a larger institutional footprint.
The planned first half of 2027 Nasdaq transaction remains conditional on shareholder votes, SEC registration and regulatory clearances. Until those conditions are satisfied, the proposed public listing remains a transaction in progress rather than a completed change in ownership or market status.
Conclusion
First Digital’s proposed combination with CSLM Digital Asset Acquisition Corp III would place the issuer of FDUSD among the publicly traded companies operating at the intersection of stablecoins, digital payments and AI-enabled commerce.
The $250 million pre-money valuation is modest relative to the company’s reported $87 million in fiscal 2025 revenue, but the market will need to distinguish between the economics of its established stablecoin business and the longer-term potential of Finance District.
FDUSD’s reported $4.7 trillion cumulative trading volume and previous circulation above $4.4 billion demonstrate significant market activity, while the company’s planned expansion across the UAE, Europe, Asia and the United States introduces a broader regulatory challenge.
If completed, the Nasdaq listing would provide First Digital with greater access to public capital markets and increase disclosure to investors. It would also subject the company and its stablecoin model to closer scrutiny over reserves, regulation, valuation, governance and the commercial viability of AI-driven payments.

