


Introduction
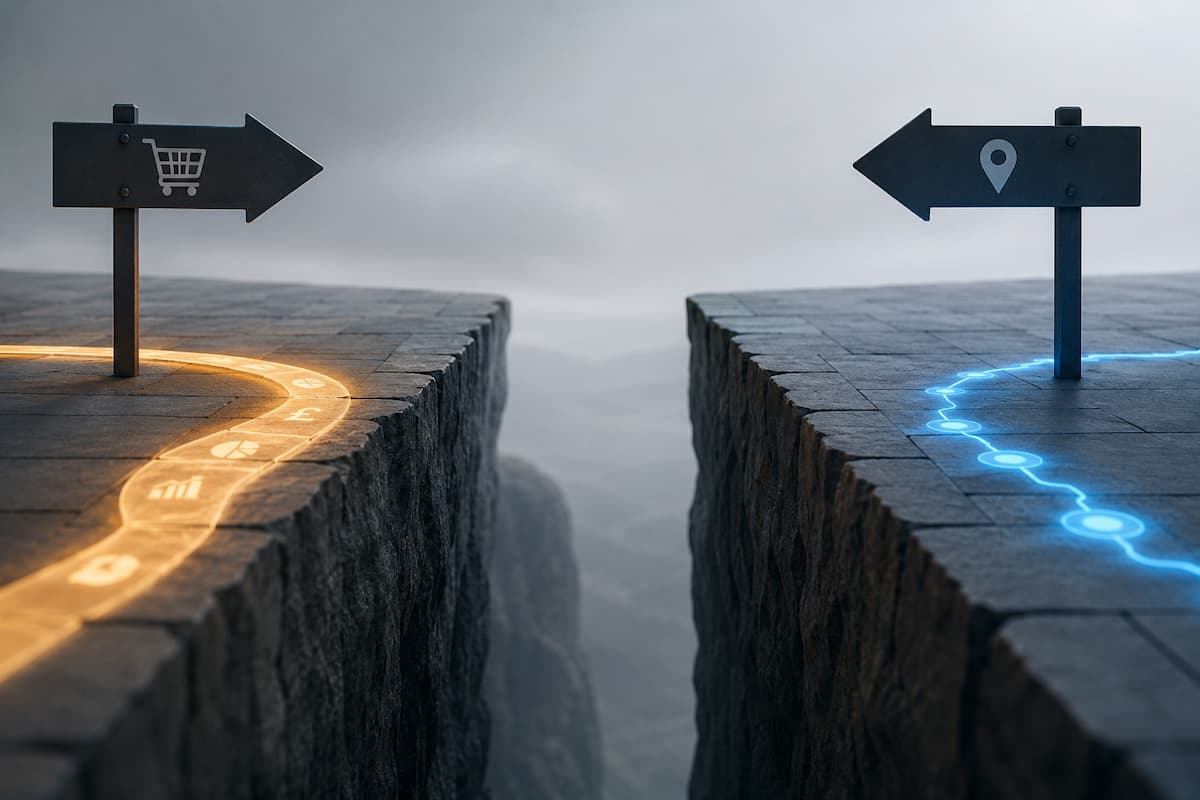
A structural gap exists in the UK financial support market between free general financial information at one end and regulated financial advice for wealthier households at the other. According to the Financial Conduct Authority’s own estimate, approximately 23 million people fall into the underserved space between these two categories, unable to access a regulated adviser but unable to find a definitive answer about their financial position from free information alone. A wave of financial-guidance platforms has emerged to address this gap, operating deliberately outside the UK’s regulated advice framework.
Syd Lawrence, founder of financial clarity platform Delphina, set out the operating distinction between financial advice and financial guidance, and the regulatory reasoning behind building a guidance product rather than a regulated advisory firm, in comments provided to The Fintech Times as part of its financial inclusion coverage. The distinction matters to consumers navigating financial decisions, to fintech firms designing products within or outside FCA regulatory perimeters, and to policymakers assessing whether the current advice-guidance boundary serves the households it is meant to protect.
What Financial Advice and Financial Guidance Mean Under UK Regulation
Under UK regulation, financial advice refers narrowly to a personal recommendation to buy, sell or hold a specific regulated financial product, a defined regulated activity. Questions such as whether an individual is on track for retirement, when they could realistically retire, or how to hold assets more tax-efficiently do not fall within this regulated definition, despite being commonly asked. Lawrence characterised the industry’s general reluctance to answer such questions, absent a formal recommendation, as a consequence of two decades of regulatory caution around a boundary that most consumers cannot perceive.
Financial guidance, by contrast, addresses a person’s current financial position and what could change it, without recommending specific products. Lawrence described advice as answering “what to buy” and guidance as answering “where you are,” positioning the two as distinct activities rather than points on the same continuum.
How Guidance Platforms Operate Within the Regulatory Boundary
Delphina, the platform Lawrence founded after completing a financial-adviser diploma, does not operate as a regulated advisory firm. According to Lawrence, the platform takes a user’s financial position, including income, spending, savings, pensions and debt, and returns an assessment of whether the person is on track and the approximate scale of any shortfall, without recommending a specific product.
Lawrence stated that Delphina does not sell products, take commission, or accept product referral fees, structuring the business so that no particular guidance outcome generates additional revenue. When a user’s situation is assessed as requiring regulated advice, Lawrence said the platform’s output is to direct the user to a regulated adviser rather than attempt to address the need internally.
Key Factors Shaping the Guidance Market
The FCA’s estimate of 23 million underserved consumers is a primary factor shaping demand for guidance platforms, representing a substantial share of the UK population positioned between free information and regulated advice. A second factor is business model structure: Lawrence stated that Delphina’s core verdict-generating function is offered free, with paid tiers covering ongoing tracking, scenario modelling and Monte Carlo simulations, and that approximately 5% of users convert to paid tiers.
User behaviour presents a further factor influencing platform design. Lawrence identified data entry, described as tedious and mildly discomforting for users, as the primary obstacle to platform engagement, and stated that Delphina’s returning-user rate rose from approximately 7% to approximately 30% after the platform was restructured to prioritise delivering a definitive verdict rather than a numerical projection.
Costs, Impact and Measurement Challenges
Lawrence stated that Delphina deliberately does not optimise for conventional engagement metrics such as time in app, daily active users or session length, arguing that a user who receives a clear answer and does not return for several months represents a successful outcome under the platform’s model, despite scoring negatively on standard engagement measures. The metric the platform tracks instead is whether a user reaches a completed verdict and subsequently takes action based on it.
Lawrence acknowledged that outcome measurement, of the kind that would demonstrate a specific improvement in a user’s financial position attributable to the platform, requires a multi-year timeframe and a larger user base than currently available, and stated a preference for acknowledging this limitation directly rather than presenting a proxy metric as a proven outcome.
Risks and Limitations
Lawrence acknowledged a structural limit to what guidance technology can address: where a user’s honest financial position shows a shortfall with no available surplus to close it, no software-based clarity resolves the underlying issue, which he characterised as a wages and cost-of-living matter falling outside the scope of a guidance platform.
The claims regarding user outcomes, return rates and platform impact in this analysis originate from the platform’s founder rather than from independent or regulator-verified data. As Delphina operates outside FCA regulation as a non-advice service, its guidance is not subject to the same regulatory oversight, complaints mechanisms or compensation protections that apply to regulated financial advice, a distinction relevant to consumers evaluating which type of service suits their needs.
Future Outlook
Lawrence indicated that near-term platform development is focused on reducing onboarding drop-off rather than adding new features, with new feature development paused to prioritise measurement of existing outcomes. Longer term, Lawrence stated an objective of developing sufficiently robust self-reported outcome data to more definitively answer questions about the platform’s impact on user financial positions.
On the broader financial guidance market, Lawrence characterised success as the emergence of a recognised middle-ground category between free information and regulated advice, populated by multiple credible providers rather than a single platform. No regulatory changes to the UK advice-guidance boundary have been announced by the FCA in connection with this trend.
Conclusion
The gap between free financial information and regulated financial advice in the UK, estimated by the FCA to affect approximately 23 million people, has prompted the emergence of guidance platforms operating deliberately outside the regulated advice perimeter. Delphina’s model, as described by its founder, illustrates one approach: a free core assessment product, a business model without product-linked incentives, and referral to regulated advice where warranted. Independent verification of outcome claims and broader questions about consumer protection for non-regulated guidance services remain open considerations for this emerging category.

