
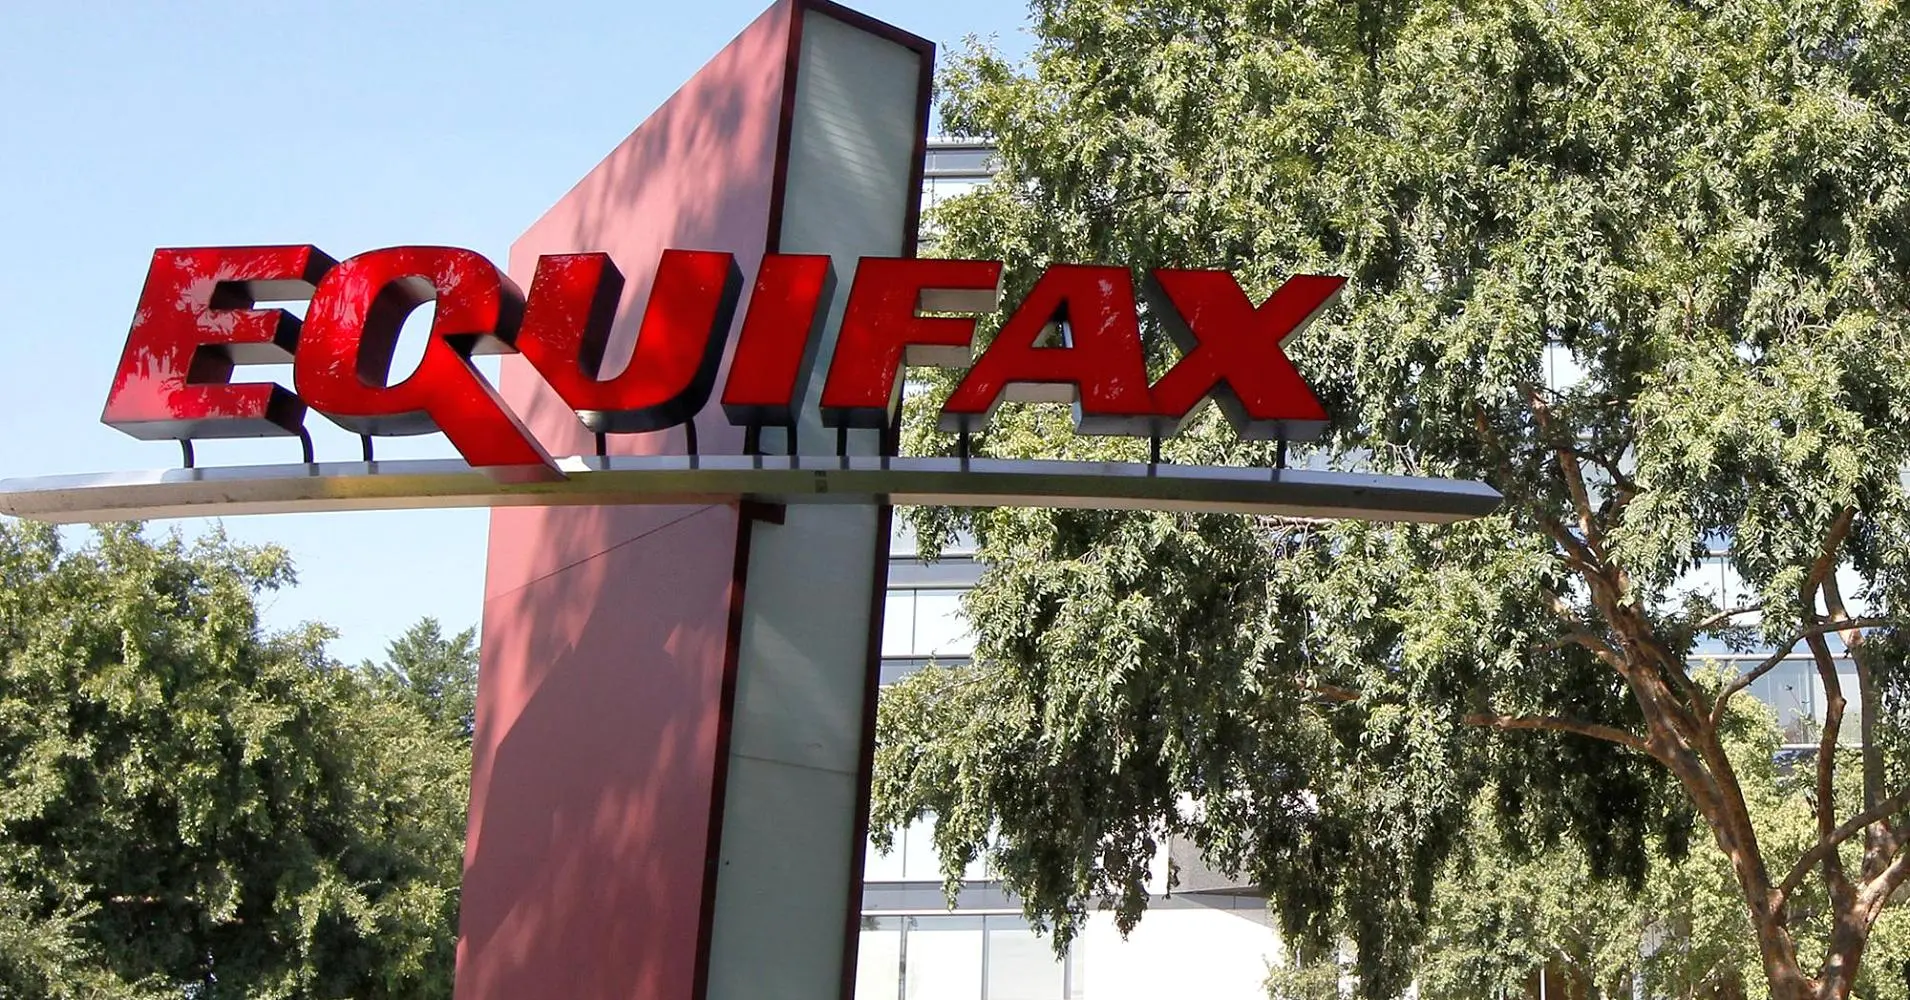
Equifax UK has launched Automated AML Watchlist Monitoring (AWM), a compliance tool designed to help regulated businesses continuously screen customers against sanctions, politically exposed persons (PEPs), relatives and close associates (RCAs), and adverse media sources.
The launch comes as UK financial services, insurance and gaming companies face continuing obligations to conduct customer due diligence and monitor relationships for potential money-laundering and financial-crime risks. Equifax developed the product in partnership with data provider NOTO, combining automated screening with a centralized case-management dashboard.
The development reflects a broader shift in AML compliance from periodic manual reviews toward technology-enabled, continuous monitoring. For regulated firms, however, automation does not remove the need for appropriate risk controls, human review and governance over potential matches.
What Is Equifax’s Automated AML Watchlist Monitoring?
Automated AML Watchlist Monitoring is a screening service that allows regulated businesses to monitor existing customer portfolios against multiple risk databases.
According to Equifax UK, the system can screen against:
- Global sanctions lists
- Politically exposed persons registers
- Relatives and close associates databases
- Adverse media sources
The service is delivered through a single API and includes a centralized dashboard for managing potential matches and compliance cases.
The approach is intended to address a limitation of periodic screening. A customer who presents no identifiable risk at onboarding may subsequently appear on a sanctions list, become a politically exposed person or become associated with adverse information.
Continuous monitoring is therefore increasingly relevant to customer due diligence programs where firms are required to maintain an up-to-date understanding of customer risk.
How Automated AML Screening Works
The Equifax system is designed to automate several stages of the watchlist-monitoring process.
Customer portfolio screening
Rather than requiring compliance teams to manually review customer records at predetermined intervals, AWM is designed to monitor portfolios automatically against updated risk information.
The system can identify potential matches and route them into a case-management process for further assessment.
Configurable matching thresholds
One of the key features is the ability for businesses to configure matching thresholds according to their risk frameworks.
This is important because automated name matching can produce two different problems. A system with highly sensitive matching may identify more potential risks but also generate a larger number of false positives. A less sensitive system may reduce the number of cases requiring review while increasing the possibility that relevant matches are missed.
Configurable thresholds allow compliance teams to determine how potential matches are escalated within their existing risk-management processes.
Centralized case management
The platform also provides a centralized dashboard and audit trail.
For regulated businesses, maintaining records of screening activity can be important when demonstrating how customer-monitoring controls operate during internal reviews or regulatory examinations.
The availability of an audit trail does not, however, by itself establish compliance. Firms remain responsible for determining whether their controls are appropriate to their business model and regulatory obligations.
Why Continuous AML Monitoring Matters in the UK
The launch comes against a backdrop of sustained regulatory attention on anti-money laundering controls in the UK.
The Financial Conduct Authority (FCA) has identified weaknesses in customer due diligence and ongoing monitoring among areas of concern in its supervision and enforcement work. The broader UK economic-crime framework has also continued to develop, including through the Economic Crime and Corporate Transparency Act 2023.
For regulated businesses, this creates a requirement to maintain systems capable of identifying changes in customer risk rather than relying exclusively on information collected at onboarding.
The issue extends beyond traditional banking.
Insurance companies, gaming businesses and other regulated sectors also operate customer-monitoring frameworks, although the specific obligations and supervisory expectations differ between industries.
The Gambling Commission, for example, has requirements concerning customer interaction and financial-risk controls that can increase the operational importance of effective customer screening and monitoring.
AML Technology Market Is Increasingly Competitive
Equifax enters a market that already includes established providers of sanctions screening, PEP screening and adverse media monitoring.
Companies including LexisNexis Risk Solutions, Refinitiv World-Check and ComplyAdvantage have developed screening products used by financial institutions and other regulated organizations.
This means the commercial significance of AWM will depend not simply on its ability to automate screening, but on factors such as data quality, matching performance, integration, case-management capabilities and the number of false-positive alerts generated.
Equifax says AWM uses millions of detailed and up-to-date risk profiles and was developed with NOTO. The company’s launch announcement did not provide independent accuracy measurements or disclose a false-positive rate.
Those metrics can be important when compliance departments compare automated screening systems because a high volume of false alerts can increase the workload for analysts and potentially reduce operational efficiency.
UK and EU AML Rules Create Cross-Border Compliance Considerations
The regulatory environment is also changing beyond the UK.
The European Union’s Anti-Money Laundering Regulation, which entered into force in 2024, forms part of a broader restructuring of the EU’s AML framework. The new framework includes the establishment of the European Anti-Money Laundering Authority (AMLA) and a move toward a more harmonized single AML rulebook.
The framework is scheduled to become applicable from mid-2027.
For businesses operating across the UK and European Union, this creates a more complex compliance environment because firms may need to manage requirements arising from different jurisdictions.
Technology platforms that can integrate multiple data sources and apply configurable monitoring rules may therefore become increasingly relevant to international compliance operations. The technology itself, however, does not eliminate the need for firms to understand and implement the specific requirements applicable in each jurisdiction.
Costs, Operational Impact and False Positives
The economic impact of automated AML screening extends beyond the price of a technology platform.
Manual screening can require compliance analysts to review customer records, investigate potential matches and document decisions. Automation can reduce some of this repetitive workload by identifying potential matches and organizing cases electronically.
The main operational challenge is false-positive management.
A potential match does not necessarily indicate that a customer is sanctioned or involved in financial crime. Names can be similar, identities can overlap and information contained in different databases can vary in quality.
Compliance teams therefore still need processes for validating alerts and distinguishing genuine matches from unrelated individuals.
The ability to configure matching thresholds is intended to help firms manage this balance. The appropriate threshold will depend on factors including the institution’s risk appetite, customer population, geographic exposure and regulatory obligations.
Risks and Limitations of Automated AML Screening
Automation can improve the scale and speed of screening, but it introduces its own limitations.
Data quality
Screening results depend heavily on the accuracy, completeness and timeliness of the underlying data. An automated system cannot compensate fully for incomplete or outdated source information.
False positives
Highly sensitive matching can generate large numbers of alerts that require human investigation. Excessive alert volumes can increase compliance costs and create operational bottlenecks.
False negatives
Conversely, overly restrictive matching parameters can reduce the number of alerts while increasing the risk that relevant individuals are not identified.
Human oversight
AML screening remains a risk-management process rather than a purely technical exercise. Potential matches often require contextual investigation and documented decisions by appropriately trained personnel.
Regulatory accountability
The use of a third-party screening provider does not transfer regulatory responsibility away from the regulated business. Firms remain accountable for the effectiveness of their AML frameworks and customer-monitoring arrangements.
What Equifax’s Launch Means for AML Compliance Technology
Equifax’s AWM launch illustrates the continuing movement toward automated and continuous compliance monitoring.
Its integration with the company’s identity and fraud capabilities, combined with the NOTO data partnership, positions the service within a market where financial institutions and other regulated businesses already have multiple screening options.
The immediate question for prospective users is therefore less about whether AML screening can be automated and more about how effectively a particular system performs against existing compliance requirements.
Relevant considerations include data coverage, matching accuracy, false-positive rates, integration requirements, auditability, case-management functionality and the ability to adapt screening parameters to different risk profiles.
Future Outlook for Automated AML Monitoring
The direction of AML regulation in the UK and Europe is likely to keep compliance technology under scrutiny as regulators place greater emphasis on effective customer-risk management and financial-crime controls.
Continuous monitoring can provide regulated businesses with a mechanism for responding more quickly to changes in customer information than periodic screening alone. At the same time, increasingly sophisticated compliance systems will need to demonstrate reliable data, explainable alerts and appropriate governance.
Equifax’s launch adds another established data and financial-services technology provider to an increasingly competitive AML screening market. Its longer-term significance will depend on how the platform performs in real-world compliance environments and whether its data partnership, configurable thresholds and integration capabilities provide measurable advantages over existing systems.
Conclusion
Equifax UK’s launch of Automated AML Watchlist Monitoring reflects the wider transition from periodic customer screening toward continuous, technology-supported AML monitoring. The platform combines sanctions, PEP, RCA and adverse-media screening with API connectivity and centralized case management.
For UK-regulated businesses, automation can reduce repetitive screening activity and support the documentation of monitoring processes. However, screening technology remains one component of a broader AML framework. Data quality, false-positive management, human investigation and regulatory governance remain central to effective customer-risk monitoring.

