



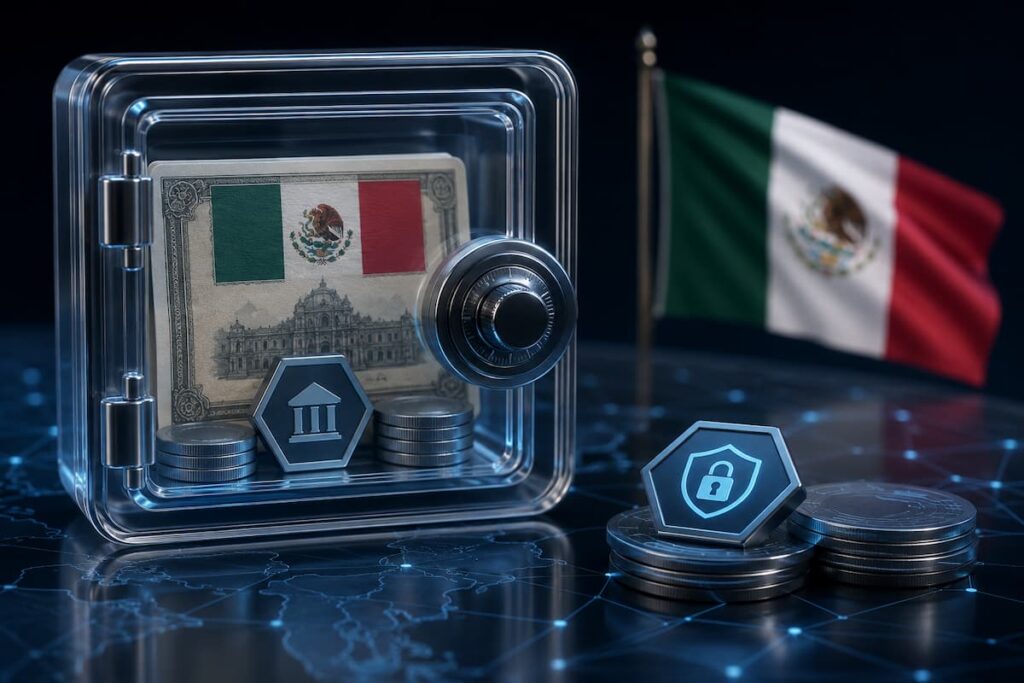
Anchorage Digital has added custody support for CETES, a tokenized version of Mexican Federal Treasury Certificates issued by Etherfuse on the Stellar network. The move extends the federally chartered crypto bank’s product range into Latin American sovereign debt custody, adding a new asset class to its suite of tokenized real-world assets held on behalf of institutional clients.
CETES are short-term instruments issued by the Mexican federal government and rank among the country’s most widely traded debt securities. The arrangement structures the offering across three distinct layers: Etherfuse tokenizes the underlying instrument under its Stablebonds framework, Stellar provides the settlement and asset-transfer network, and Anchorage Digital supplies the regulated custody infrastructure that institutional investors require before allocating to a digital asset.
The development is significant for institutional finance because it extends an established pattern in tokenized real-world assets — issuance, network, and custody as separate regulated layers — to an emerging-market sovereign debt instrument, an asset class where cross-border custody infrastructure has historically lagged that available for US Treasuries or EU government bonds.
What the CETES Tokenization Arrangement Involves
The product wraps Mexican Federal Treasury Certificates onchain through Etherfuse’s Stablebonds platform, with Stellar handling settlement and asset transfer. Anchorage Digital sits at the custody layer, providing the regulated holding infrastructure that allows institutional investors to gain exposure to the underlying sovereign debt without directly managing the operational complexity of cross-border holding.
Anchorage Digital co-founder and chief executive Nathan McCauley said tokenized real-world assets are becoming a core part of institutional digital finance, and framed the CETES custody addition as expanding the range of global assets institutions can securely hold at Anchorage Digital while reinforcing the firm’s focus on Mexico and the broader Latin American market. Etherfuse co-founder and chief executive David Taylor pointed to the access rationale underlying the product, noting that tokenization can, in principle, widen the pool of participants in established government debt markets by reducing the operational friction associated with cross-border holding.
How the Three-Layer Custody Model Works
The transaction structure reflects a recurring architecture in the tokenized real-world asset sector: issuers tokenize the underlying financial instrument, a public or permissioned blockchain provides the settlement rail, and a regulated custodian holds the resulting token on behalf of end investors. Each layer requires distinct regulatory permissions, and the custody layer is frequently the operational bottleneck, since it demands the most extensive regulatory standing among the three functions.
Anchorage Digital holds a national bank charter from the Office of the Comptroller of the Currency — the first such charter granted to a crypto-native firm in the United States — alongside licences from the Monetary Authority of Singapore and a New York BitLicense. This multi-jurisdictional regulatory footprint is relevant for CETES specifically, given that prospective buyers may be based in the US, Europe, or Asia, while the underlying instrument constitutes Mexican sovereign debt.
Key Factors Influencing Institutional Adoption
The announcement follows an earlier partnership Anchorage Digital disclosed with Grupo Salinas covering cross-border settlement, which the company has positioned as part of a sustained strategic focus on Mexico and Latin America. Tokenized government debt has drawn increasing institutional interest globally, with Franklin Templeton and BlackRock both having launched tokenized fund products in the US, and several European asset managers exploring onchain versions of sovereign debt. The CETES market is considered a plausible candidate for tokenization given the instrument’s liquidity and recognition within Mexican capital markets.
Regulatory Framework and Implications
The product sits across several overlapping regulatory frameworks. In the US, the OCC’s stance on crypto-bank activities will influence how Anchorage Digital can market custody services to registered investment advisers and fund managers. In the EU, the Markets in Crypto-Assets (MiCA) regulation does not directly govern tokenized securities, which instead fall under the Markets in Financial Instruments Directive II (MiFID II) and the EU’s Distributed Ledger Technology (DLT) Pilot Regime. This regulatory bifurcation means institutional investors evaluating CETES exposure must navigate custody-specific rules separately from securities-specific rules, depending on jurisdiction.
Risks and Limitations
Institutions considering CETES exposure will need to account for Mexican peso currency risk embedded in the underlying instrument, which the tokenization process does not remove or mitigate. Cross-border custody and settlement infrastructure for emerging-market sovereign debt also remains comparatively thin relative to that available for US Treasuries or EU government bonds, a structural gap that tokenization addresses only partially. Additionally, the ultimate commercial viability of the product depends on whether institutional demand for tokenized Mexican sovereign debt is sufficient to justify the compliance and operational overhead associated with onboarding a new asset class — a question that remains unresolved at launch.
Outlook
Stellar Development Foundation chief business officer Raja Chakravorti described the arrangement as an example of blockchain technology improving access to global markets. Whether this framing translates into sustained institutional allocation will depend on demand dynamics that have not yet been tested at scale for emerging-market sovereign debt tokenization specifically, as distinct from the more established tokenized US Treasury products already in circulation.
Conclusion
Anchorage Digital’s addition of CETES custody extends tokenized real-world asset infrastructure into Latin American sovereign debt, applying an issuance-network-custody model already established for US Treasuries to a Mexican government instrument. Currency risk, thin cross-border infrastructure for emerging-market debt, and unproven institutional demand at scale remain open questions ahead of broader market adoption.

