


Introduction
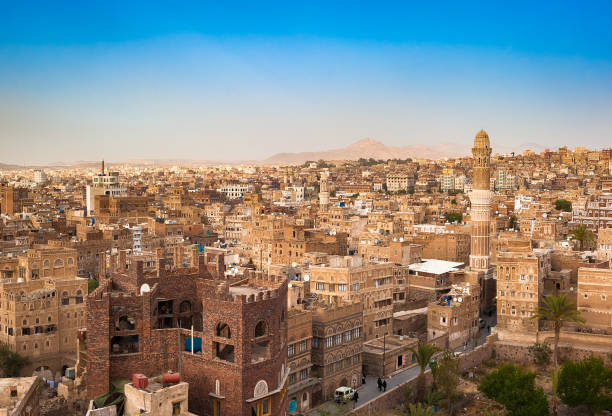
Yemen’s financial system has been reshaped by more than a decade of conflict, leaving institutions, banks, payment infrastructure and monetary conditions divided between authorities in Sana’a and Aden. The result is an economy in which access to formal financial services remains difficult and cash continues to play a central role.
At the same time, digital financial services are beginning to expand. Electronic wallets such as ONE Cash and Jawali provide transfers, payments and other services without requiring customers to maintain conventional bank accounts. A $20million World Bank-supported project is also working on payment infrastructure, including a Fast Payment System and Real Time Gross Settlement System under the Central Bank of Yemen in Aden.
For Yemen, the significance of fintech is therefore less about the rapid expansion of consumer technology and more about whether digital financial infrastructure can improve access, payments and the movement of money in an economy fragmented by conflict.
What Is Yemen’s Fintech and Digital Payments Market?
Yemen’s fintech market operates within an unusually fragmented financial environment.
The country’s conflict has produced separate institutional and monetary systems in areas controlled by different authorities. The World Bank has described Yemen as increasingly divided into two economic zones, with separate institutions, monetary authorities and exchange-rate conditions.
This distinction matters for digital finance because payment services generally depend on common infrastructure, regulatory standards and interoperability between financial institutions.
A fintech company operating in such an environment faces challenges that extend beyond software development. Its ability to provide nationwide services can depend on telecommunications infrastructure, banking relationships, payment systems, identification mechanisms and the regulatory environment in each area.
The result is a digital-finance market where infrastructure and institutional coordination are as important as the technology itself.
How Digital Payments Work in Yemen
Digital financial services are developing through two principal channels: electronic wallets and payment infrastructure.
Electronic wallets
Services such as ONE Cash allow customers to hold and transfer Yemeni rials, Saudi riyals and US dollars, according to the company. The platform also supports payments and bill-related services.
Jawali, operated by WeCash, provides another wallet-based model. Its services include sending and receiving money, salary and aid payments, purchases and payments for services such as telecommunications and internet access.
The significance of these systems is partly related to Yemen’s limited conventional banking infrastructure. Mobile wallets can use agent networks and digital channels to provide financial services without requiring every customer to have convenient access to a bank branch.
National payment infrastructure
At the infrastructure level, the World Bank’s Yemen Financial Market Infrastructure and Inclusion Project is supporting the development of a Fast Payment System and Real Time Gross Settlement System through the Central Bank of Yemen in Aden.
The programme is being implemented by the United Nations Development Programme (UNDP).
The project is also intended to improve interoperability among financial institutions and support greater digitisation of government payments, remittances and cash transfers.
Why Remittances Are Central to Yemen’s Fintech Economy
Remittances occupy an important position in Yemen’s financial system because many households depend on money sent by Yemenis working outside the country, particularly in Gulf states.
This creates a direct connection between international migration and domestic financial infrastructure.
Traditional remittance systems often involve cash collection or physical financial-service networks. Digital payment systems can create additional channels for receiving and distributing funds, provided recipients have access to telecommunications, agents, identification and functioning payment infrastructure.
The World Bank-backed financial infrastructure project specifically identifies remittances as one area where digitisation could have an impact.
For households receiving money from relatives abroad, the practical question is therefore not simply whether digital payments exist. It is whether those systems can operate reliably across fragmented financial institutions and reach recipients outside major urban centres.
Financial Inclusion Remains a Major Constraint
Yemen entered the conflict with significant financial-inclusion challenges, and years of economic disruption have made access to formal financial services more difficult.
Digital wallets can address some physical barriers because they do not depend entirely on conventional branch networks. This can be particularly relevant in rural communities and areas where banking infrastructure has been damaged or disrupted.
However, digital financial inclusion depends on infrastructure beyond financial technology.
Telecommunications and electricity
Digital payments require functioning communications networks and access to electricity or devices capable of supporting transactions. Disruptions in either can limit the usefulness of electronic financial services.
Agent networks
Where conventional branches are scarce, agents can serve as an important connection between digital accounts and physical cash. Their availability and reliability therefore influence how effectively mobile wallets can operate.
Identification and compliance
Formal financial services also require mechanisms for identifying customers and meeting regulatory and compliance requirements. Fragmented institutions can make these processes more complicated.
Fintech can reduce some barriers to financial access, but it cannot independently resolve the physical and institutional constraints surrounding Yemen’s economy.
The Main Challenge Is Financial Fragmentation
The most significant obstacle to a unified digital payments market is the country’s institutional division.
Financial institutions have faced competing regulatory demands, while banks have also dealt with sanctions-related concerns and operational pressures. Some financial institutions have moved activities from Sana’a toward Aden, adding another layer of complexity to the banking system.
The development of payment infrastructure through the Central Bank in Aden is an important institutional development, but the existence of separate financial structures in Houthi-controlled areas creates challenges for nationwide interoperability.
This means Yemen cannot necessarily follow the same fintech development path as countries with unified financial regulators and nationwide payment infrastructure.
A mobile application can provide a transaction interface, but the underlying payment rails still need to connect institutions.
Costs and Economic Implications of Digital Finance
The economic implications of digital payments extend beyond transaction convenience.
For government agencies and humanitarian organisations, digitised transfers can potentially reduce reliance on physical cash distribution. For financial institutions, interoperable payment infrastructure can simplify transfers between participating institutions.
For households, digital wallets can provide an alternative mechanism for receiving money, paying bills and transferring funds.
However, the economic benefits depend on reliability and coverage. A digital payment system that cannot operate consistently across regions, institutions or telecommunications networks cannot fully replace cash-based transactions.
The cost of developing and maintaining digital infrastructure is another consideration. Fast-payment systems require technical systems, security controls, institutional coordination and ongoing maintenance.
In Yemen’s case, these investments are taking place while the wider economy remains under severe pressure.
Risks and Limitations for Yemen’s Fintech Sector
Digital finance does not eliminate the risks created by Yemen’s broader economic and political conditions.
Regulatory fragmentation
Different authorities and financial institutions can operate under different regulatory conditions. This can limit the ability of fintech providers to develop truly nationwide products.
Currency fragmentation
Different exchange-rate conditions and monetary arrangements complicate transactions and financial reporting.
Infrastructure disruption
Conflict can affect electricity, telecommunications, banking branches, payment agents and other physical infrastructure required to support digital services.
Cybersecurity and operational risks
As financial activity becomes more digital, systems must also manage cybersecurity, fraud and operational-continuity risks.
Limited interoperability
The usefulness of a payment network increases when users can transact across institutions. Fragmentation can reduce that interoperability and leave digital services operating within separate financial ecosystems.
What the World Bank-Supported Infrastructure Could Change
The $20million Yemen Financial Market Infrastructure and Inclusion Project represents an effort to address some of the structural limitations affecting Yemen’s financial system.
Its focus on a Fast Payment System and Real Time Gross Settlement System is significant because these systems form part of the basic infrastructure required for modern banking and payments.
A Fast Payment System is designed to enable rapid electronic transfers between participating institutions. A Real Time Gross Settlement System, meanwhile, provides infrastructure for settling financial transactions between institutions on a transaction-by-transaction basis.
The project also targets interoperability, digital government payments, remittances and cash transfers.
The significance is therefore broader than introducing another consumer payment application. It concerns the underlying financial infrastructure needed for banks and other providers to exchange and settle payments.
Future Outlook for Yemen’s Fintech Sector
Yemen’s fintech development is likely to remain closely tied to the country’s wider economic and institutional conditions.
Electronic wallets already demonstrate that digital financial services can operate in a difficult environment. Meanwhile, investment in payment infrastructure indicates an effort to establish more modern financial rails.
But technology alone cannot resolve institutional fragmentation caused by conflict.
The future development of Yemen’s digital financial sector will depend on several factors, including the stability of financial institutions, telecommunications access, payment-system interoperability, regulatory coordination and the continued availability of international and development assistance.
If those foundations improve, digital payments could become more important in remittances, government transfers, banking and everyday transactions. If fragmentation persists, digital financial services may continue developing as separate systems rather than forming one integrated national payments market.
Conclusion
Yemen’s fintech sector is developing under conditions that differ sharply from those in more stable Middle Eastern economies. The country’s financial system remains divided, cash is still important and access to conventional banking services is uneven.
Electronic wallets such as ONE Cash and Jawali provide examples of how digital services can extend financial access beyond traditional bank branches. At the infrastructure level, the $20million World Bank-supported project for fast payments and settlement systems represents an effort to strengthen the financial rails beneath those services.
The central issue is therefore not whether Yemen can build financial technology. It already has. The larger question is whether digital payment networks can achieve sufficient interoperability and reliability across an economy divided by conflict. That outcome will depend as much on institutional and economic conditions as on the technology itself.

