
Introduction
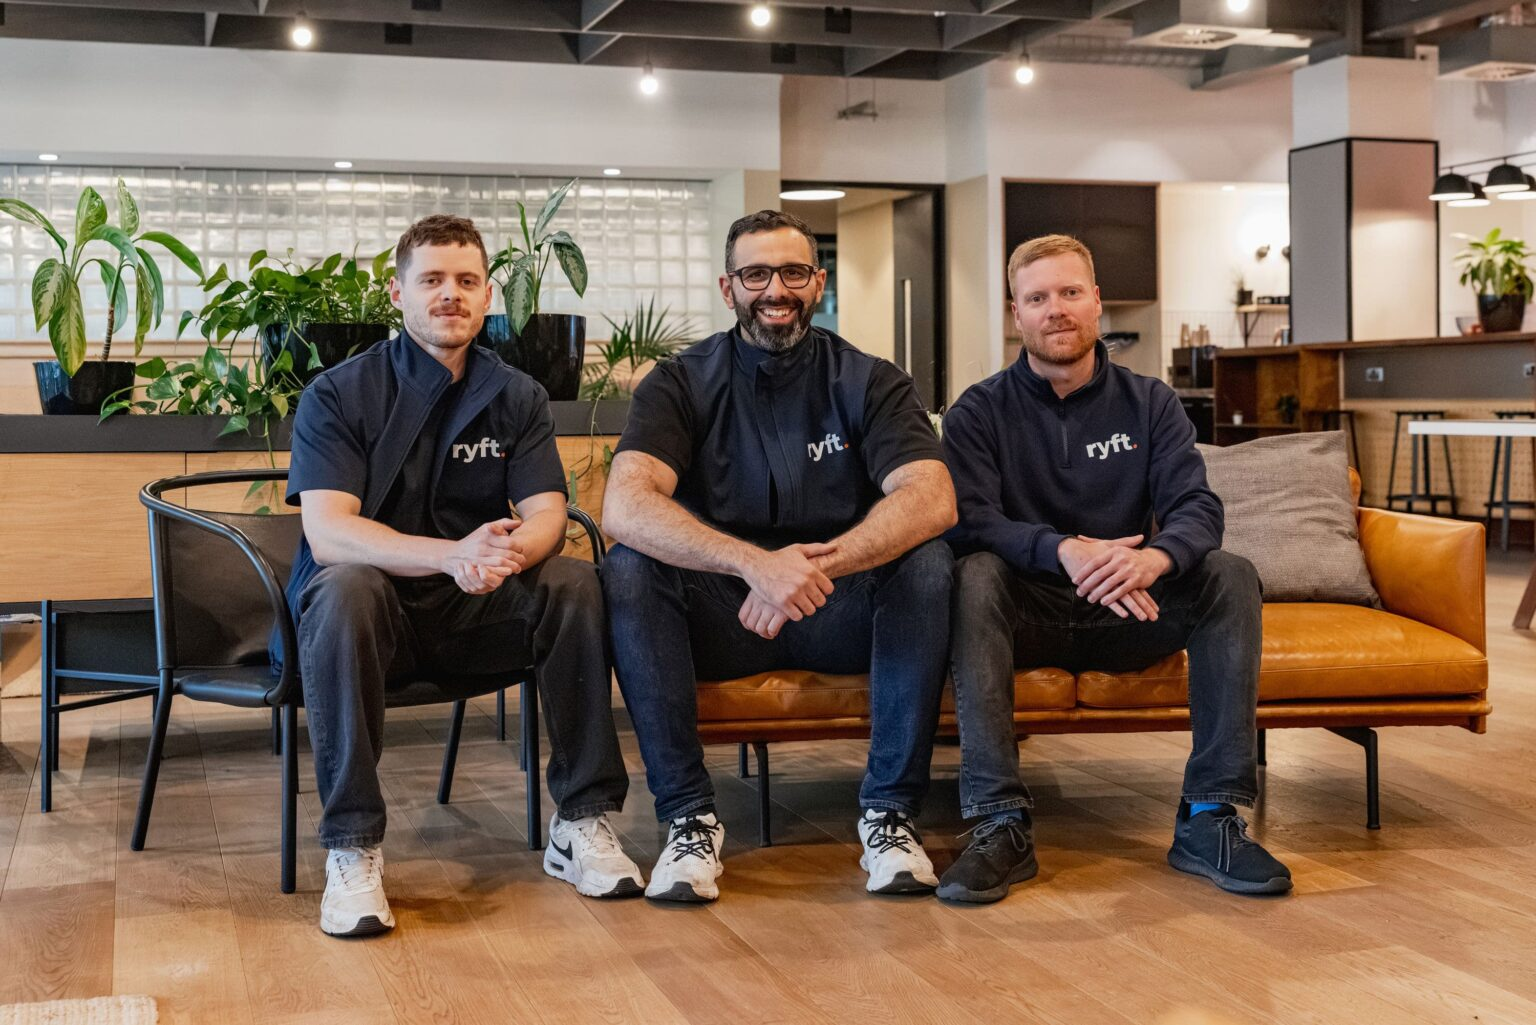
Manchester-based payments infrastructure company Ryft has raised £20 million in Series B funding, giving the company additional capital to expand its multi-party payments platform across Europe and the United States. The round was led by Gresham House Ventures, with participation from existing investors Pembroke VCT and Ingenii Capital, as well as new backing linked to the Northern Powerhouse Investment Fund II.
The financing brings Ryft’s total capital raised to approximately £27 million, according to the company. Ryft said its processing volume has tripled over the past 12 months and that more than 6,500 businesses now use its platform. The company plans to direct the new capital toward international expansion, product development and larger enterprise customers.
The fundraising comes as payment infrastructure increasingly needs to support marketplaces and other platforms where a single transaction can involve multiple sellers, service providers or recipients. Ryft’s expansion strategy also includes an application for a full European Union payments licence through the Malta Financial Services Authority (MFSA).
What Ryft’s Multi-Party Payment Infrastructure Does
Ryft was founded in 2021 by Sadra Hosseini, Alex Mackenzie and Richard Kirby. The company develops payment infrastructure for marketplaces, software platforms and multi-location businesses.
Traditional card and payment systems can be relatively straightforward when money moves between one customer and one merchant. Platform businesses can require a more complicated structure. A single customer payment may need to be allocated between several parties, followed by separate payouts and reconciliation.
Ryft’s platform is designed around these multi-party transactions. Its infrastructure can support:
- Seller and merchant onboarding
- Payment splitting between multiple parties
- Recurring billing
- Cross-border payouts
- Payment processing through a single integration
- Transaction-based monetisation for platforms
The company operates within a UK regulatory framework and says its processing volume has tripled during the past year. More than 6,500 businesses are reported to be using its payment system.
How Multi-Party Payments Work
Multi-party payments are particularly relevant to platforms that do not simply sell their own products.
Consider an online marketplace where a customer pays for products supplied by several independent sellers. The platform needs to accept the customer’s payment, determine how much belongs to each seller, account for fees and then distribute the relevant amounts.
A similar structure can appear in franchise networks, software platforms, creator marketplaces and other businesses where multiple participants share transaction revenue.
Payment splitting
Payment splitting is the process of allocating a transaction between defined recipients. The rules can be based on factors such as the seller, product, platform fee or contractual arrangement.
Seller onboarding
Platforms also need to establish the identity and eligibility of businesses receiving payments. This can involve customer due diligence and other compliance processes.
Payouts
After a transaction has been processed, funds may need to be distributed to several recipients. Cross-border activity can introduce additional considerations involving currencies, payment networks and regulatory requirements.
These functions make payment infrastructure an operational component of the platform rather than simply a checkout feature.
Why Ryft Is Expanding Into Europe
Ryft’s European expansion is tied to a regulatory application in Malta.
The company has applied for a full EU payments licence from the Malta Financial Services Authority. If authorised, the licence is intended to support the company’s ability to provide relevant payment services across the European Economic Area (EEA) through the applicable passporting framework.
The application is significant because Ryft is currently a UK-based payments company. Following the UK’s departure from the European Union, UK-based financial services businesses cannot simply rely on their UK regulatory authorisation to provide regulated services throughout the EEA.
The proposed Maltese structure would give Ryft an EU regulatory base from which it could pursue expansion in European markets, subject to authorisation and the applicable regulatory requirements.
No approval date for the application was disclosed in the sources reviewed.
How the £20 Million Funding Will Be Used
Ryft has said the £20 million Series B will support three broad areas of development.
European expansion
The company intends to increase its presence in European markets, with the Malta licence application forming part of that strategy.
US expansion
The funding will also support expansion into the United States. The company has not publicly disclosed a detailed market-by-market timetable for that expansion.
Product and enterprise development
Ryft plans to continue developing its payment infrastructure while increasing adoption among larger and higher-growth businesses.
The company’s reported processing growth provides one measure of expansion. However, gross processing volume is not the same as revenue or profit, and Ryft has not publicly disclosed all of the financial metrics that would be needed to assess those areas.
That distinction is important when evaluating growth in payment infrastructure businesses.
Investors and Funding Structure
Gresham House Ventures led the Series B. Existing investors Pembroke VCT and Ingenii Capital also participated, while the Northern Powerhouse Investment Fund II provided new backing through PXN Equity Finance.
The round follows earlier financing as Ryft developed its payments platform. The company has not disclosed a valuation for the Series B, according to reporting on the transaction.
Pembroke’s participation also marks continued support from an existing investor. The company said this was its third investment in Ryft and its largest investment in the business to date.
The funding provides Ryft with additional resources for international expansion without requiring the company to rely solely on operating cash flow for that growth.
Partnerships With Global Payment Networks
Ryft has established partnerships involving major payments companies and card networks, including Global Payments, Visa, Mastercard, American Express and Nuvei, according to company information.
These relationships are relevant to the infrastructure model because a payment technology company can combine its own software layer with established payment networks and processing capabilities.
The arrangement illustrates an important feature of modern payment infrastructure: companies do not necessarily need to operate every layer of the payments stack themselves.
Instead, technology companies can build specialised software for a particular problem while connecting to established acquiring, card and payment infrastructure.
Risks and Limitations of International Expansion
Ryft’s growth strategy also involves regulatory and operational challenges.
Regulatory authorisation
The Malta application remains an application until the relevant authorisation is granted. European expansion therefore depends partly on the outcome and conditions of that regulatory process.
Different market requirements
Payment businesses operating across jurisdictions must account for differences in licensing, consumer protection, financial-crime controls, data requirements and payment-market structures.
Competition
The multi-party payments market includes established global payment providers as well as specialist platform-payment companies. Ryft’s expansion therefore places it in a market where technology, regulatory coverage, pricing, reliability and customer relationships can all influence adoption.
Processing volume versus financial performance
The company’s reported tripling of processing volume demonstrates increased transaction activity, but it does not by itself establish equivalent growth in revenue, margins or profitability.
This distinction is particularly relevant for payment companies because transaction volume can rise while the economics of each transaction vary.
AI Agents and the Changing Payments Architecture
The development of AI-enabled commerce is another area being discussed by investors in the payments sector.
Digital platforms increasingly automate parts of purchasing, booking and service delivery. In future commercial models, software agents could initiate transactions on behalf of businesses or consumers.
Such transactions could create additional requirements around authentication, authorisation, merchant identification and payment allocation.
Ryft investors have linked the company’s multi-party architecture to this broader shift, arguing that payment systems originally designed around relatively simple buyer-to-merchant transactions may need to accommodate more complex platform relationships.
However, the commercial scale and regulatory treatment of agent-initiated payments remain areas of development. The expansion of AI in commerce does not automatically translate into immediate changes in payment volumes.
Future Outlook for Ryft and Multi-Party Payments
Ryft’s next phase will combine international market expansion with regulatory development.
The £20 million Series B provides additional capital for the company to expand in Europe and the US, while its application to the Malta Financial Services Authority is intended to establish an EU regulatory base.
The wider market is also evolving as marketplaces, software platforms and other businesses require payment infrastructure capable of supporting multiple recipients, recurring transactions and cross-border settlement.
For payment infrastructure providers, the key operational challenge is balancing this complexity with regulatory compliance, transaction reliability and commercially sustainable economics.
Ryft’s reported growth provides evidence of increased adoption of its platform, but its longer-term international performance will depend on factors including regulatory authorisation, customer acquisition, payment volumes, competition and the economics of cross-border expansion.
Conclusion
Ryft has raised £20 million in Series B funding as it prepares to expand its multi-party payment infrastructure across Europe and the United States. The financing, led by Gresham House Ventures, takes the company’s reported total capital raised to approximately £27 million.
The Manchester-based company says its processing volume has tripled over the past 12 months, with more than 6,500 businesses using its platform. Its infrastructure is designed to support payment splitting, seller onboarding, recurring billing and cross-border payouts for marketplaces and other platform businesses.
European expansion is closely linked to Ryft’s application for a full EU payments licence with the Malta Financial Services Authority. If authorised, the structure would provide a regulatory basis for expansion across the EEA under the applicable passporting framework.
The transaction highlights a broader development in payments: platforms increasingly require infrastructure that can manage transactions involving multiple commercial parties rather than a simple buyer-and-merchant relationship. Ryft’s next stage will depend on how effectively it converts its UK operating base and new funding into regulated international growth.

