


Introduction
Travel insurance can provide financial protection against certain trip cancellations, delays, medical emergencies, baggage problems and other covered disruptions. Its relevance can increase when travelers have significant non-refundable expenses or are traveling internationally, where medical treatment and emergency evacuation can create substantial costs.
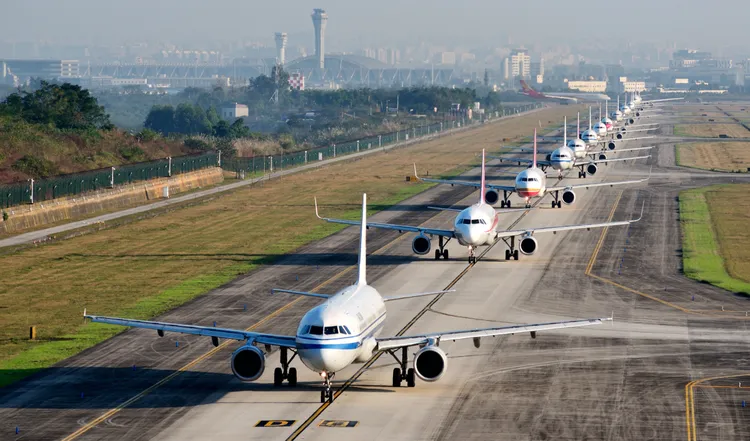
The source material identifies several factors that could contribute to travel disruptions in 2025, including air-traffic-controller shortages, above-normal hurricane activity in the Atlantic and aging airport infrastructure. Radio outages at Newark airport were cited as an example of infrastructure problems contributing to widespread delays.
Travel insurance does not cover every disruption, however. Coverage depends on the policy’s terms, exclusions, limits and claim requirements. Travelers therefore need to evaluate the risks associated with their particular itinerary rather than assuming every cancellation or delay will qualify for reimbursement.
What Is Travel Insurance?
Travel insurance is a type of insurance designed to protect travelers against specified financial losses and emergencies occurring before or during a covered trip.
Depending on the policy, coverage can include:
- Trip cancellation
- Trip interruption
- Covered travel delays
- Emergency medical expenses
- Baggage loss or theft
- Emergency assistance
- Rental-car-related coverage
- Accidental death and dismemberment
Policies differ considerably in what they cover and the limits that apply. A standard policy may also contain exclusions for pre-existing medical conditions, high-risk activities, war, unlawful events and certain named storms.
Travel insurance is therefore best understood as contractual protection against defined risks rather than comprehensive coverage for every travel problem.
How Travel Insurance Works
A traveler purchases a policy covering a specified trip or period. If a covered event occurs, the policy may reimburse eligible expenses or provide specified assistance, subject to deductibles, limits, exclusions and documentation requirements.
For example, a covered illness could potentially trigger trip cancellation or interruption benefits. A covered travel delay could result in reimbursement for eligible additional expenses, depending on the policy.
Medical coverage operates differently from trip cancellation coverage. A traveler who becomes ill or injured abroad may have access to emergency medical benefits under a travel policy, but the amount and circumstances of coverage depend on the contract.
Some policies also offer Cancel For Any Reason (CFAR) coverage as an optional add-on. CFAR can broaden cancellation protection beyond the reasons covered by a standard policy, although it remains subject to its own conditions and limitations.
When Should You Buy Travel Insurance?
The source recommends considering travel insurance as soon as a trip is booked, particularly when the trip involves significant non-refundable expenses.
Some insurers require policies to be purchased in advance, while a limited number may allow coverage to be purchased as late as the day before departure, generally with more restricted benefits.
The source suggests considering:
- 14 to 21 days in advance for international travel where full benefits are sought
- Immediately after booking a non-refundable domestic trip
- Immediately after booking an adventure trip
- At least 24 hours before departure for a last-minute trip
These are timing guidelines from the source material rather than universal requirements. Individual insurers can impose different eligibility windows and conditions.
Domestic vs. International Travel
Travel insurance may have different value depending on the nature and cost of a trip.
For a relatively inexpensive domestic trip with fully refundable reservations, purchasing a policy may provide less financial protection because there is less non-refundable expenditure at risk.
The source identifies several situations in which coverage can be more relevant:
- Non-refundable hotel or Airbnb reservations
- Concert and event tickets
- Significant prepaid travel expenses
- Medical emergencies away from home
- International travel
The source cites travel agent Shaikh Ahmed, who said travel insurance becomes particularly relevant for trips costing $1,000 and over and noted that emergency medical treatment or evacuation abroad can exceed $10,000.
International travelers can face additional exposure because domestic health insurance may not provide the same coverage outside the country. Emergency transportation can also create substantial expenses.
What Does Travel Insurance Cover?
Trip Cancellations and Interruptions
Travel insurance can reimburse eligible non-refundable expenses when a trip is canceled or interrupted for a reason specifically covered by the policy.
Covered reasons vary between contracts. A general desire to cancel a trip is typically different from a cancellation caused by a qualifying event.
Travel Delays
Travel delays can create additional expenses, including accommodation, meals and transportation.
The source cites staffing shortages, weather disruptions and broader travel congestion as factors contributing to delays. It also states that over 20% of U.S. domestic flights were delayed in 2024, according to the source material.
Even a relatively short delay can have wider consequences when it causes a missed connection, lost accommodation reservation or disruption to a scheduled tour.
Emergency Medical Coverage
Travel insurance can provide emergency medical benefits for covered illnesses or injuries during a trip.
This can be particularly relevant internationally because a traveler’s existing health insurance may not provide equivalent coverage abroad.
The source cites a recommendation from Shaikh Ahmed of at least $50,000 in emergency medical coverage for travelers, and at least $100,000 for international trips together with evacuation services. These are his recommendations, not universal industry requirements.
Baggage Protection
Depending on the policy, travel insurance may reimburse eligible losses involving baggage or personal belongings that are lost or stolen.
Coverage limits and exclusions apply, and travelers may need documentation to support a claim.
Additional Benefits
Some policies offer optional benefits for rental-car problems, accidental death and dismemberment, emergency assistance and other travel-related risks.
The availability and price of these benefits vary by insurer.
How Much Does Travel Insurance Cost?
The source estimates that travel insurance can cost approximately 4% to 10% of the total trip price, before considering the cost of optional add-ons.
For a $3,000 trip, that range would translate to approximately $120 to $300.
The final premium can depend on several factors, including:
- Total trip cost
- Trip duration
- Traveler’s age
- Policy type
- Coverage selected
- Additional riders or benefits
More expensive trips generally produce higher premiums because the insurer has greater potential financial exposure.
Single-Trip vs. Multi-Trip Coverage
Travelers generally can choose between coverage for one specific trip and policies designed for multiple trips.
A single-trip policy covers one defined journey.
A multi-trip policy can provide coverage for multiple journeys during a specified period, commonly a year. This structure can be relevant to frequent travelers, although the applicable benefits and limits depend on the policy.
Basic vs. Comprehensive Travel Insurance
Travel insurance policies can also differ in the breadth of coverage.
Basic coverage generally provides a more limited set of benefits and may have lower premiums.
Comprehensive coverage generally includes a broader range of benefits and can cost more.
The appropriate comparison is therefore not simply the premium. Travelers need to examine what risks are covered, the maximum benefit amounts, exclusions and conditions for making claims.
How to Buy Travel Insurance
The process begins by identifying the financial and medical risks associated with the trip.
Important questions include:
- Is the trip refundable?
- How much money has been prepaid?
- Is emergency medical coverage required?
- Will the traveler be outside their home country?
- Is baggage protection necessary?
- Are adventure activities included?
- Does existing health insurance provide coverage at the destination?
Travelers can then compare quotes from specialized travel insurers and existing insurance companies.
Other potential sources of coverage include:
- Credit card issuers
- Airlines
- Travel companies
- Travel agents
- Existing home, auto or health insurers
Credit card travel benefits can vary significantly, so travelers should review the actual terms rather than assuming a booking automatically provides comprehensive insurance.
Key Risks and Limitations
Policy Exclusions
Travel insurance policies can exclude pre-existing medical conditions, high-risk activities, war, unlawful events and certain named storms.
The presence of an exclusion does not necessarily mean that all travel-related claims are denied. It means that claims falling within the specific exclusion may not qualify for coverage.
Claim Deadlines
Policies can impose deadlines for notifying insurers and submitting claims.
Missing a required deadline can affect eligibility for reimbursement.
Documentation Requirements
Travelers may need to provide documentation supporting a claim. Depending on the circumstances, this can include receipts, medical records, proof of delay or cancellation and other evidence required under the policy.
Existing Insurance May Overlap
A traveler may already have some form of protection through health insurance, a credit card or another insurance policy.
Understanding these overlapping benefits can help distinguish between primary and secondary coverage and identify potential gaps.
Travel Advisories and Other Events
Coverage can also be affected by the circumstances surrounding an event, including government advisories and other exclusions contained in the policy.
Travelers should review these provisions before purchasing coverage, particularly when visiting destinations affected by elevated risks.
Travel Insurance and Global Mobility
Travel insurance has broader relevance for international mobility because medical systems, emergency transportation costs and insurance arrangements differ between countries.
Business travelers, international students, expatriates and people taking extended overseas trips may face different risks from those associated with a short domestic vacation.
Emergency evacuation can be particularly significant when appropriate medical facilities are not readily accessible. A policy that includes evacuation benefits can therefore provide a different level of protection from one focused primarily on trip cancellation or baggage.
For international travel, travelers should also determine whether their existing health insurance applies in the destination country and whether the travel policy’s medical coverage is subject to specific exclusions or limits.
Future Outlook for Travel Insurance
Travel insurance demand is closely linked to travel volumes, trip costs and perceptions of disruption risk.
The source indicates that travel demand was expected to remain strong, supported by higher household travel budgets, an increase in people working while traveling and stronger consumer confidence.
At the same time, staffing shortages, extreme weather, airport infrastructure problems and broader travel congestion can create operational disruptions.
These conditions make policy design and exclusions increasingly important to travelers. However, a higher perceived risk of disruption does not mean every disruption will qualify for reimbursement. The contractual definition of a covered event remains central to any claim.
Conclusion
Travel insurance can provide financial protection against specified cancellations, interruptions, delays, medical emergencies and baggage problems, but its value depends on the cost and characteristics of the trip and the terms of the policy.
The source estimates that travelers can expect to pay approximately 4% to 10% of their trip cost for travel insurance, before optional add-ons. For a $3,000 trip, that represents approximately $120 to $300.
Coverage can be particularly relevant when travelers have substantial non-refundable expenses or are traveling internationally. However, exclusions, coverage limits, claim deadlines and documentation requirements can materially affect whether an insurer pays a claim.
The key consideration is therefore not simply the price of a travel insurance policy, but the specific risks it covers and the circumstances under which those benefits become available.

