


Introduction
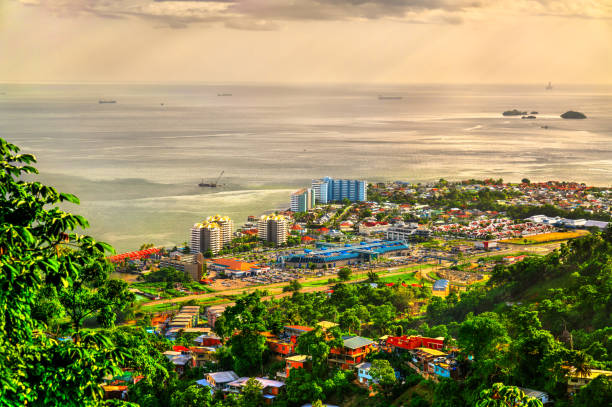
Trinidad and Tobago is entering a new phase of financial-sector modernisation. The country already has a comparatively developed banking system, relatively high incomes and a financial sector that includes commercial banks, credit unions, insurers and investment firms. The challenge is no longer simply expanding access to formal financial services.
Instead, the focus is increasingly on how people and businesses use those services.
The country’s 2023 National Financial Inclusion Survey found that 75% of people were formally financially included, while 91% of financially included respondents had a commercial bank savings account. Yet only 24% had a mobile application connected to their financial account, and 21% used online banking through a website.
In 2026, Trinidad and Tobago is seeking to accelerate digital payments through new infrastructure modelled on India’s Unified Payments Interface (UPI), alongside the expansion of electronic-money issuers and domestic fintech companies. The development comes as the economy continues to balance its dependence on energy exports with efforts to strengthen non-energy activity.
Trinidad and Tobago’s Financial System Is Already Highly Developed
Trinidad and Tobago, with a population of around 1.4 million, has one of the more established financial systems in the Caribbean.
Major financial institutions include Republic Financial Holdings, First Citizens, Scotiabank and RBC Royal Bank, alongside credit unions, insurers and investment companies.
Port of Spain has also developed a role as a regional financial centre.
This structure means the country’s fintech challenge differs from that of markets where large portions of the population remain outside formal banking.
The central issue is digital adoption within an existing financial system.
Banking Access Versus Digital Usage
The 2023 financial inclusion survey illustrates the distinction.
Three-quarters of respondents were formally financially included, while debit-card ownership was also widespread. Among people with financial accounts, 88% had a debit card linked to their account.
Mobile and online banking adoption, however, remained substantially lower.
Only 24% had a mobile application linked to their financial account, while 21% had access to online banking through a website.
Among people without a banking application, more than half said they did not know how to use one. Lack of trust was another cited obstacle.
The figures suggest that increasing digital-payment adoption requires more than simply providing financial accounts or payment cards. It also requires users to understand, trust and regularly use digital financial services.
Economic Diversification Is Part of the Payments Story
Trinidad and Tobago’s economic structure makes its financial-technology development particularly significant.
Unlike Caribbean economies heavily dependent on tourism, Trinidad and Tobago has built substantial economic activity around oil, natural gas and petrochemicals.
Manufacturing, financial services, trade and professional services provide additional sources of economic activity, while Tobago has a stronger tourism component.
Energy remains an important source of national income but also exposes the economy to changes in production and commodity conditions.
IMF Outlook
The International Monetary Fund expects real GDP to grow by approximately 0.8% in 2026, following similar growth in the previous year.
The IMF expects the non-energy economy to expand by 2.6%, while energy output is projected to contract by 4.5%.
Nominal GDP is projected at approximately TT$181.3 billion, equivalent to about $26.7 billion at the prevailing exchange rate cited in the source material.
New energy projects could support future growth, but stronger non-energy activity remains important to diversification.
Digital financial infrastructure is one component of that broader transition.
Trinidad and Tobago Is Adopting a UPI-Style Payments Model
One of the country’s most significant fintech developments is its partnership with NPCI International Payments Limited to develop an instant-payments platform based on India’s UPI model.
UPI has become a major component of India’s digital-payment infrastructure, enabling account-to-account transactions through an interoperable system.
Trinidad and Tobago is attempting to adapt a similar approach to a much smaller market.
How the New Payments Infrastructure Is Intended to Work
The proposed platform is designed to support several transaction types, including:
- Government-to-person payments
- Peer-to-peer transfers
- Peer-to-merchant payments
- 24/7 real-time settlement
The objective is to create digital payment rails that can connect participants across the financial ecosystem rather than requiring every transaction to remain within an individual bank or payment provider’s system.
That could reduce dependence on cash and potentially broaden the use of electronic payments.
Why Interoperability Matters
A fragmented payments market can make digital transactions more difficult when consumers and businesses use different banks or payment providers.
Interoperable infrastructure addresses part of that problem by creating common rails through which participating institutions can process transactions.
For a relatively small economy, interoperability can be particularly important. A system that allows consumers to move money between different institutions without requiring complicated processes could increase the usefulness of digital payments.
The success of the model will ultimately depend on adoption, participating institutions, reliability, pricing, consumer trust and the regulatory framework surrounding the infrastructure.
Domestic Fintech Companies Are Expanding the Market
The development of national payment infrastructure is taking place alongside an existing domestic fintech ecosystem.
WiPay
WiPay is a Caribbean payments company that has developed electronic-payment infrastructure for businesses and consumers.
Its presence illustrates that digital-payment activity in Trinidad and Tobago predates the country’s adoption of a UPI-inspired national infrastructure model.
PayWise
PayWise is a Central Bank-registered electronic-money issuer.
Its platform allows users to send and receive payments, pay bills and fund wallets using cards or cash through agents.
These services provide alternatives to traditional banking channels and can help introduce additional digital-payment options into the market.
Growth in Electronic-Money and Payment Providers
The Central Bank reported granting two additional electronic-money issuer licences during its 2025 financial year.
It also reported 11 payment service providers under its supervision by September 2025.
The expansion indicates that fintech activity is increasingly being incorporated into the regulated financial system rather than operating exclusively alongside traditional financial institutions.
Regulation Will Shape the Payments Transition
A larger digital-payment ecosystem requires regulatory oversight capable of addressing financial crime, consumer protection, operational resilience and payment-system risks.
Electronic-money issuers and payment service providers in Trinidad and Tobago operate under Central Bank supervision.
The Central Bank has also been implementing risk-based supervision for payment providers and electronic-money issuers while pursuing broader payment-system reforms.
Trust Is a Critical Adoption Factor
Regulation has an economic function beyond controlling financial risk.
The country’s financial inclusion data indicates that trust is one of the factors influencing digital adoption. Consumers are less likely to move everyday transactions onto digital platforms if they are uncertain about security, reliability or how their money will be protected.
A regulated fintech environment can therefore help establish confidence, although regulation alone cannot guarantee adoption.
Providers must also demonstrate reliable technology, transparent pricing, effective customer support and appropriate security controls.
Foreign-Exchange Constraints Remain a Separate Challenge
Digital payments can make domestic transactions faster, but they cannot resolve structural foreign-exchange shortages.
The IMF has continued to identify foreign-exchange availability as an economic constraint for Trinidad and Tobago, while international reserves have gradually declined.
This has implications for businesses that depend on overseas suppliers.
Companies importing merchandise, purchasing international software services or paying foreign vendors still require access to foreign currency regardless of how efficiently domestic payments operate.
Digital Payments Cannot Replace Foreign Currency
This distinction is important when assessing the economic impact of fintech.
A modern instant-payment system can reduce transaction friction within the domestic economy. It cannot by itself increase the supply of U.S. dollars or eliminate balance-of-payments pressures.
Consequently, payments reform needs to be considered alongside broader monetary, fiscal, trade and foreign-exchange conditions.
What the Payments Revolution Could Mean for Businesses
For businesses, more interoperable real-time payments could change how customers pay and how companies manage receivables.
Potential operational benefits include faster settlement, fewer cash-handling requirements and greater integration between merchants and financial-service providers.
Government agencies could also use digital payment infrastructure to distribute funds more efficiently through government-to-person transactions.
However, the economic impact will depend on actual adoption rather than infrastructure deployment alone.
A payments platform can provide the rails, but consumers and businesses still need reasons to use them.
Risks and Limitations
Trinidad and Tobago’s digital-payments transition faces several constraints.
Adoption Risk
Low digital usage among financially included consumers suggests that access to technology does not automatically translate into adoption.
Knowledge, trust and familiarity will influence how quickly consumers move away from cash.
Cybersecurity and Operational Risk
As more transactions move through digital channels, payment providers become increasingly dependent on technology infrastructure.
System outages, cyberattacks, fraud and data-security incidents can undermine confidence in digital payments.
Regulatory Complexity
The expansion of payment providers requires regulators to maintain oversight as new business models and technologies enter the market.
Rules must support innovation while addressing consumer protection, financial crime and systemic risks.
Foreign-Exchange Constraints
Domestic payment modernisation does not eliminate the need for foreign currency.
Businesses involved in international trade can therefore continue to face constraints even if domestic payments become faster and more efficient.
Future Outlook for Trinidad and Tobago’s Fintech Sector
The country’s payments market is moving from a traditional bank-led model toward a more diverse ecosystem involving banks, electronic-money issuers, payment service providers and fintech companies.
The introduction of UPI-inspired infrastructure could become a major milestone if it achieves widespread interoperability and consumer adoption.
The broader significance extends beyond payments.
A more efficient digital financial system could support commerce, government disbursements and financial-service innovation while reducing some of the practical dependence on cash.
But the transformation is unlikely to happen through technology alone. Consumer education, trust, regulation, cybersecurity and economic conditions will determine how extensively the new infrastructure is used.
Conclusion
Trinidad and Tobago enters 2026 with a financial system that already provides broad formal access to banking services. Its next challenge is converting that access into greater digital usage.
The country’s relatively low adoption of banking applications and online banking shows why financial inclusion and financial digitisation are not the same thing. The planned UPI-inspired payments infrastructure, alongside domestic fintech providers and expanding electronic-money regulation, could help close that gap.
The opportunity is significant, but so are the constraints. Digital payments can improve the movement of money within the economy, yet they cannot independently resolve foreign-exchange shortages or the country’s broader dependence on energy-related activity.
For Trinidad and Tobago, the emerging payments infrastructure is therefore best understood as part of a wider economic-modernisation effort rather than as a standalone fintech project.

