


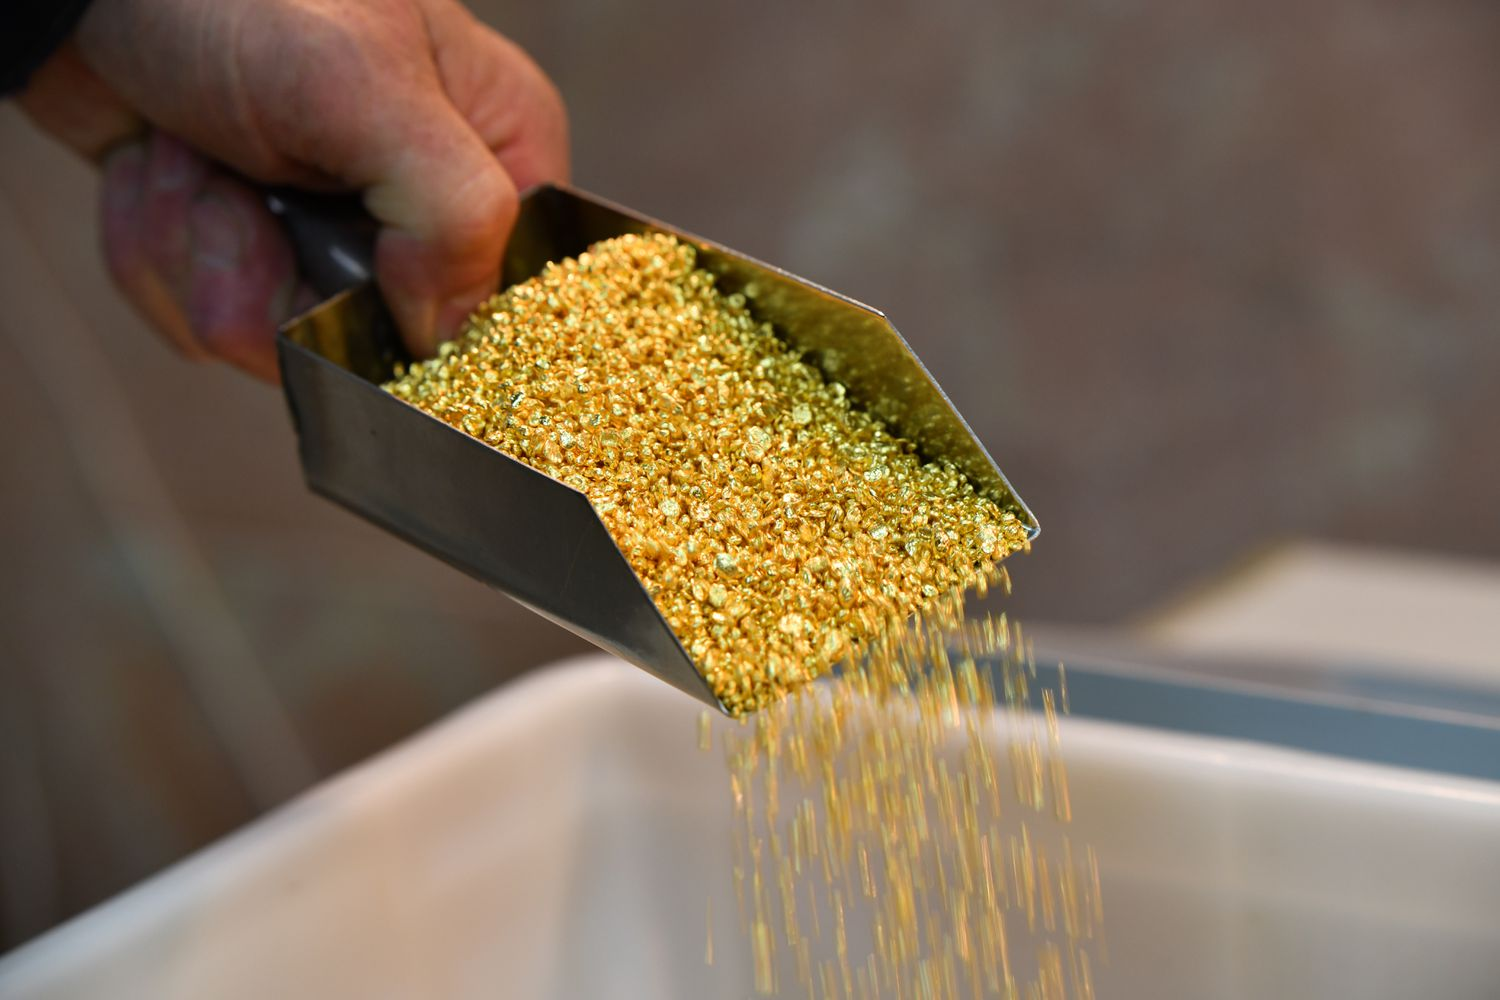
Gold remains a core reserve asset for central banks, but the question of reserve security increasingly extends beyond how much gold a country owns. Where bullion is stored, which legal system governs it, how quickly it can be mobilised and whether financial infrastructure remains available during a crisis can all affect its practical value.
The issue gained renewed attention on 2 September 2026, when De Nederlandsche Bank said it had moved roughly 86 tonnes of gold from New York and Ottawa to London. The Netherlands continued to own 612.4 tonnes, meaning the transaction changed the geographical distribution of the reserves rather than their total amount. The stated rationale was crisis preparedness, with London providing access to a deep physical gold market while reducing concentration in particular locations.
The Netherlands’ move illustrates a broader challenge for reserve managers: geographical diversification can reduce one type of risk while leaving other risks largely unchanged. A reserve spread across several locations may still depend on the same political relationships, legal frameworks, settlement infrastructure or communications systems.
What Makes Gold Important to Central Banks?
Gold differs from many other reserve assets because it does not depend on a corporate issuer making a promised payment.
A gold bar does not represent a conventional corporate debt obligation, and therefore does not carry the same type of issuer credit risk associated with bonds or deposits. This characteristic has helped gold maintain a role in official reserves.
But the absence of conventional credit risk does not mean gold is free of risk.
Central banks also have to consider:
- Custody risk — whether bullion is securely held and independently accounted for.
- Jurisdictional risk — whether foreign authorities could restrict access.
- Political risk — whether geopolitical developments could affect control or mobilisation.
- Operational risk — whether transport, communications or infrastructure remain functional.
- Liquidity risk — how quickly the asset can be converted into usable funds.
- Settlement risk — whether transactions can be completed when financial systems are under stress.
The distinction is important because physical ownership and practical accessibility are not always the same thing.
The Netherlands and the Case for Geographic Diversification
The Netherlands’ decision to relocate roughly 86 tonnes of gold illustrates one approach to reserve management.
The country did not increase its gold holdings. Instead, it changed where part of its 612.4-tonne reserve was held.
London has long been an important international centre for physical gold trading and official bullion custody. Holding reserves there can therefore provide access to established market infrastructure.
At the same time, reducing the concentration of bullion in particular jurisdictions can limit exposure to a single location.
The underlying principle is straightforward: if one storage location becomes inaccessible, other holdings may remain available.
However, geographical diversification is only effective when the risks associated with different locations are sufficiently independent.
When Different Locations Share the Same Risk
A reserve split between London, New York and Ottawa may appear highly diversified on a map. But physical distance does not necessarily create independent risk.
Several locations could be exposed to common disruptions involving:
- geopolitical conflict;
- sanctions;
- cyberattacks;
- financial-market disruption;
- restrictions on capital movements;
- settlement-system failures;
- communications outages; or
- coordinated political responses to a major crisis.
This creates what can be described as common-mode risk.
The problem is similar to diversification elsewhere in financial markets. The Long-Term Capital Management crisis in 1998 demonstrated how positions that appeared diversified across markets could become highly correlated during periods of severe stress.
The same principle can apply to reserve custody. Three different vaults may still depend on overlapping legal, political and financial infrastructure.
For reserve managers, the relevant question is therefore not simply:
How many countries hold our gold?
It is:
How independent are the risks attached to those locations?
History Shows Why Custody and Sovereignty Can Diverge
Historical experience demonstrates that foreign custody can produce very different outcomes depending on the geopolitical environment.
Belgium provides one example.
The National Bank of Belgium reported 227.4 tonnes of gold at the end of 2024, valued at €18.36 billion at the time. Most of the country’s gold was held at the Bank of England, with smaller quantities at the Bank for International Settlements and the Bank of Canada, while only a small amount was held domestically.
Foreign custody itself does not automatically represent a weakness. London is a major international bullion market and an established centre for official gold custody.
The historical experience of Belgium, however, demonstrates how rapidly the meaning of “safe custody” can change during a geopolitical crisis.
In 1939, Belgium moved a substantial amount of its gold abroad and entrusted part of the remaining holdings to the Banque de France. Following Germany’s invasion, the gold was transferred to Dakar in French West Africa. After France fell, the political circumstances surrounding the assets changed again, and French authorities ultimately delivered the remaining Belgian gold to the German Reichsbank.
In autumn 1944, the Bank of France transferred 198.4 tonnes of fine gold to the National Bank of Belgium under an agreement between the institutions.
The episode illustrates an important distinction: the physical asset can remain intact while the political arrangements governing access to it change.
Czechoslovakia experienced a related problem in 1939. The Bank for International Settlements executed an instruction transferring gold held at the Bank of England to the German Reichsbank after an order that was subsequently understood to have been issued under duress.
History also provides examples in which foreign custody supported sovereign control.
Canada served as a wartime sanctuary for European central-bank gold, while Norway’s decision to move reserves abroad helped preserve control when its domestic environment was threatened in 1940.
These cases do not establish that domestic or foreign custody is universally safer. Instead, they demonstrate that the appropriate reserve structure depends on the nature of the crisis being considered.
Domestic Gold Versus Foreign Custody
Repatriating gold can reduce exposure to foreign jurisdictions.
Domestic custody can give a central bank greater direct control over its physical reserves and reduce the possibility that another jurisdiction restricts access.
But concentrating gold entirely at home introduces another form of risk.
A country could become more exposed to domestic political instability, physical infrastructure disruption, natural disasters, security threats or a single national system failure.
Foreign custody can provide access to international bullion markets and established liquidity infrastructure. Domestic custody can provide greater sovereign control.
The reserve-management problem is therefore not simply about choosing one location.
It is about balancing:
Sovereign control + market liquidity + jurisdictional diversification + operational resilience.
Ownership Does Not Guarantee Immediate Access
Recent developments in the international financial system have reinforced the distinction between ownership and usability.
The European Union has immobilised approximately €210 billion in Central Bank of Russia assets. At the end of June 2026, Euroclear Bank reported that €202 billion of its €241 billion balance sheet related to sanctioned Russian assets.
Russia’s circumstances differ fundamentally from those of European Union member states. The broader institutional lesson, however, concerns the relationship between legal ownership and practical access.
An asset may remain legally attributable to its owner while the jurisdiction in which it is held controls the financial infrastructure required to transfer or mobilise it.
For reserve managers, this creates three distinct questions:
1. Asset safety
Does the underlying reserve retain its economic value?
2. Access safety
Can the sovereign effectively control and access the asset?
3. System safety
Can the reserve be converted into usable purchasing power when markets, settlement systems, communications or transportation networks are disrupted?
Gold can perform strongly against the first test while encountering difficulties under the second or third.
The Difference Between Market Value and Effective Liquidity
The headline value of a country’s gold reserves does not necessarily represent the amount of liquidity that can be generated immediately during a severe crisis.
Physical bullion may have a deep international market under normal conditions. But crisis conditions can introduce delays, transportation constraints, settlement problems, legal restrictions or wider market dislocation.
The source article points to a July 2026 IMF note recommending a risk-based approach to assessing gold’s effective liquidity rather than relying exclusively on headline market value.
This distinction is particularly important for central banks because reserves are ultimately held to support financial and monetary resilience.
An asset that retains value but cannot be mobilised when liquidity is urgently required may provide less protection than its balance-sheet valuation suggests.
Why Central Banks Need Stress Tests for Reserve Geography
Traditional financial stress testing generally focuses on banks, liquidity positions and financial institutions.
Reserve management can apply a similar framework to physical custody and financial infrastructure.
Instead of asking only what happens if one vault becomes unavailable, central banks can examine scenarios in which several apparently independent systems experience disruption simultaneously.
For example:
- What happens if London and North American markets are disrupted at the same time?
- What happens if physical ownership remains intact but settlement systems stop functioning?
- What happens if bullion can be accessed but the payment infrastructure needed to monetise it is unavailable?
- What happens if sanctions or capital controls restrict transactions?
- What happens if communications networks fail?
- What happens if transportation infrastructure is disrupted?
These scenarios shift reserve management away from identifying a single “safest” location.
The objective becomes maintaining multiple functioning options.
Reverse Stress Testing and Reserve Resilience
A further approach is reverse stress testing.
Instead of beginning with an assumed crisis and calculating its effects, policymakers can begin with the outcome they most want to prevent: a reserve system becoming unusable when it is most needed.
They can then work backwards to identify which combinations of events could produce that result.
Such an analysis could examine:
- custody failures;
- legal restrictions;
- settlement interruptions;
- geopolitical shocks;
- cyber disruptions;
- transportation failures;
- market-liquidity shortages; and
- simultaneous failures across supposedly independent jurisdictions.
This framework treats reserve resilience as a system rather than a collection of individual assets.
A diversified reserve architecture could therefore combine domestic physical holdings, international bullion custody, foreign-exchange reserves, central-bank swap arrangements and alternative settlement channels.
Each component serves a different function.
Can Domestic Gold Become More Liquid?
There is also a longer-term question around how domestically held gold can be connected to liquidity without requiring permanent relocation to an international financial centre.
One possible framework involves maintaining bullion under sovereign custody while establishing independent verification and pre-agreed standards that could support temporary liquidity arrangements.
Such systems would not eliminate jurisdictional or operational risk. But they could reduce the extent to which physical location determines whether a reserve asset can be mobilised.
The broader objective is to create multiple routes from reserve assets to usable liquidity.
What This Means for European Reserve Management
The Netherlands’ latest move illustrates one part of a broader European debate about reserve resilience.
A more geographically distributed reserve can reduce dependence on individual locations. But geographical diversification should not be treated as the final measure of resilience.
The Swiss National Bank, for example, explicitly considers country risk in its reserve-management framework, including the possibility that a foreign state could restrict access to assets held within its jurisdiction.
Its gold allocation is approximately 70% domestic, 20% in London and 10% in Canada.
That structure illustrates the trade-off between sovereign custody and international market access.
There is no single allocation that can protect against every conceivable crisis. The relevant question is whether the reserve system retains sufficient alternatives when its underlying assumptions are challenged.
Conclusion
Gold remains an important reserve asset because it does not depend on a conventional corporate issuer and can provide diversification within official reserves. But physical ownership alone does not determine reserve resilience.
The location of bullion affects jurisdictional exposure, market access and operational flexibility. At the same time, different locations can remain connected through common political, legal and financial systems.
The experience of Belgium and Czechoslovakia during the Second World War demonstrates how geopolitical events can change the practical meaning of custody. More recent sanctions-related developments demonstrate that legal ownership and operational access can also diverge.
For central banks, the broader reserve-management challenge is therefore to build redundancy across custody, legal authority, settlement infrastructure and liquidity channels.
The Netherlands’ decision to redistribute roughly 86 tonnes of gold is one example of that approach. Its significance lies less in the movement of bullion itself than in the question it raises: Can a reserve remain accessible when the systems surrounding it are under stress?
Gold may have no issuer. But every bar still has an address—and that address can become part of the risk calculation.

