
Introduction
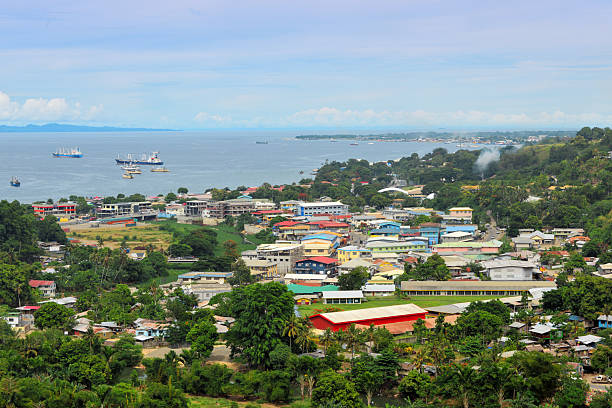
Mobile money adoption in the Solomon Islands is emerging as a direct response to a geographic constraint rather than a consumer convenience trend. Spread across nearly 1,000 islands in the South Pacific, the country presents financial institutions with logistical costs that make conventional branch and ATM networks difficult to sustain across dispersed island communities. For a large share of the population, mobile-based financial services represent the first practical point of access to formal finance rather than an upgrade to an existing one.
The shift matters globally as a case study in financial inclusion strategy for geographically fragmented economies, and it is being closely watched by development finance institutions including the World Bank, the International Finance Corporation (IFC) and the GSMA. Domestically, it affects a population of well under one million people, a large share of whom live outside the commercial centre of Honiara on Guadalcanal.
This article examines the mobile-money infrastructure now operating in the Solomon Islands, the underlying payment-settlement systems supporting it, the economic and inclusion factors driving adoption, and the risks and limitations that remain.
What Mobile Money Access Means in the Solomon Islands Context
Mobile money refers to financial services — deposits, withdrawals, transfers, bill payments and remittances — conducted through a mobile telephone rather than a conventional bank account. In the Solomon Islands, this distinction is functionally significant: research cited by the GSMA found that historically only around one-quarter of Solomon Islanders held bank accounts, with much of the remaining population relying on informal financial arrangements or excluded from formal finance altogether.
Because building bank branches and transporting physical cash across hundreds of islands carries high logistical costs, mobile money is positioned by the Central Bank of Solomon Islands and telecommunications operators as an access mechanism rather than a convenience feature.
How Mobile Money Infrastructure Operates
The most significant development in this space has been M-SELEN, launched commercially in 2023 by Our Telekom with support from the UN Capital Development Fund and the government of Australia. M-SELEN became the country’s first licensed mobile-money service, allowing customers to deposit and withdraw funds through agents, transfer money, purchase airtime and pay bills without holding a conventional bank account.
A distinguishing operational feature is that M-SELEN functions through both a smartphone application and USSD, a text-based protocol that does not require mobile internet access or a smartphone. Operator Telekom Digital has reported that the service now has more than 450,000 registered customers, supported by more than 5,500 agents and 4,500 merchants nationwide, with international remittance services added this year.
Other providers have taken parallel approaches. EziPei operates a mobile wallet designed to function across different mobile networks and on both smartphones and basic handsets, offering person-to-person transfers, merchant payments, bill payments and remittances. Bank South Pacific (BSP), one of the country’s main financial institutions alongside ANZ and Pan Oceanic Bank, has expanded mobile banking services allowing customers to transfer funds, check balances and purchase prepaid electricity, water and telephone credit remotely.
Key Factors Influencing Adoption
Several structural factors shape how mobile money has developed in the Solomon Islands:
Geographic dispersion. The archipelago’s nearly 1,000 islands make physical banking infrastructure costly to build and maintain relative to the customer base it would serve, a factor cited consistently by industry and development-finance sources as the primary driver of mobile-first financial access.
Device accessibility. Because M-SELEN and similar services operate over USSD as well as smartphone applications, they remain accessible to users without smartphones or reliable mobile internet — a design consideration considered critical in a market where universal smartphone penetration cannot be assumed.
Underlying settlement infrastructure. In April 2024, the Central Bank of Solomon Islands launched the Solomons Automated Transfer System (SOLATS), a real-time gross settlement platform developed with technical assistance from the IFC and support from Australia, New Zealand and the World Bank. SOLATS allows financial institutions to settle transactions electronically in real time, providing the interbank infrastructure that mobile-money and banking services depend on, even though the system itself is not directly visible to consumers.
National inclusion strategy. The Central Bank of Solomon Islands has pursued successive national financial inclusion strategies since 2011. Its third strategy, covering 2021 to 2025, identified digital financial services as a central mechanism for extending affordable financial products to underserved communities, particularly women and rural households. According to the central bank, the Solomon Islands was the first country globally to explicitly incorporate women’s financial inclusion into a national financial inclusion strategy.
Costs, Impact and Implications
Macroeconomic context. The International Monetary Fund (IMF) projects the Solomon Islands economy will grow by approximately 2.6% this year, with nominal gross domestic product reaching approximately $1.88 billion. The IMF has also flagged declining logging production, infrastructure constraints, climate vulnerability and the need to generate employment for a young, growing population as ongoing structural challenges — factors that shape the broader environment in which financial inclusion efforts are occurring.
Merchant-side cost implications. A national QR-code payment standard, under consultation in 2026 by the Central Bank of Solomon Islands in partnership with Australia, is intended to address payment fragmentation by allowing a single QR standard across participating wallets and financial institutions rather than requiring merchants to support multiple, provider-specific codes. Printing a QR code carries substantially lower cost than installing and maintaining conventional card-payment terminals, a factor the central bank has identified as relevant to extending electronic payments into underserved and remote communities.
H3: Banks vs. Telecom-Led Fintech Providers
Unlike markets with venture-capital-funded neobanks or wealthtech platforms, financial innovation in the Solomon Islands is being driven primarily by telecommunications operators, established banks and specialised payment providers rather than independent fintech start-ups. Telecom-led services such as M-SELEN and EziPei have scaled by leveraging existing mobile network reach, while banks including BSP have extended mobile banking features onto that same infrastructure rather than competing to replace it.
Risks and Limitations
Several limitations remain relevant to assessing the sector’s development. Registered mobile-money accounts do not necessarily indicate active or sustained usage, and independently verified active-user data specific to the Solomon Islands is limited relative to operator-reported registration figures. Device and network accessibility, while broader than smartphone-only alternatives, still depends on baseline mobile network coverage across a geographically dispersed island chain, which is not uniform nationally. The proposed unified QR-code standard remains at the consultation stage as of 2026 and has not yet been implemented. Longer-term structural economic risks identified by the IMF — including climate vulnerability and reliance on natural-resource sectors such as logging and fisheries — remain independent of, and are not resolved by, financial-inclusion technology gains.
Outlook
The trajectory of financial access in the Solomon Islands will likely continue to depend on the interaction between mobile-money adoption, underlying settlement infrastructure such as SOLATS, and planned interoperability measures including the proposed national QR standard. Development-finance institutions including the World Bank and IFC remain engaged in supporting the underlying payment infrastructure, suggesting continued institutional investment in the sector. Whether registered mobile-money usage translates into sustained formal financial inclusion, particularly among women and rural households targeted by national strategy, will depend on continued affordability and accessibility on the devices already in common use.
Conclusion
Financial inclusion in the Solomon Islands is being shaped less by consumer preference than by geography. Mobile-money services such as M-SELEN and EziPei, combined with the real-time settlement infrastructure introduced through SOLATS and a proposed unified QR-code standard, represent a layered approach to extending formal financial access across a dispersed island nation where physical banking infrastructure remains costly to sustain. Macroeconomic and structural challenges identified by the IMF continue to operate independently of these gains, meaning technology-driven inclusion addresses access without resolving broader economic vulnerabilities facing the country.

